The Market in Pictures, December 13
Our team looks at a lot of research throughout each day. A few charts that caught our eye this week, and the way they fit the unfolding puzzle of evidence:
Dave: Government inflation measures are trying to settle into the 2-3% range
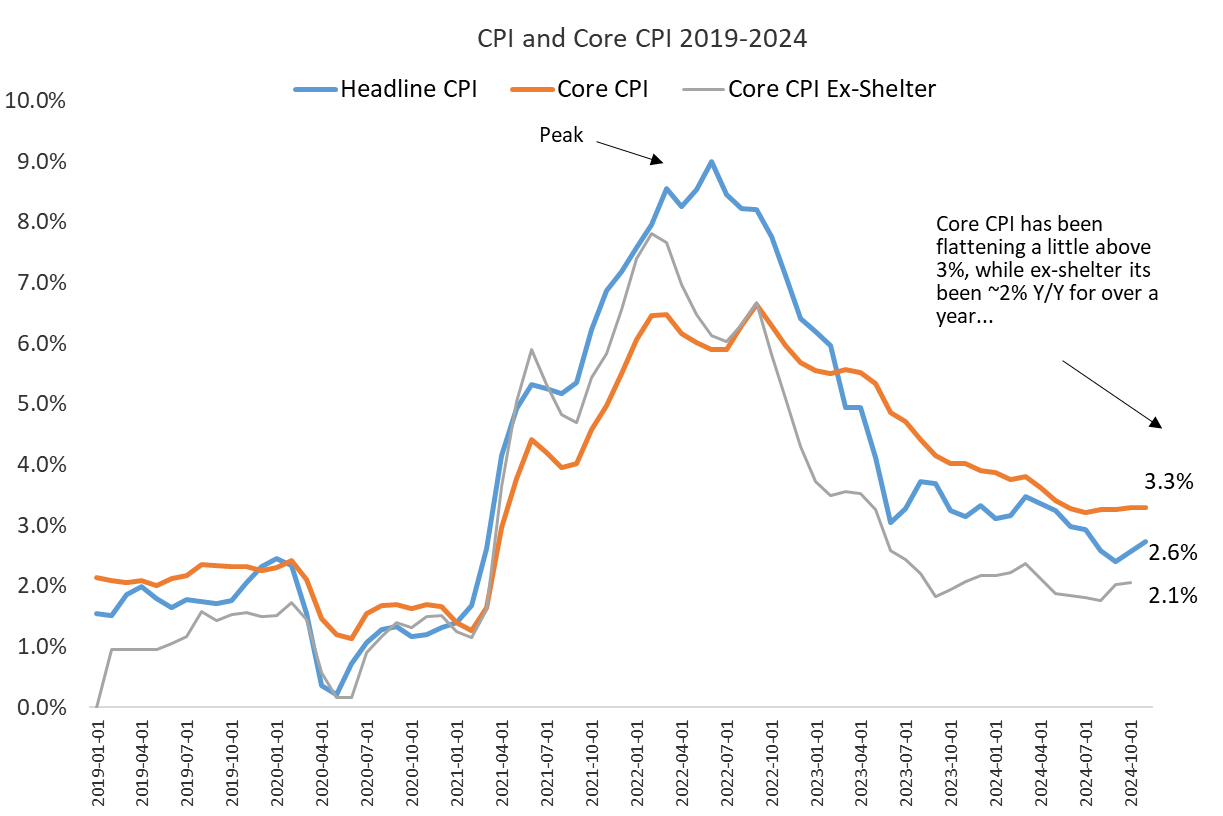 Source: Raymond James as of 12.11.2024
Brian: with services the entire source of inflation now that the price of goods has gone flat year-over-year
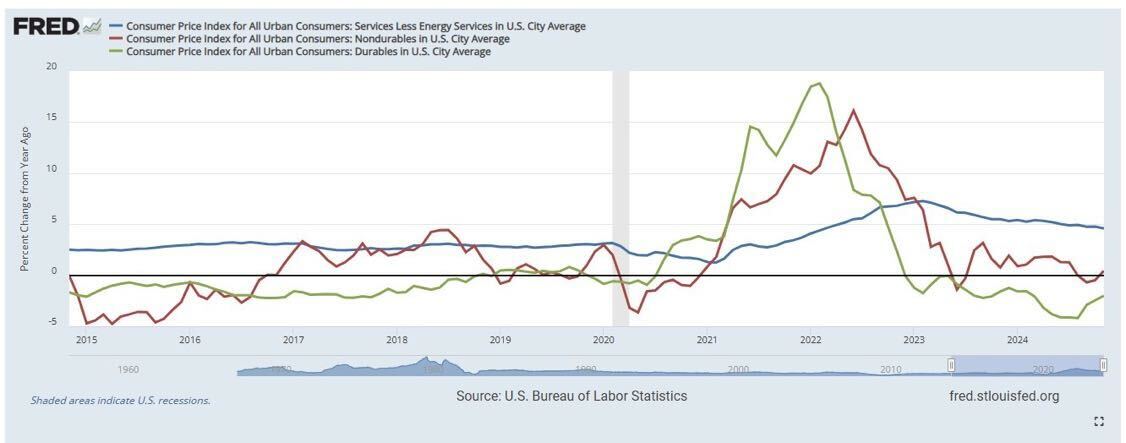 Data as of 12.11.2024
John Luke: that said, the % of inputs undergoing disinflation is no longer expanding
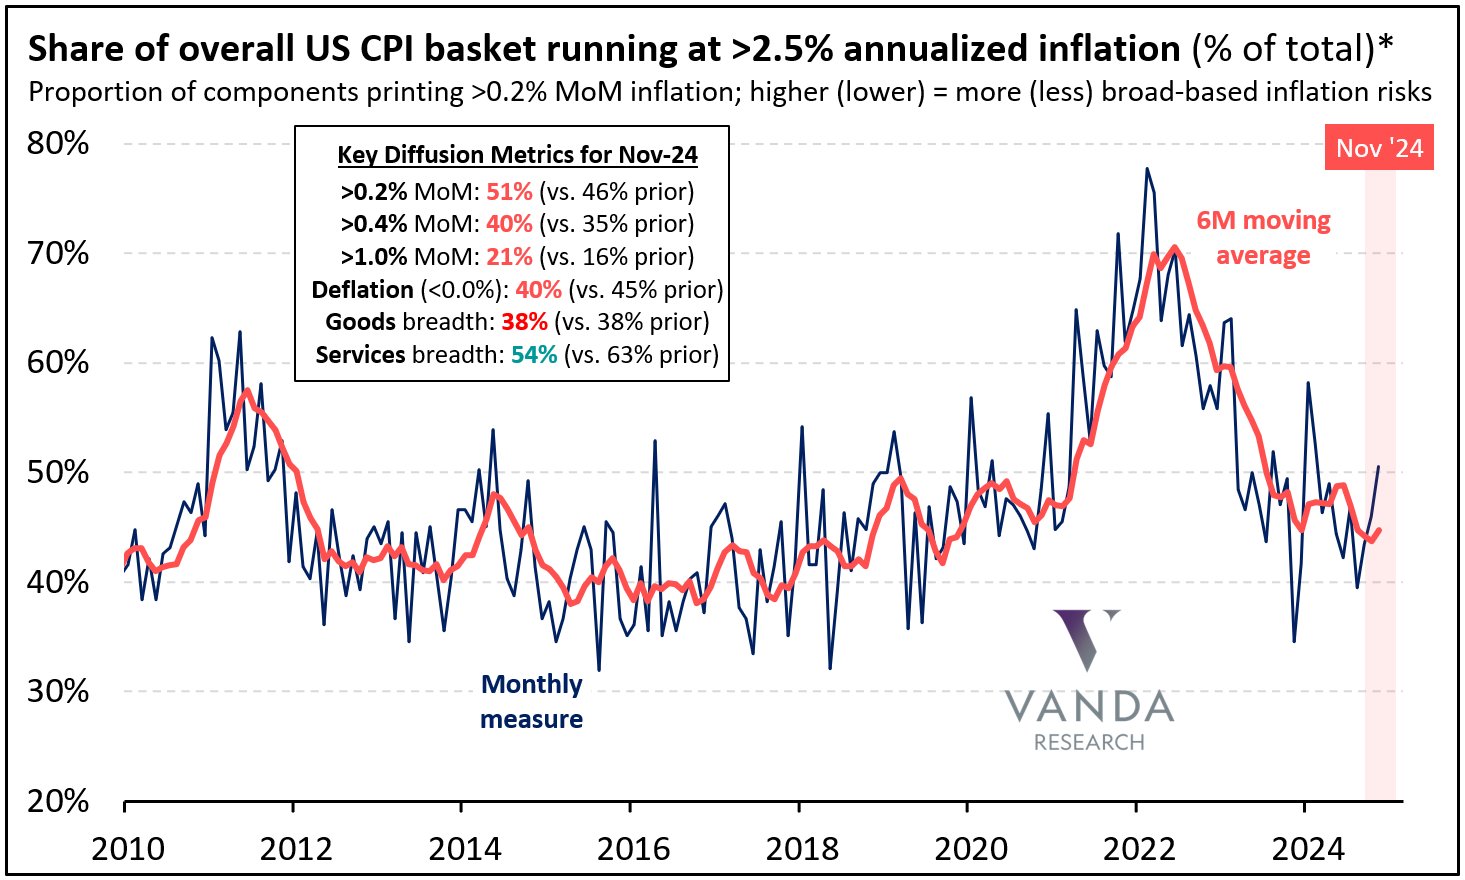 Source: Vanda Research as of 12.11.2024
John Luke: The US economy is still feeling the impact of COVID-era fiscal stimulus
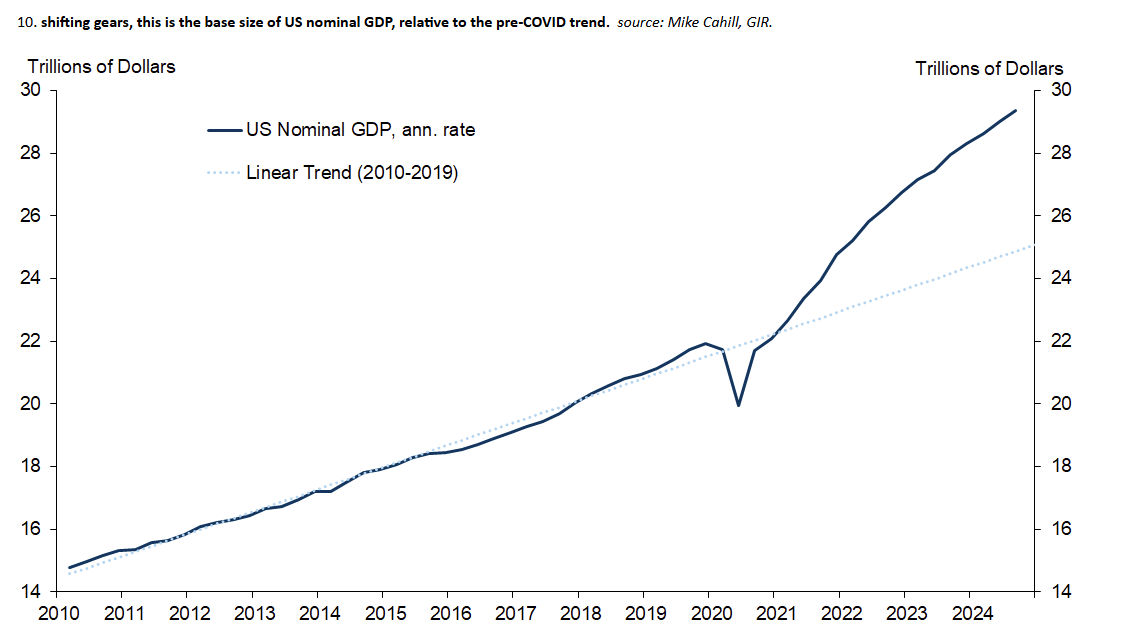 Source: Goldman Sachs as of November 2024
Brett: part of the reason there are no developed economies expecting a recession in 2025
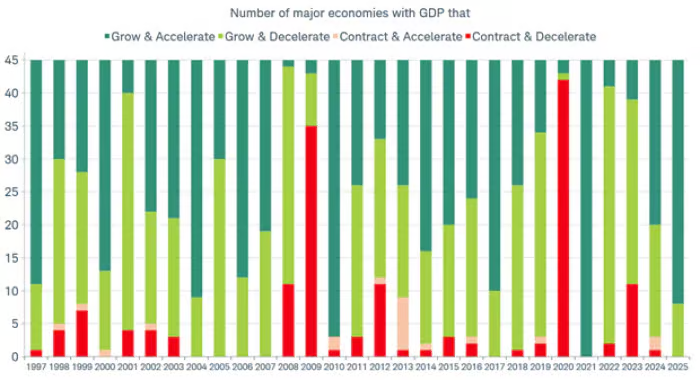 Source: Schwab as of 12.10.2024
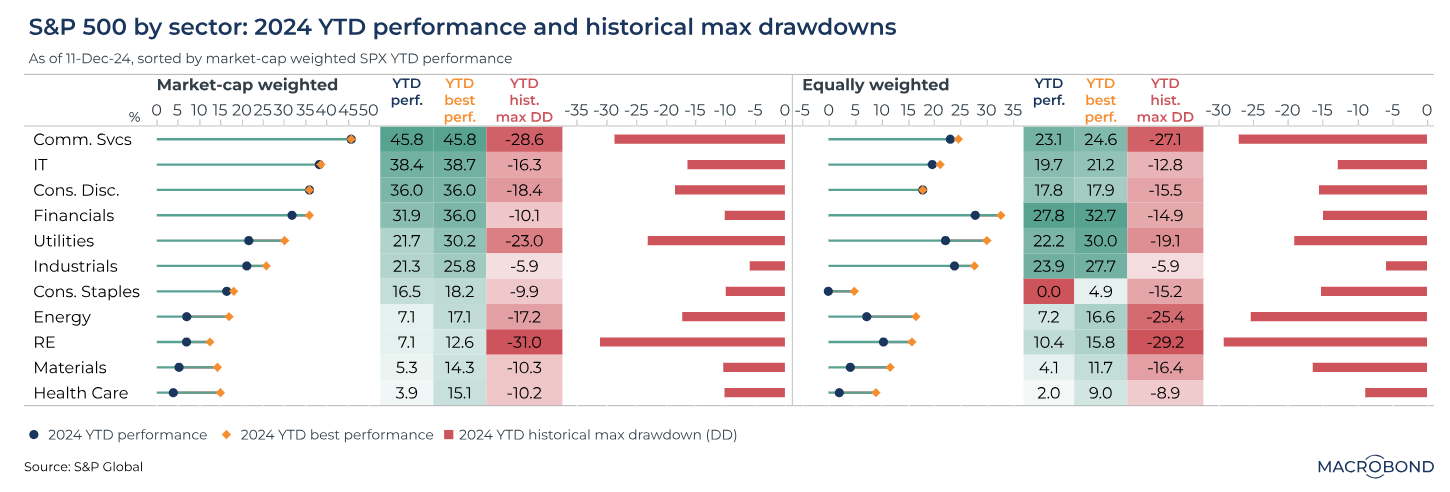
Beckham: We all know tech has been a great performer, but all sectors have had some degree of upside in 2024
 Joseph: partly due to the expectation that profit margins will continue to rise
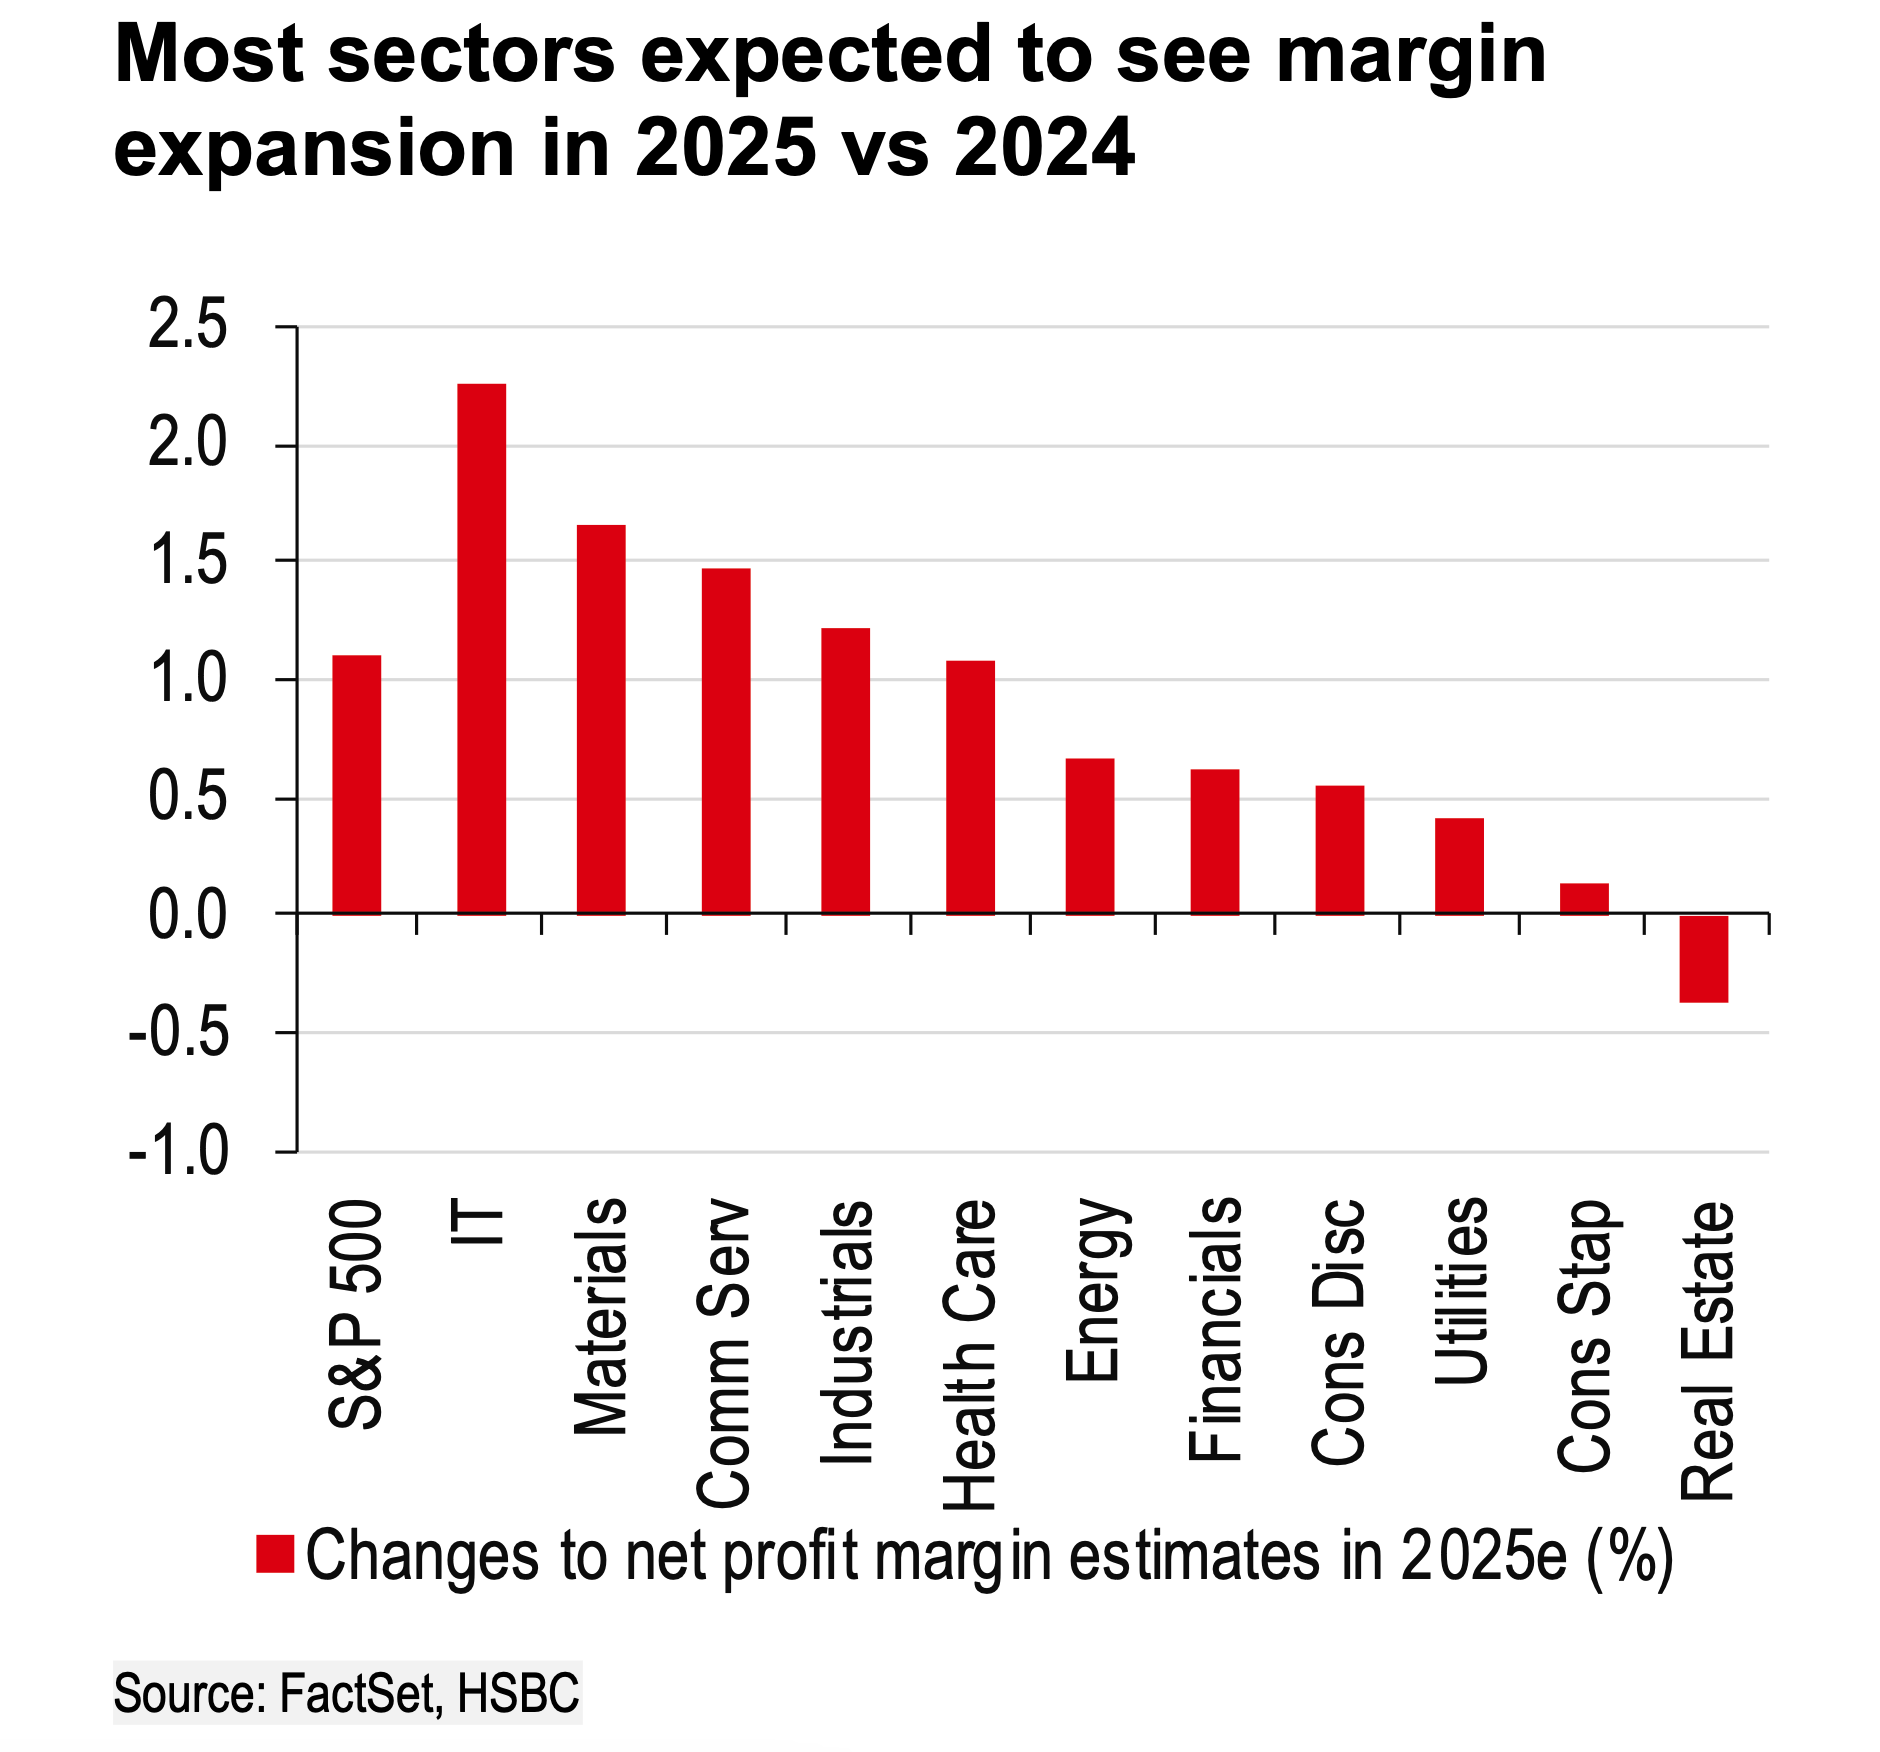 Data as of 12.09.2024 via Tker
Brad: Good reference for comparing this move to past moves from bear market lows
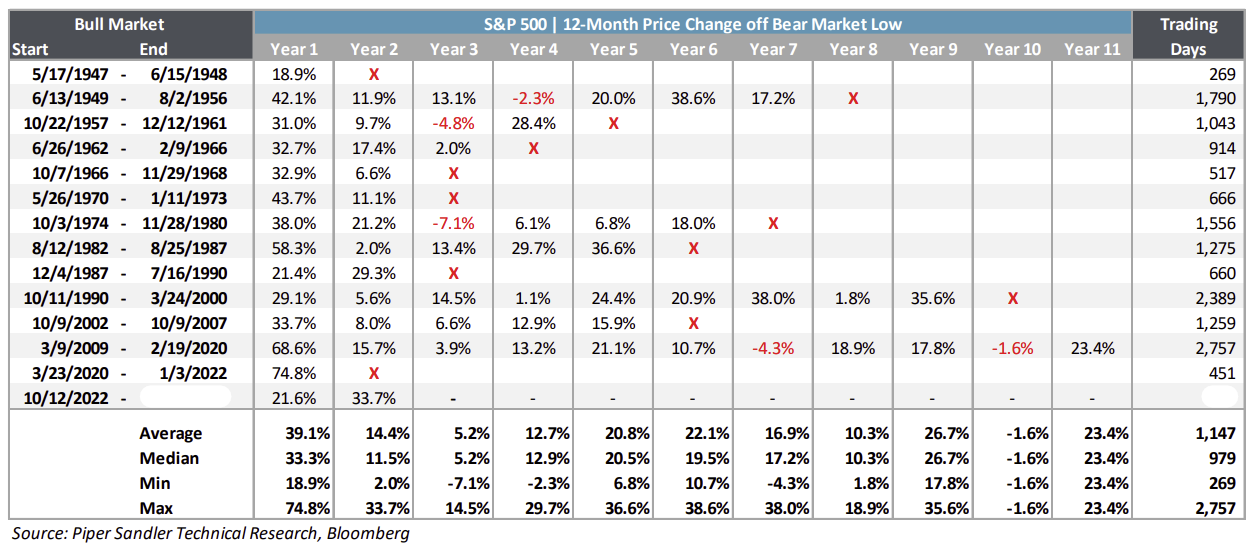 Data as of 12.09.2024
Arch: and regardless of the future path, comparisons to the 2000 top look downright silly
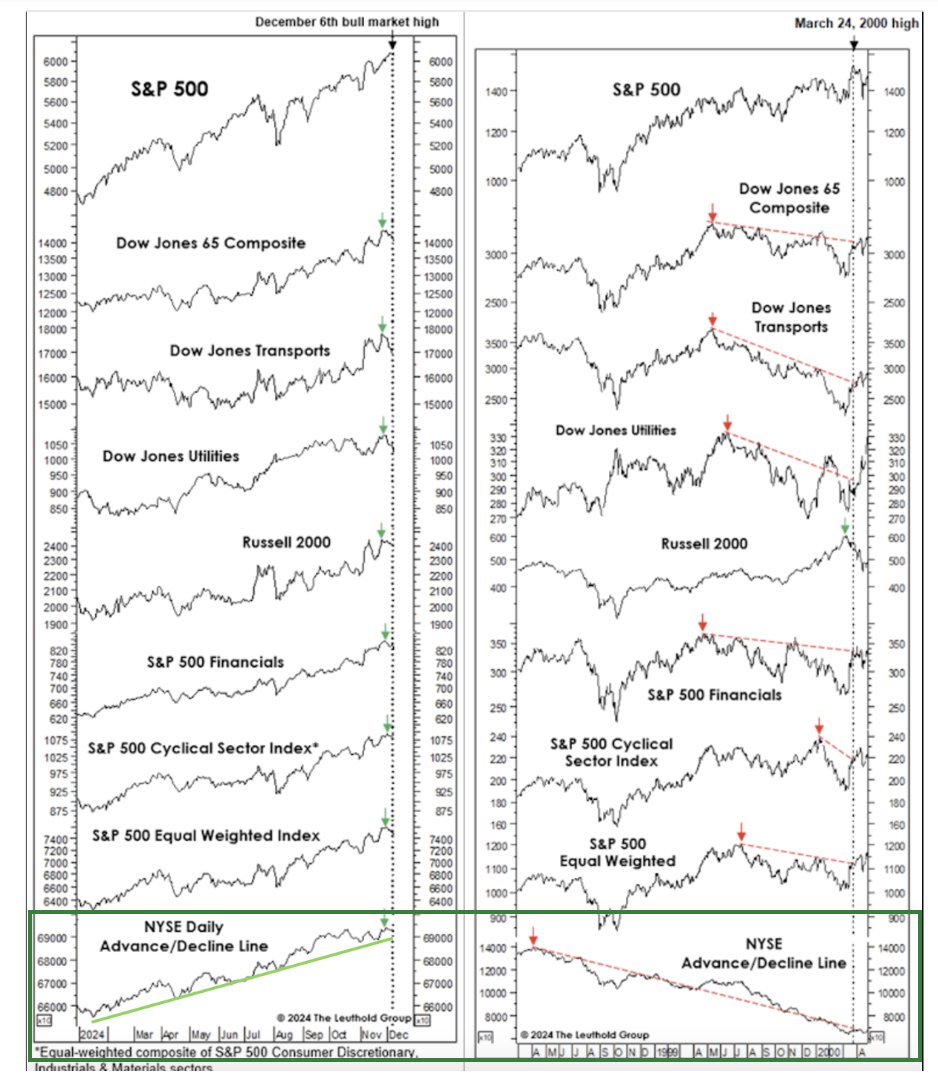 Source: @SethCL as of 12.06.2024
JD: It’s been another tough year for European stocks, one of the worst relative to the US
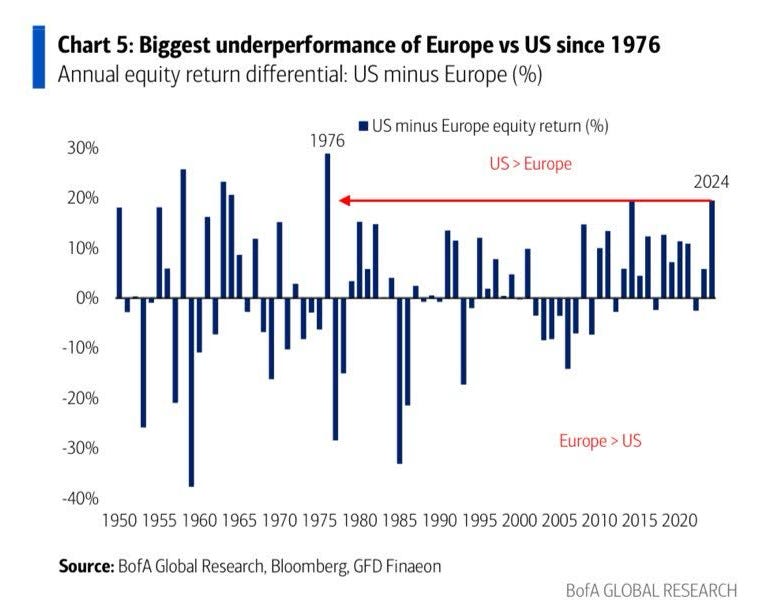 Data as of 12.06.2024
Beckham: and while the valuation discount has been a reason some have bought international stocks, once you adjust for sector composition the discount hasn’t yet been enough to stem the tide
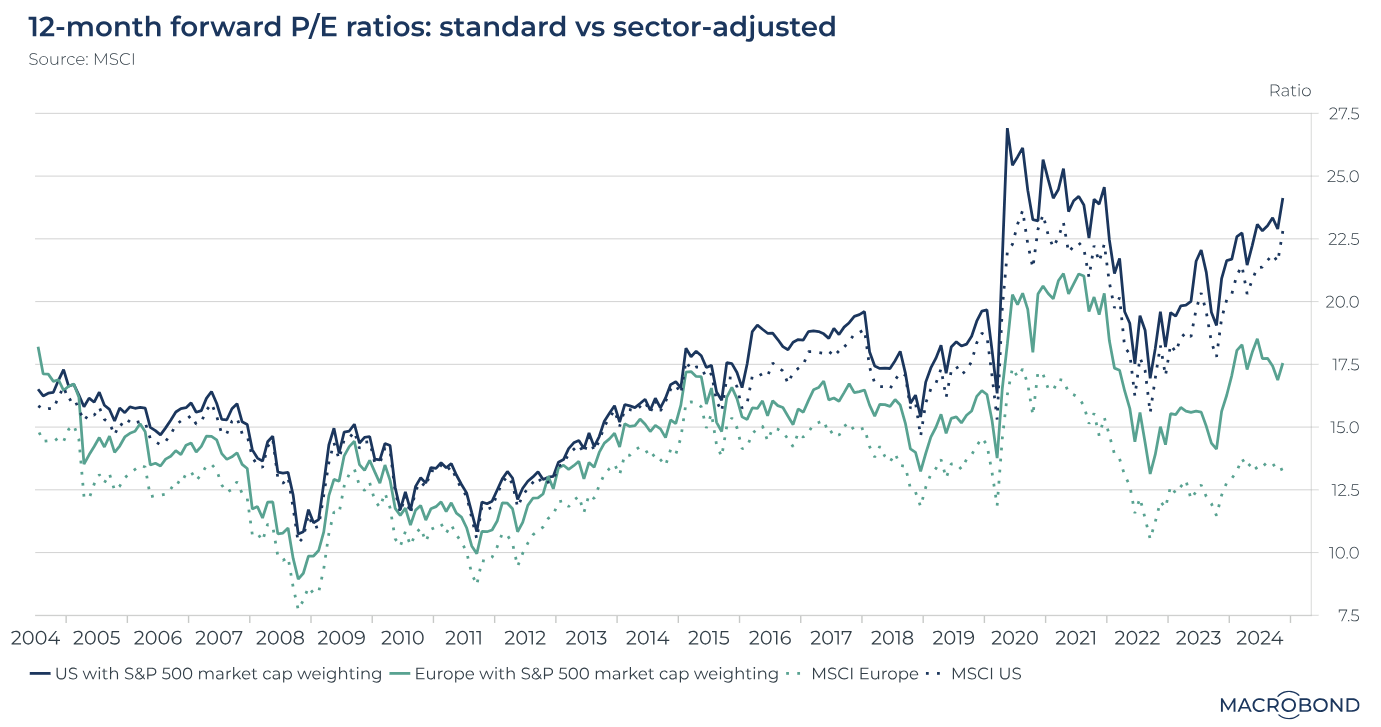 Data as of 12.12.2024
John Luke: It’s the money going out that’s expanding the government deficits, not the money coming in
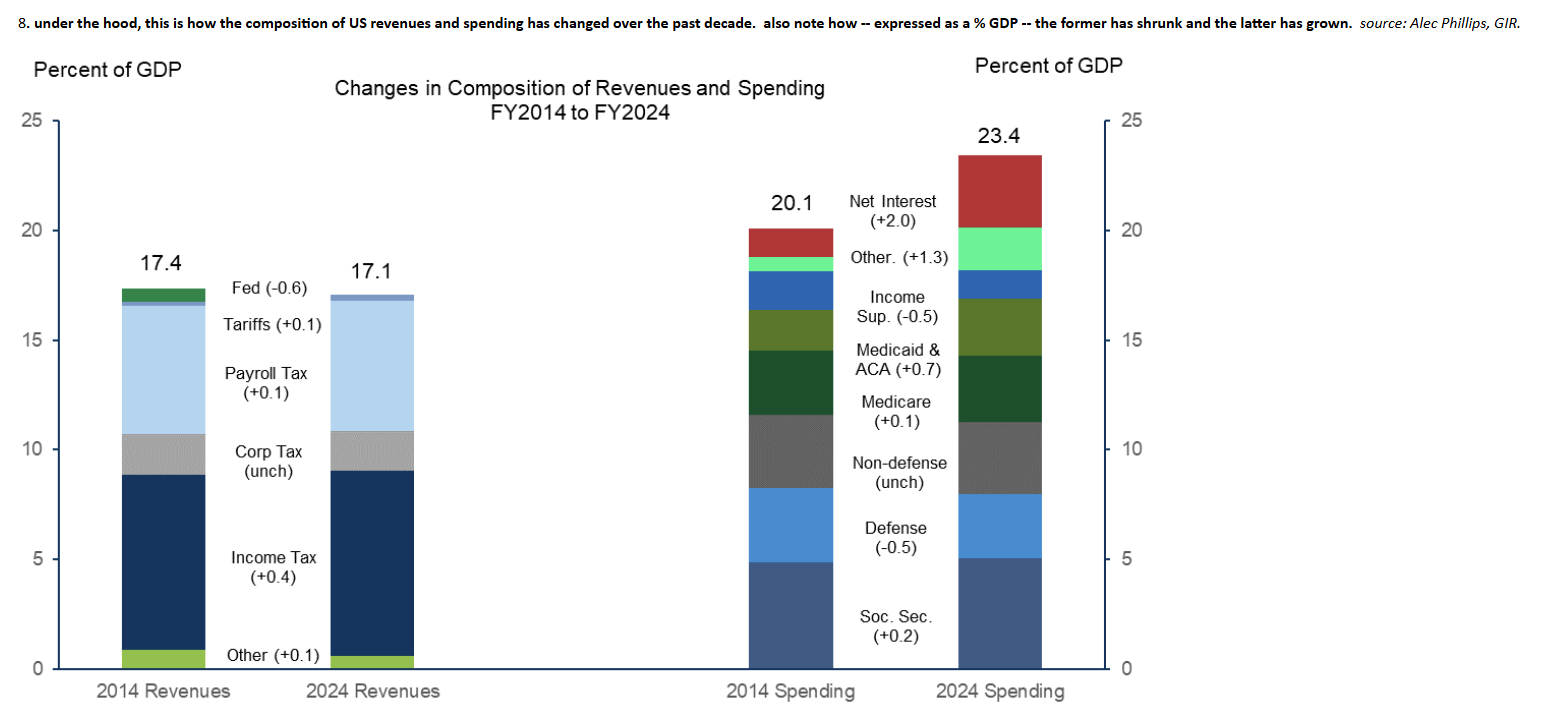 Source: Goldman Sachs as of 12.06.2024
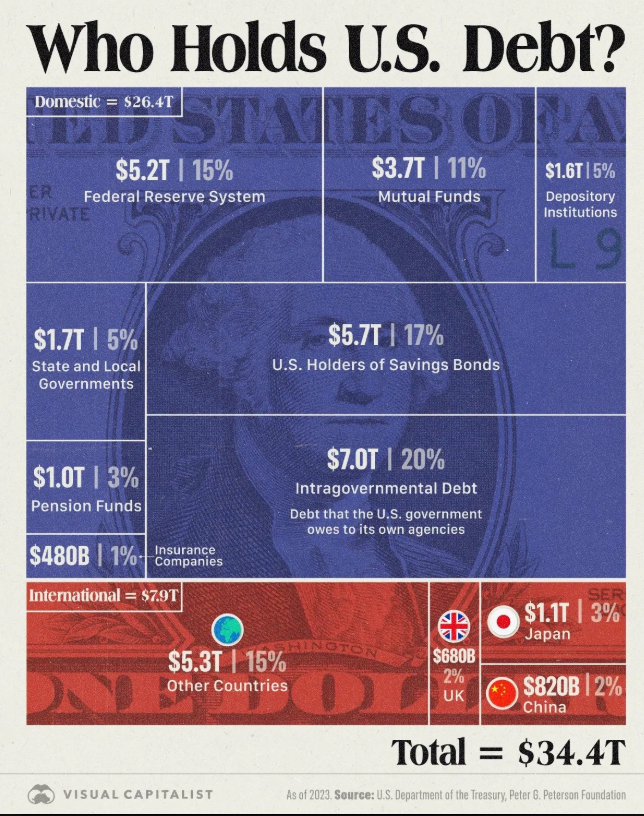
John Luke: and the expanding debt burden is increasingly falling on domestic holders
 Dave: Meanwhile, US consumers as a whole are thriving and reducing debt burdens
 Source: Goldman Sachs as of November 2024
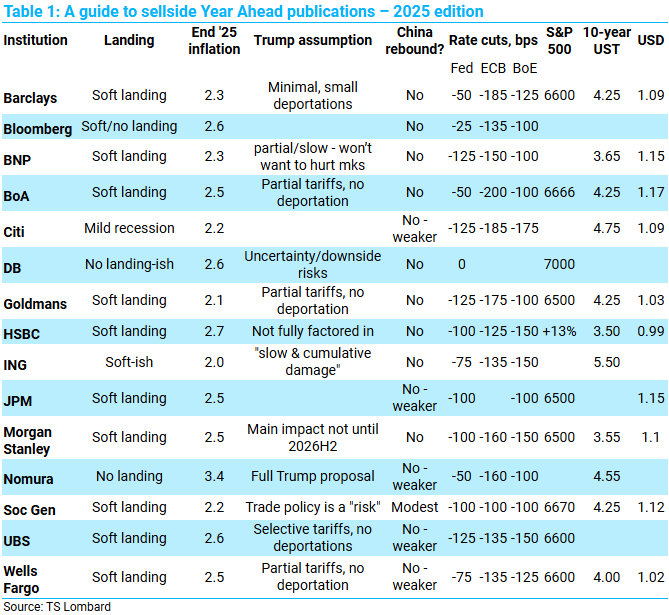
Joseph: After being caught flat-footed into the 2023 and 2024 equity rallies, strategists are getting more aggressive with 2025 price targets
 Data as of 12.12.2024
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed. Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially. This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible. Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level or skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2412-11.
The Investment Hub carries the full Aptus research library — manager research, market dashboards, models, and a studio that renders it all on your firm's letterhead.
Sign in Request access