The Market in Pictures, June 7
Our team looks at a lot of research throughout each day. A few charts that caught our eye this week, and the way they fit the unfolding puzzle of evidence:
Dave: The divergence between non farm payroll data and the household survey continues to be an example of the divergent thinking regarding economic strength
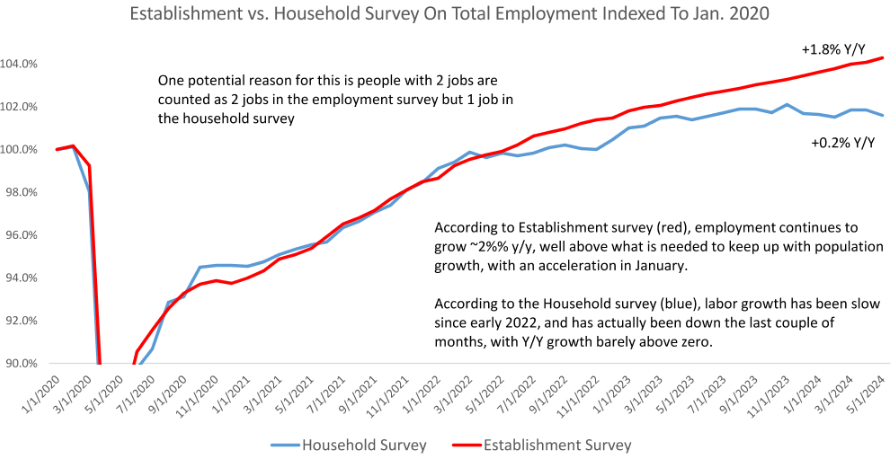 Source: Raymond James as of 06.06.2024
Dave: with the consumer continuing to spend at a decent pace
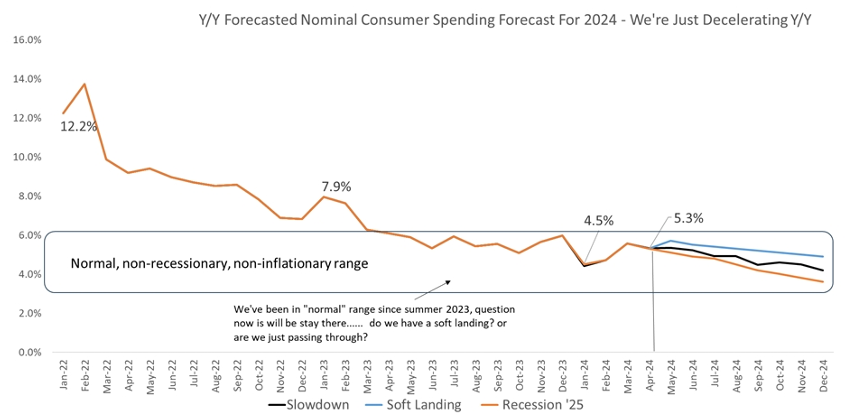 Source: Raymond James as of 06.03.2024
Brian: but GDP is tracking high or low depending on the week
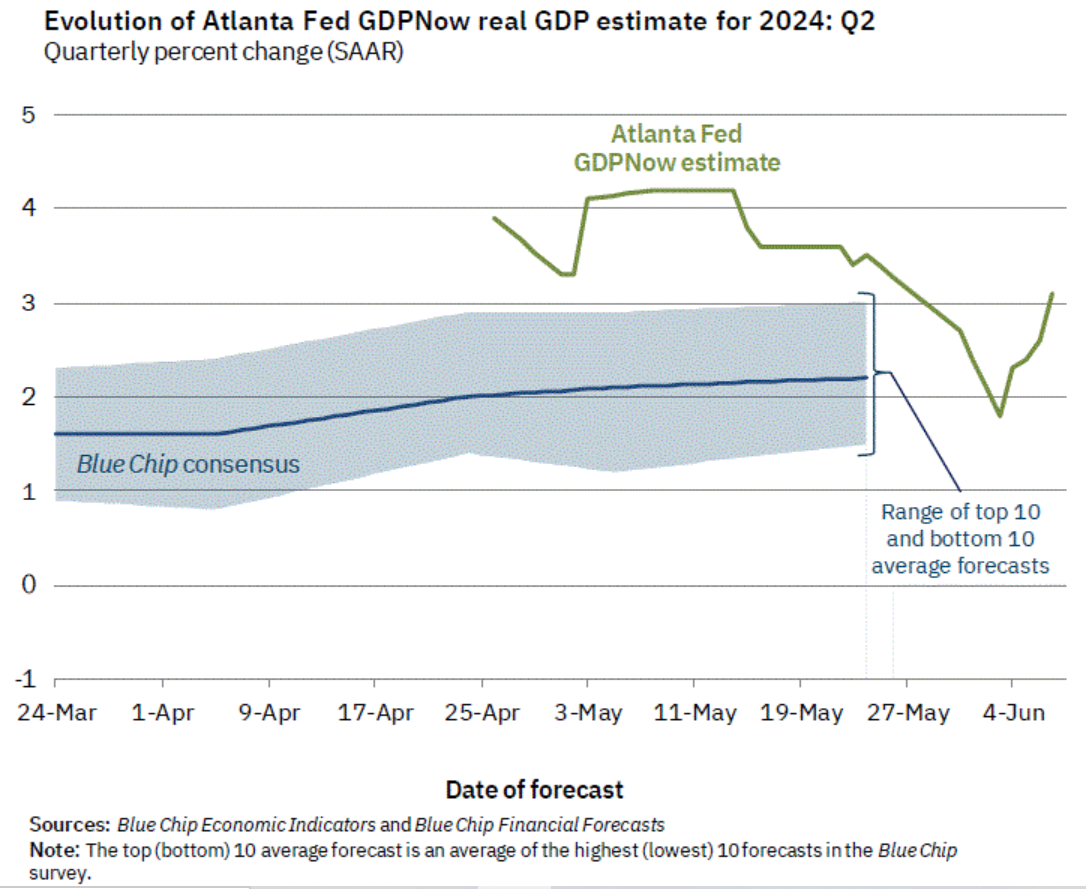 Source: Aptus via Atlanta Fed
Brett: and the odds of a recession fall
 Source: Apollo as of 06.06.2024
Arch: but some regional measures of manufacturing are falling deep into contraction territory
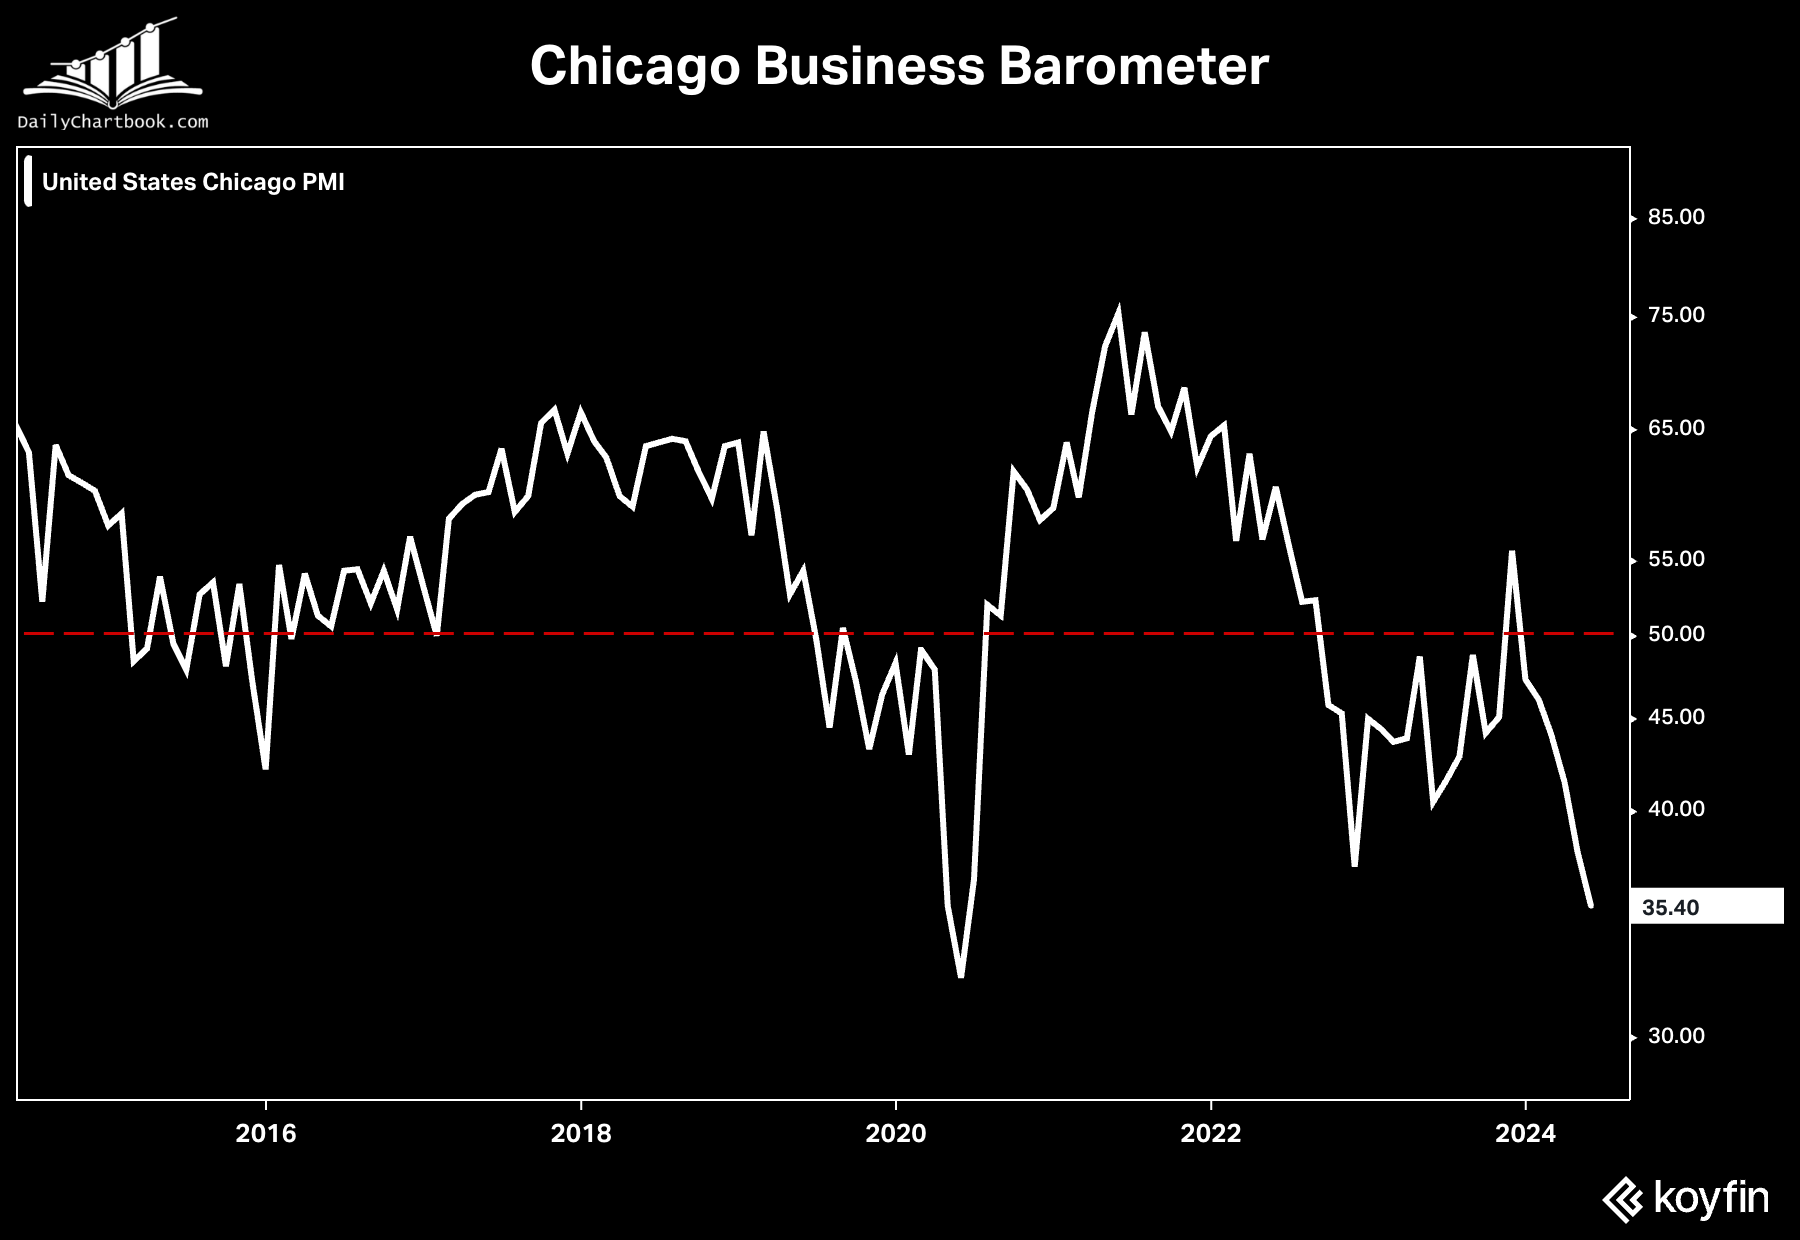 Data as of 05.31.2024
Beckham: and global measures are rising in unison
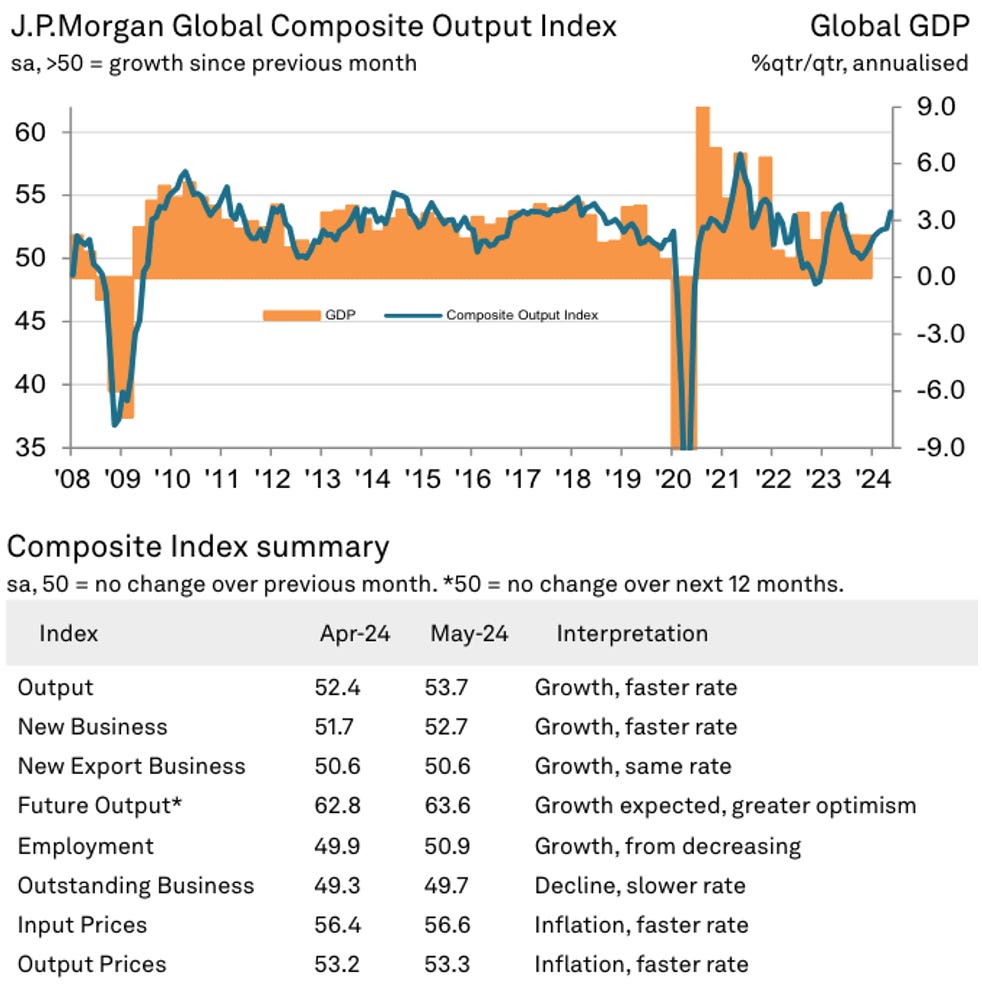 Source: S&P Global as of 06.03.2024
Joseph: but job openings in the US continuing to retreat from historic post-COVID highs
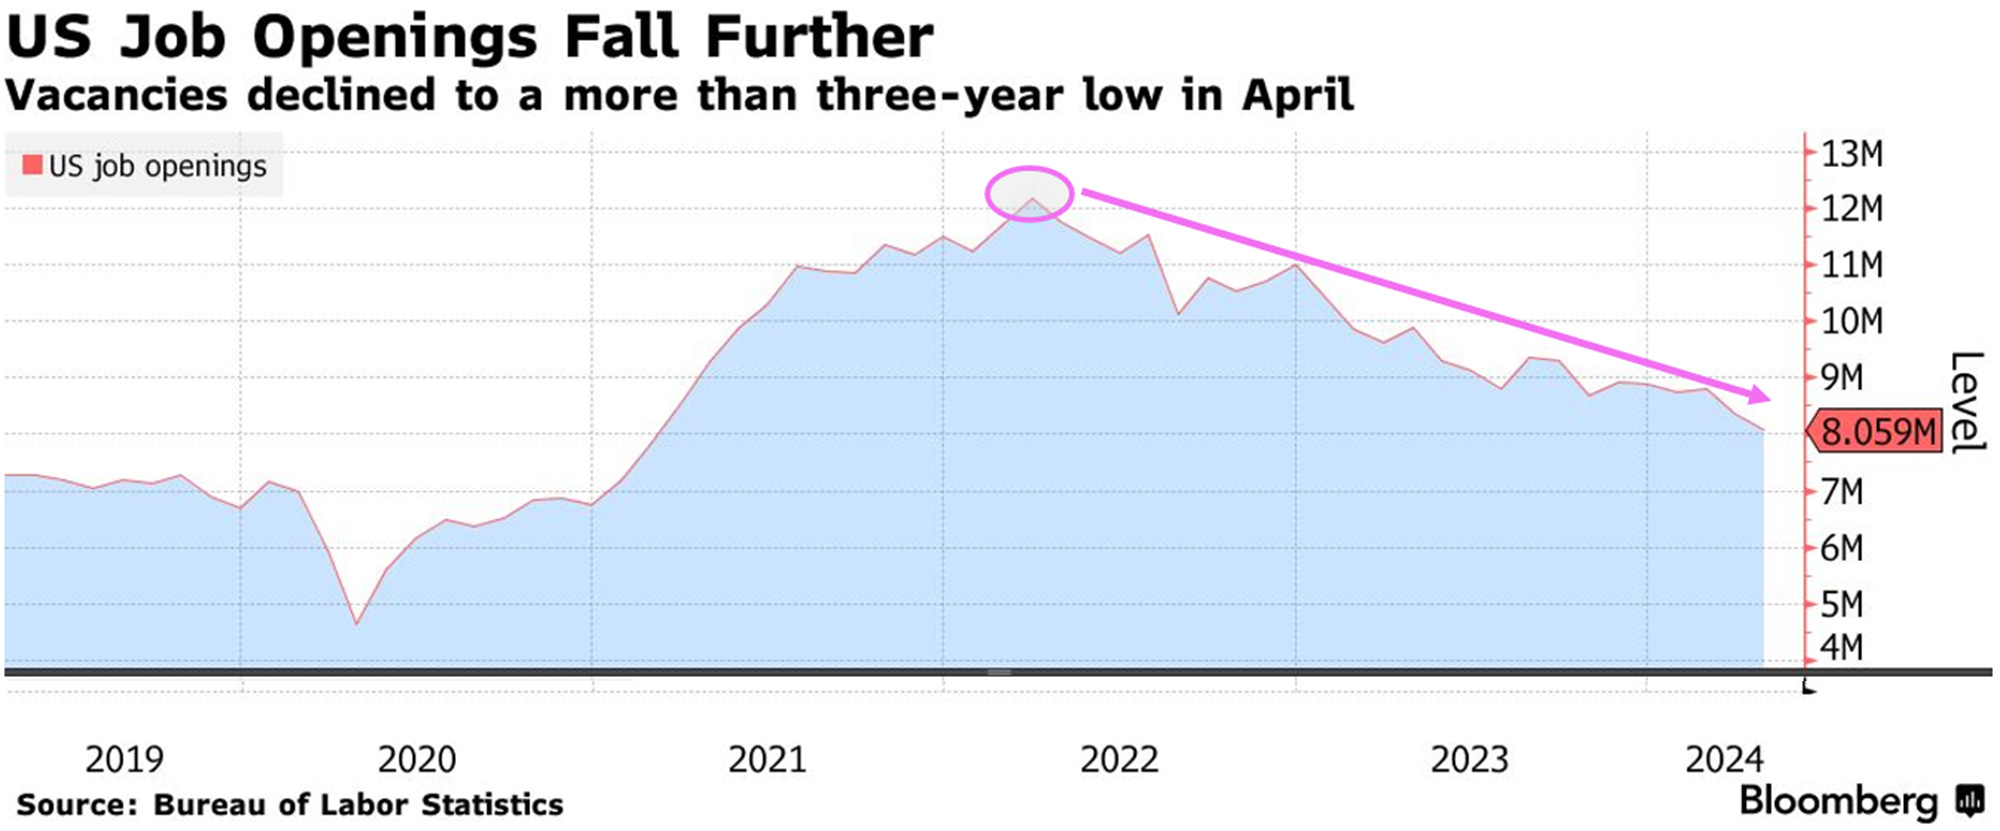 Data as of May 2024
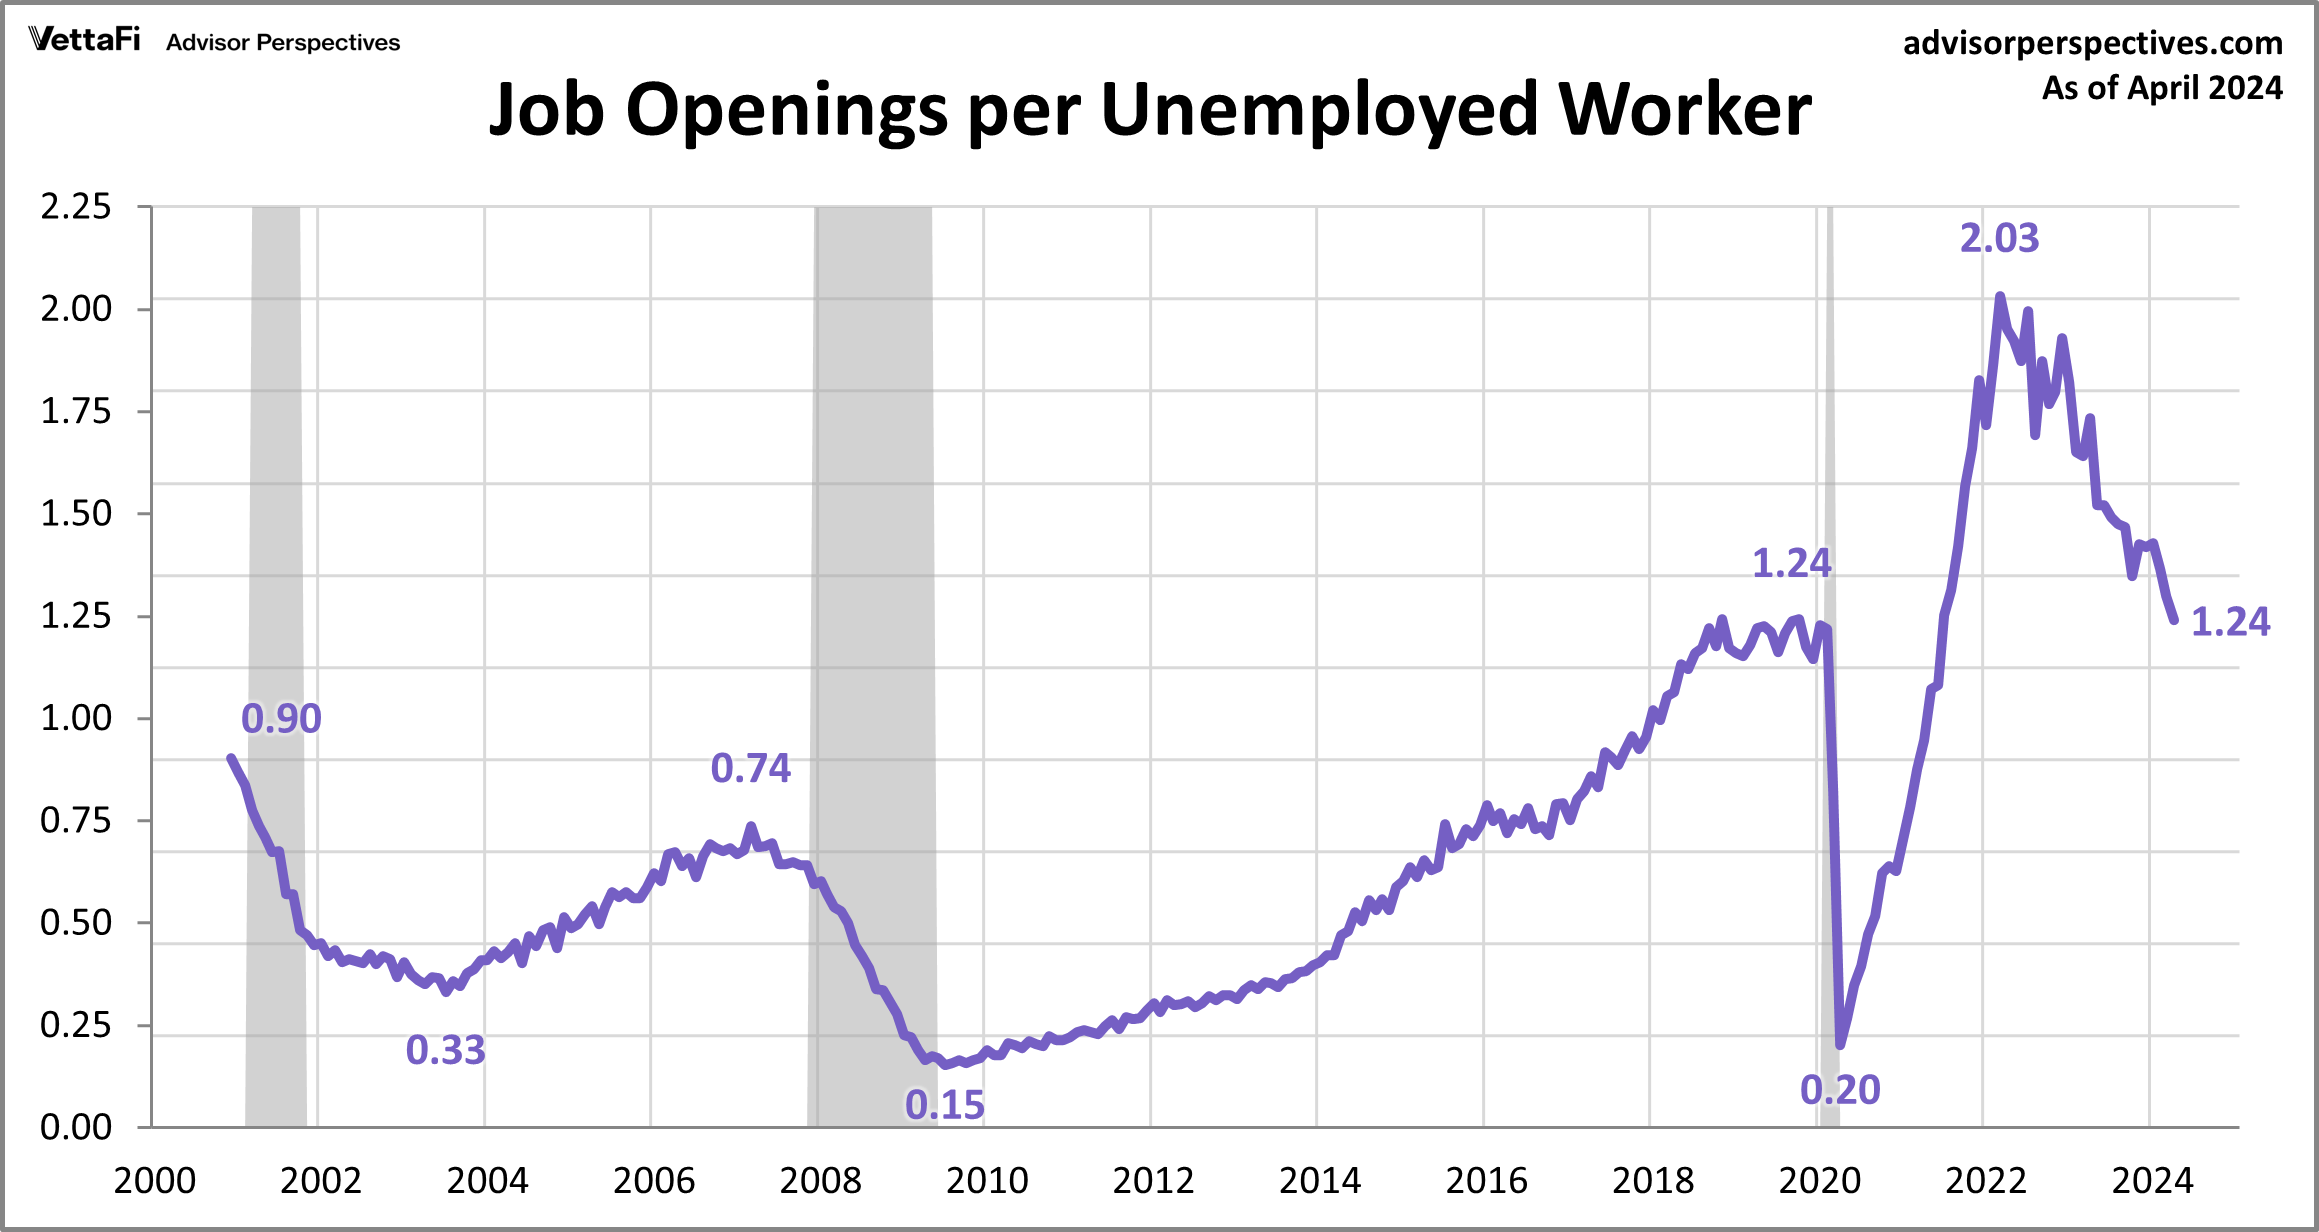
Brad: Another area of divergence is in the contrast between megacap tech stocks and the broader market

Joseph: partly due to the impact of rates on the broader list of companies
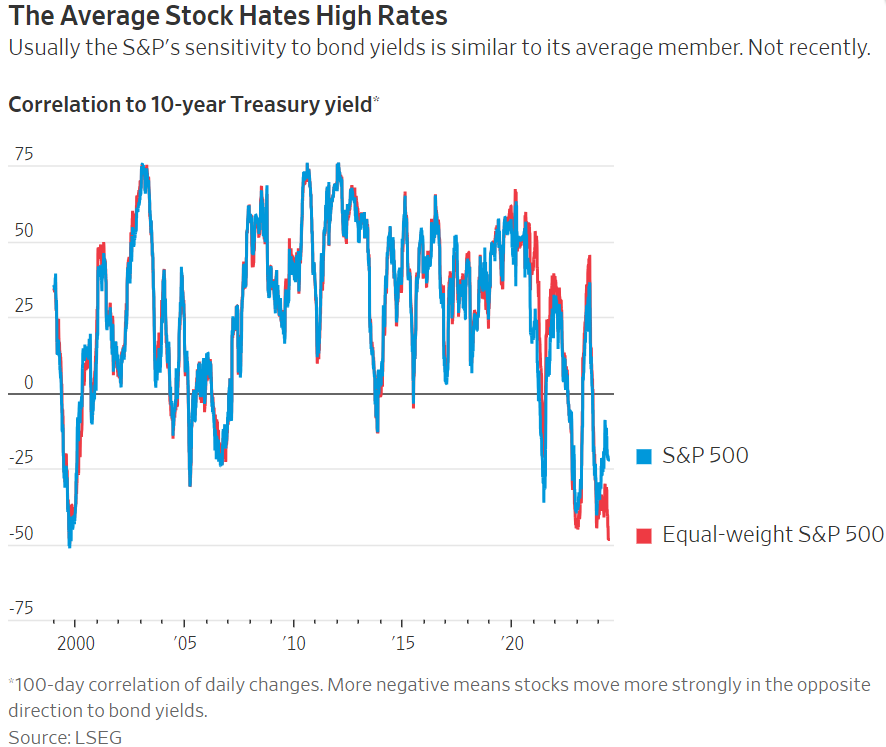 Source: WSJ as of 06.04.2024
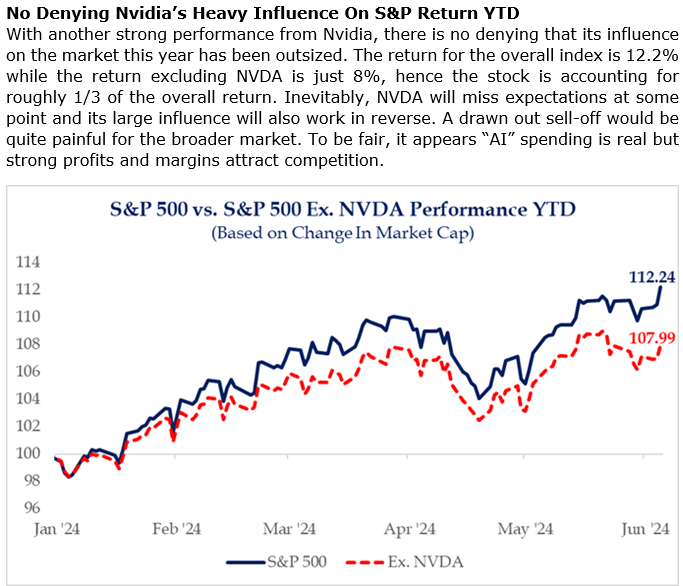
Brad: but also, just the incredible performance of NVDA and its contribution to S&P 500 returns
 Source: Strategas as of 06.04.2024
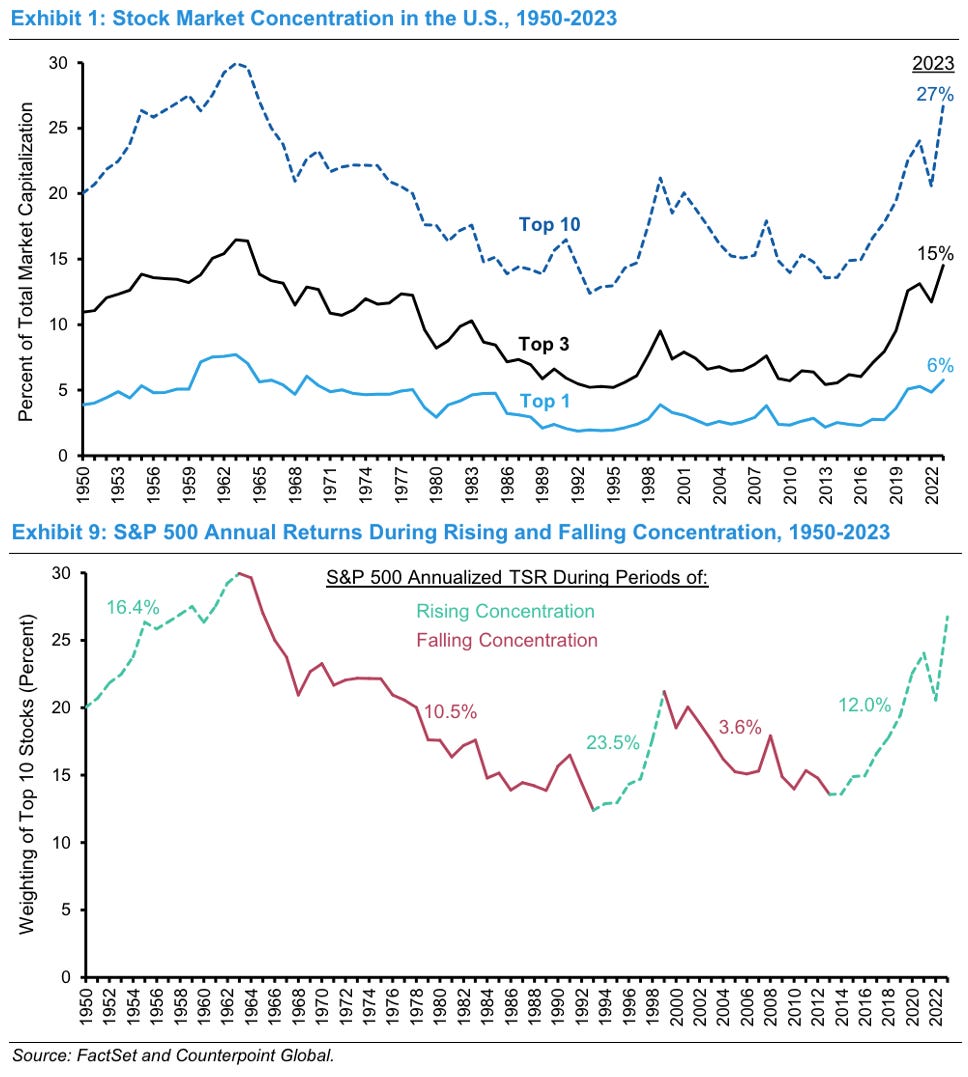
Brett: and while the concentration is approaching extremes, the risk in the past has been when that concentration retreats
 Data as of January 2024
Dave: Most important for stocks is that they grow their earnings, and trends are improving
 Data as of 05.31.2024
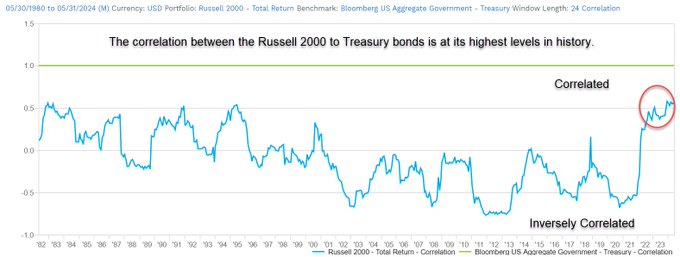
Arch: which can hopefully start to offset the outsized impact rates have had on the broader market
 Source: @matthew_miskin as of 06.03.2024
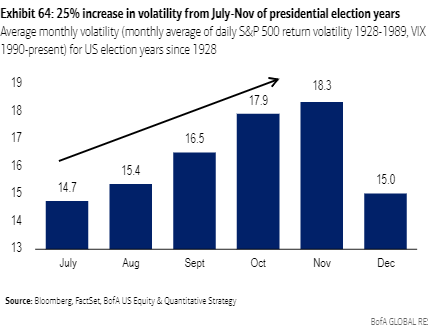
Dave: Presidential election years have generally been solid, but volatility has historically risen as the election approached
 Data as of May 2024
Brad: that said, we’ve just entered the most favorable 3-month window of past election years
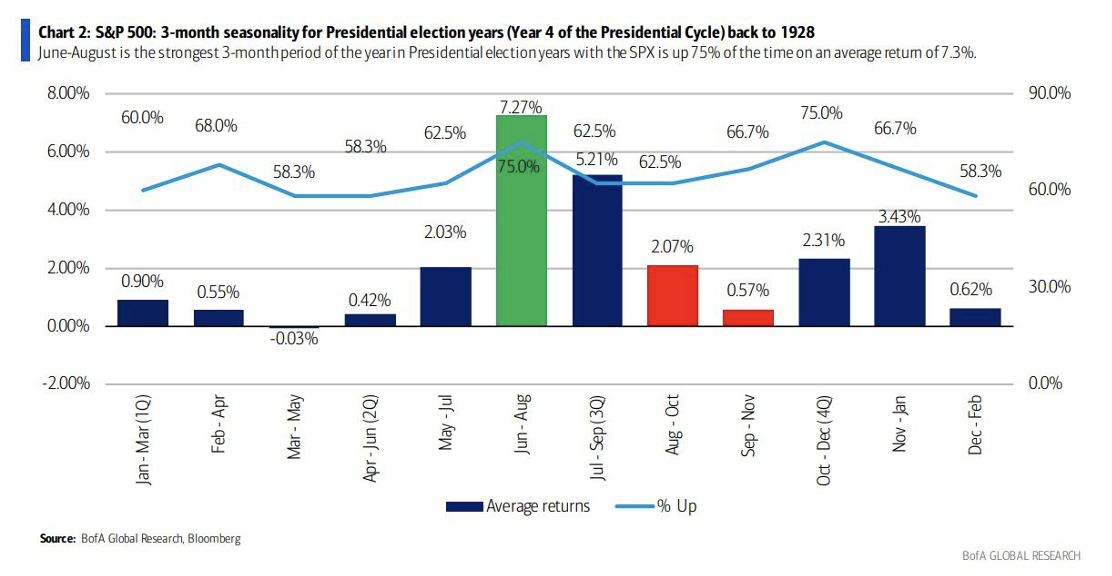 Data as of May 2024
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level or skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2406-11.
The Investment Hub carries the full Aptus research library — manager research, market dashboards, models, and a studio that renders it all on your firm's letterhead.
Sign in Request access