The Market in Pictures, November 10
Our team looks at a lot of research throughout each day. A few charts that caught our eye this week, and the way they fit the unfolding puzzle of evidence:
Brad: Q3 earnings results ran ahead of estimates by a wide margin
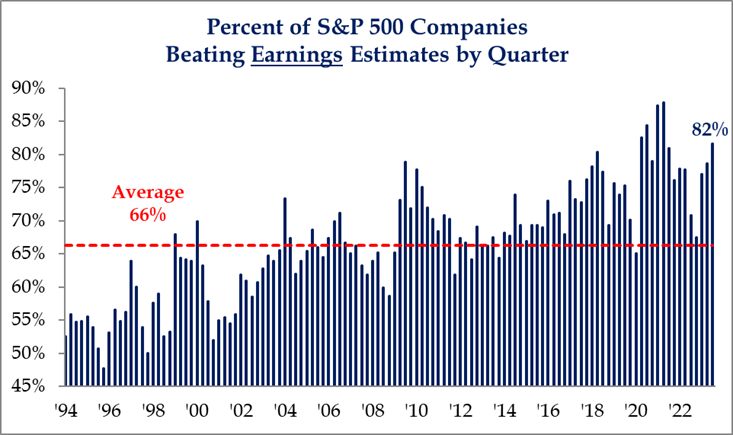 Source: Strategas as of 11.03.2023
Dave: and while the earnings trough seems to be in the rearview mirror
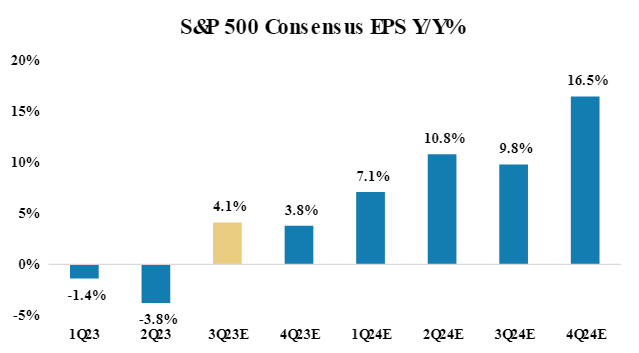
Source: Morgan Stanley as of 11.06.2023
Dave: it’s not exactly resulting in a bump to Q4 estimates and beyond
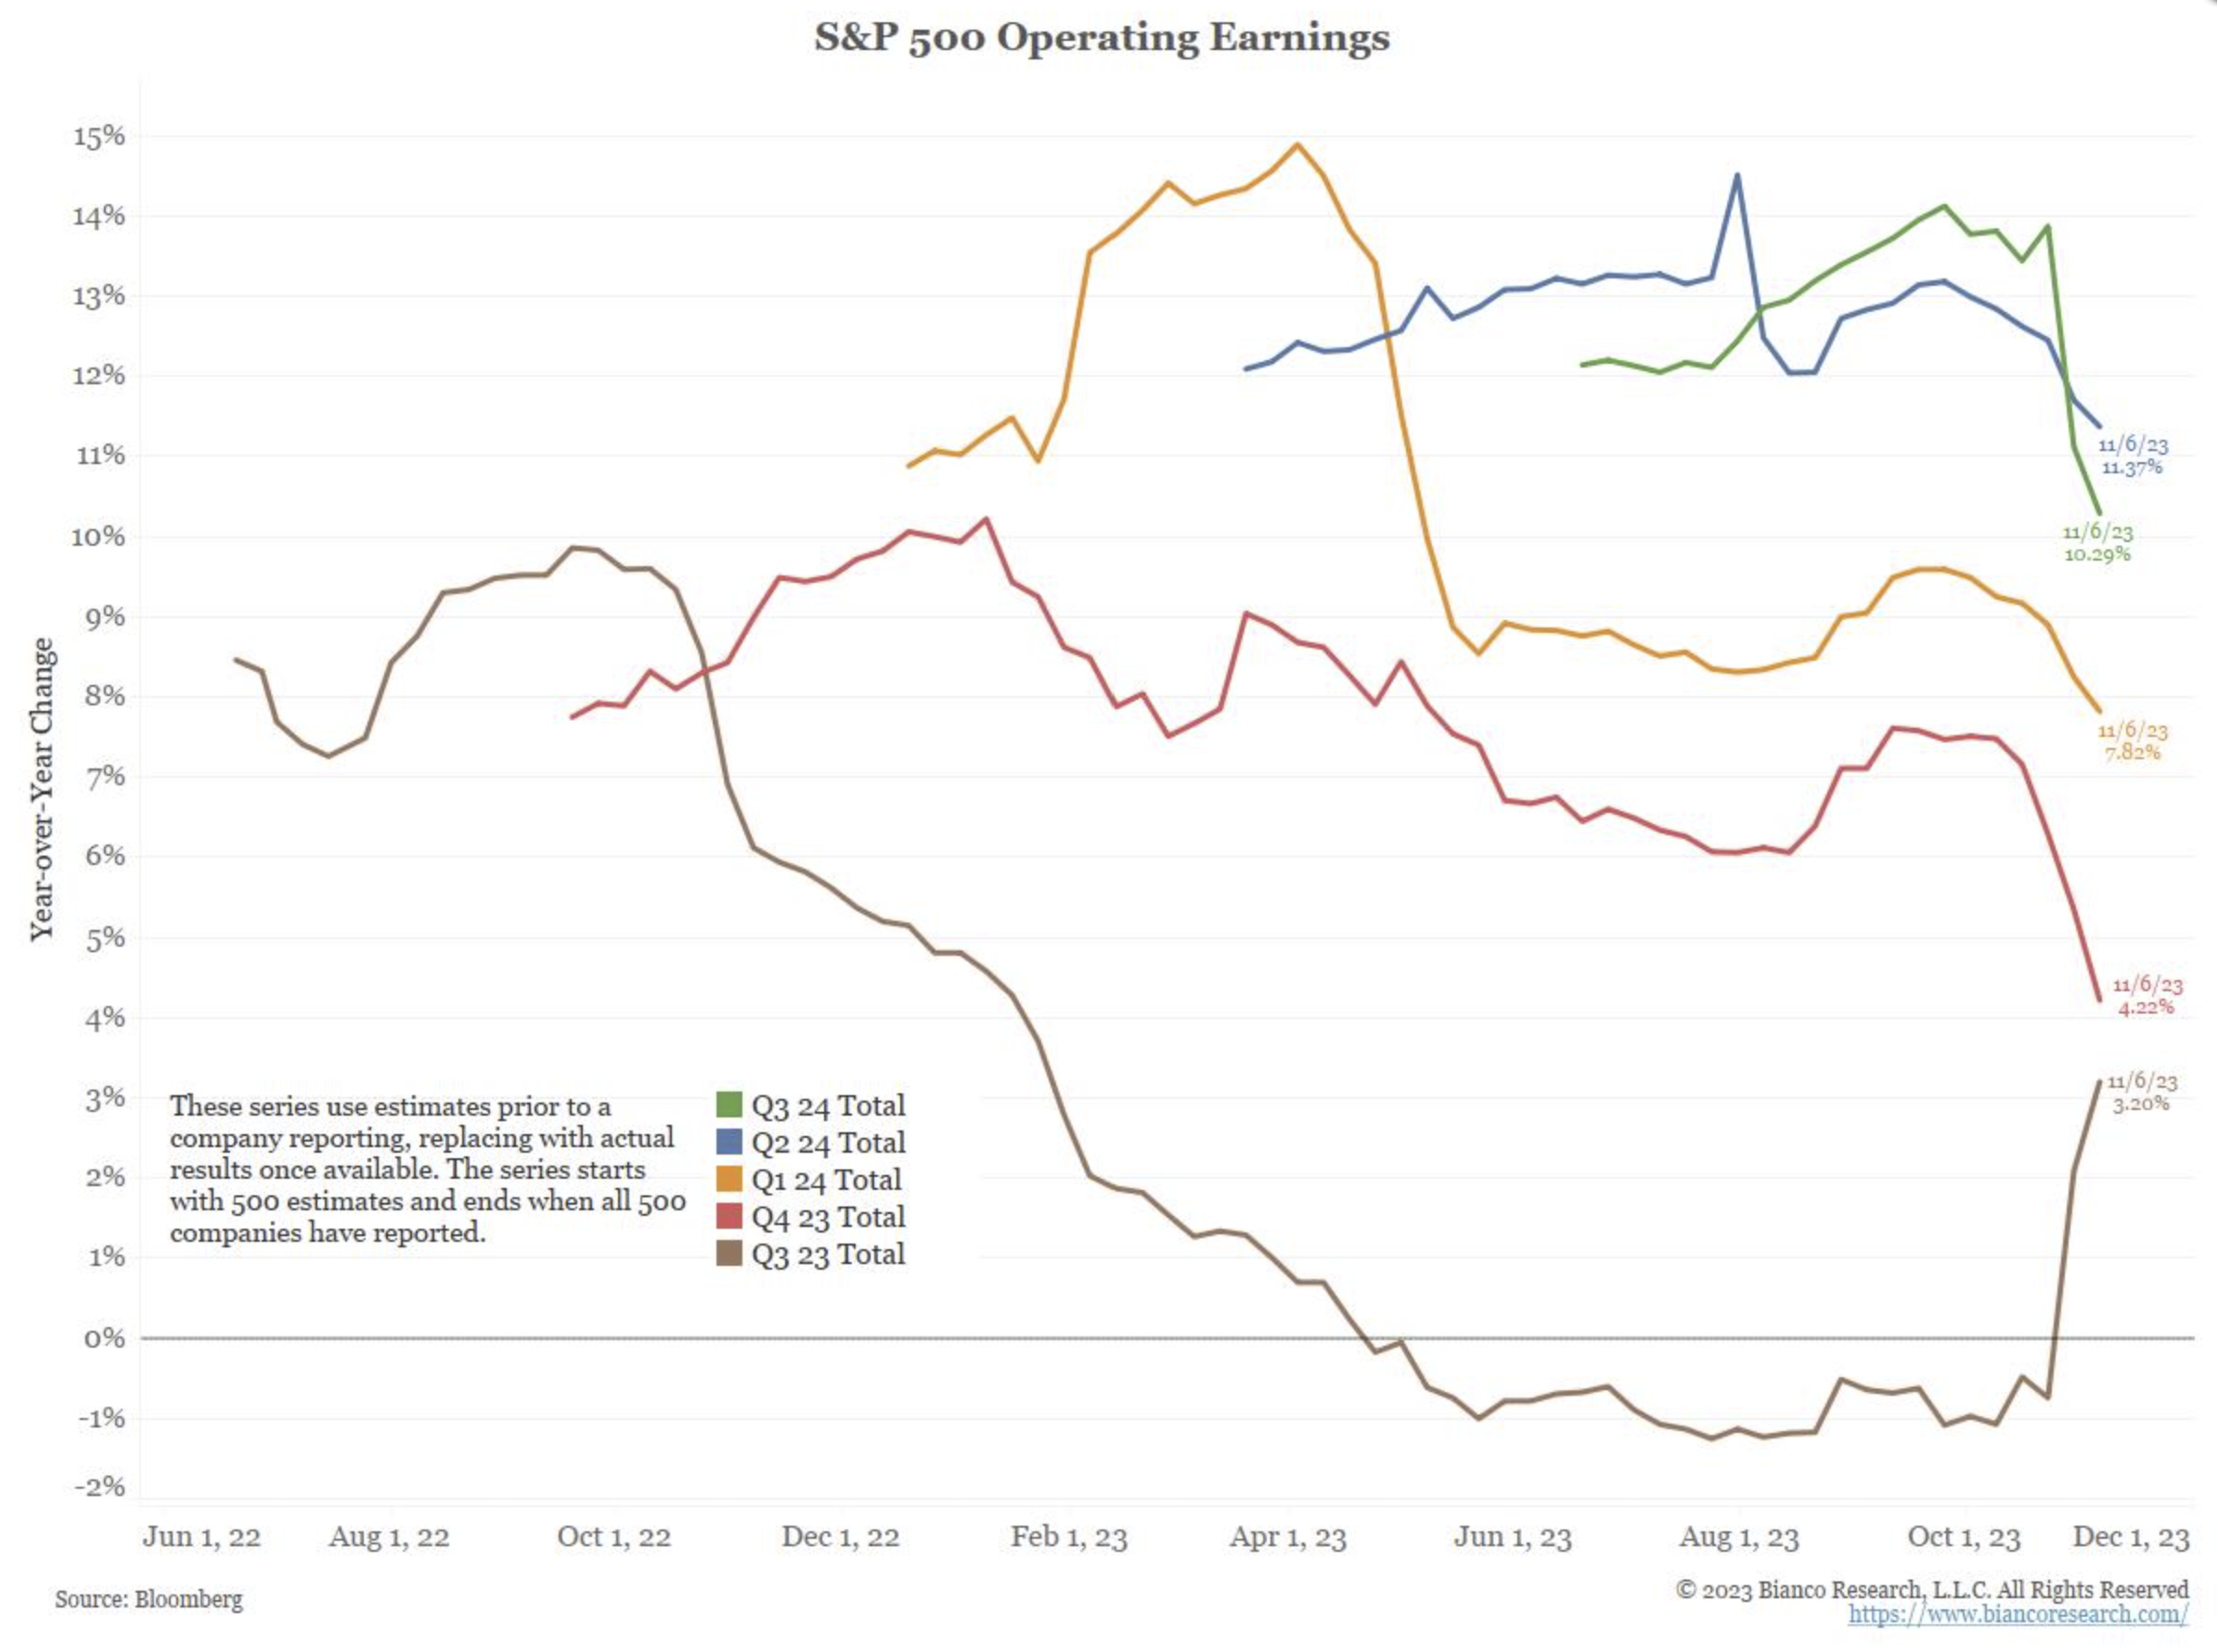 Source: Bianco as of 11.07.2023
Brad: While the Mag 7 is dominating earnings this year
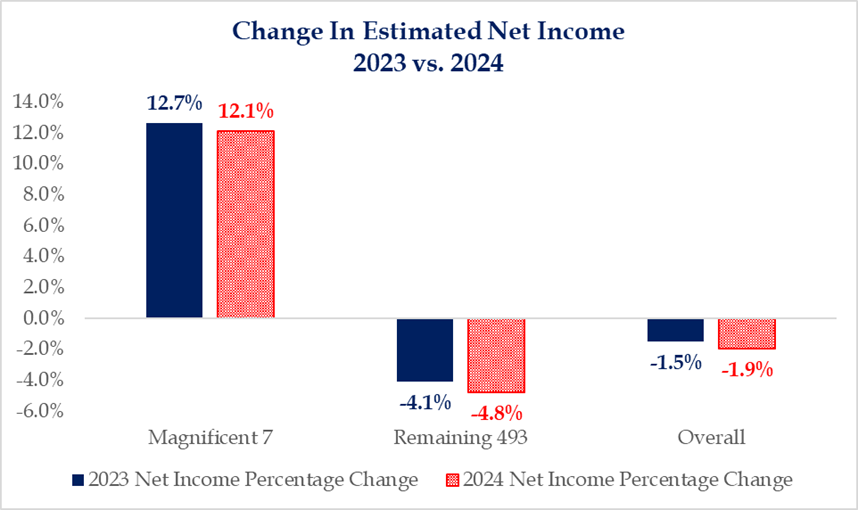 Source: Strategas as of 11.03.2023
Joseph: there’s a story in the past few years about the impact of earnings growth on market leadership
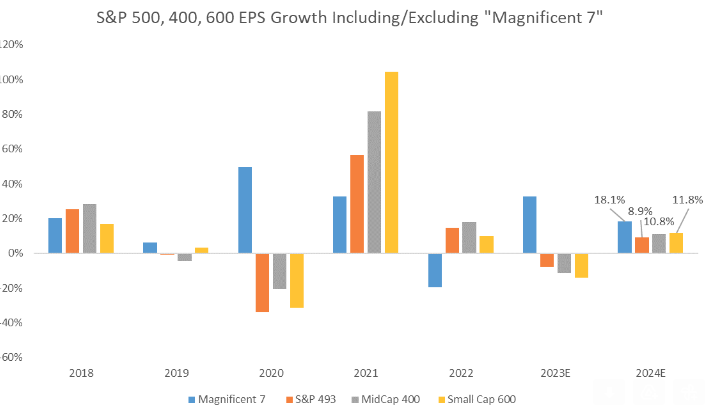 Source: Raymond James as of 11.10.2023
Brett: The Fed Funds rate is above the average corporate bond coupon for the first time in decades
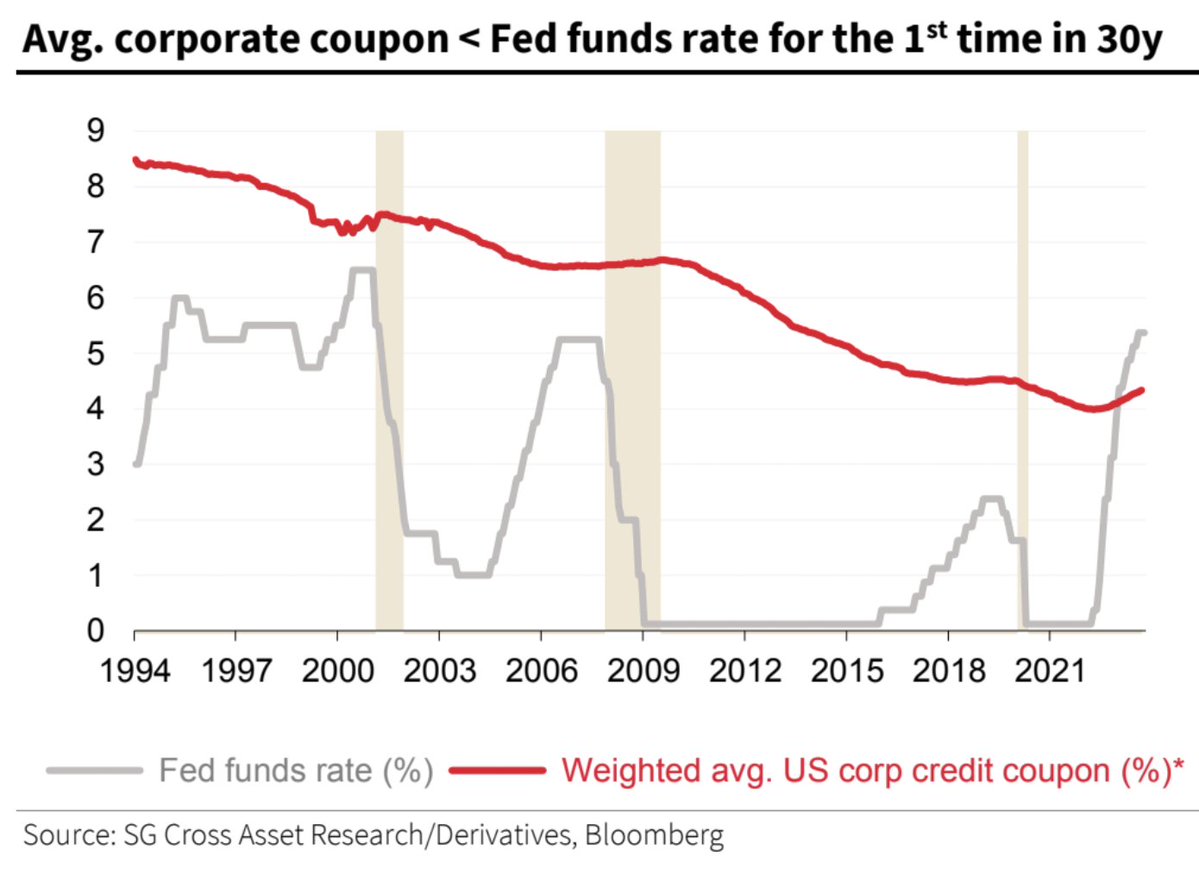 Data as of October 2023
Beckham: as the Fed’s zero-rate policy turned out to be one heckuva tailwind for corporations willing and able to raise debt
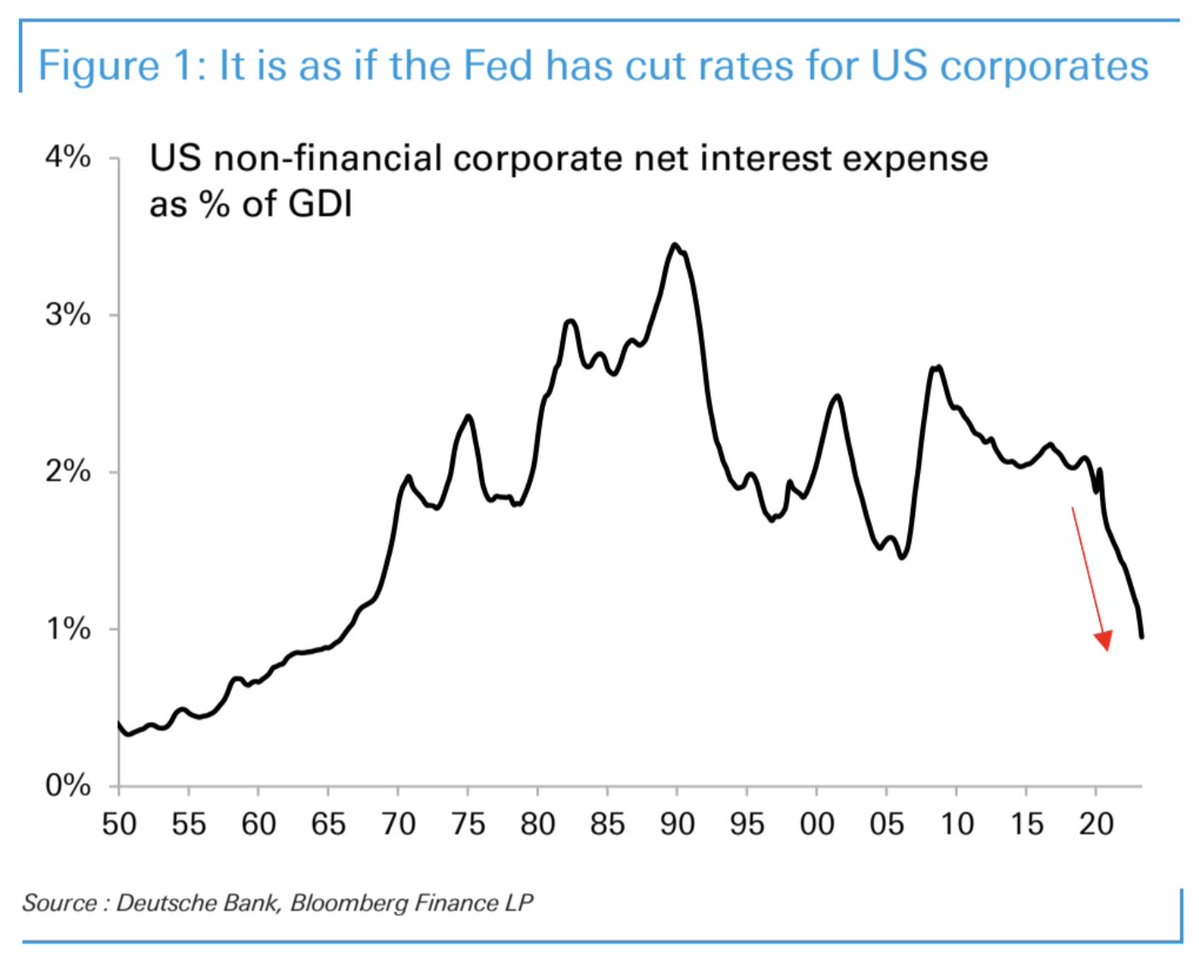 Data as of October 2023
John Luke: The same cannot be said for the US government, as they took on huge debt and relied on short-term maturities
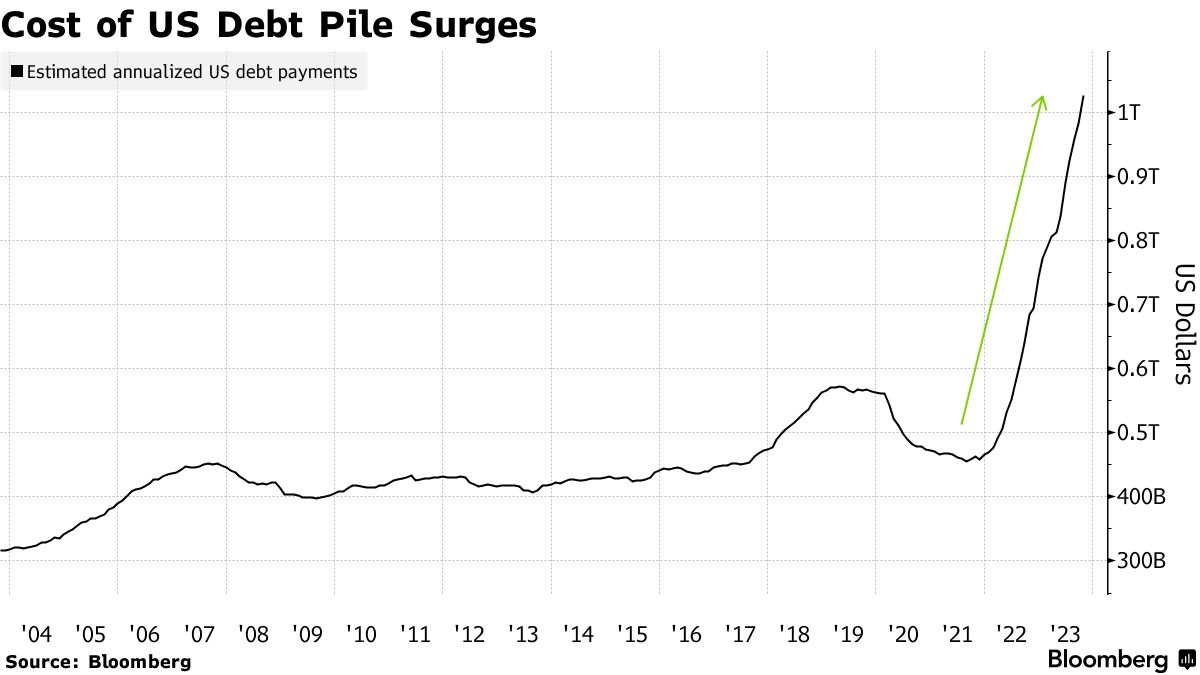 Data as of November 2023
Joseph: Large banks and small banks have taken a much different approach to their business activity since the SVB crisis
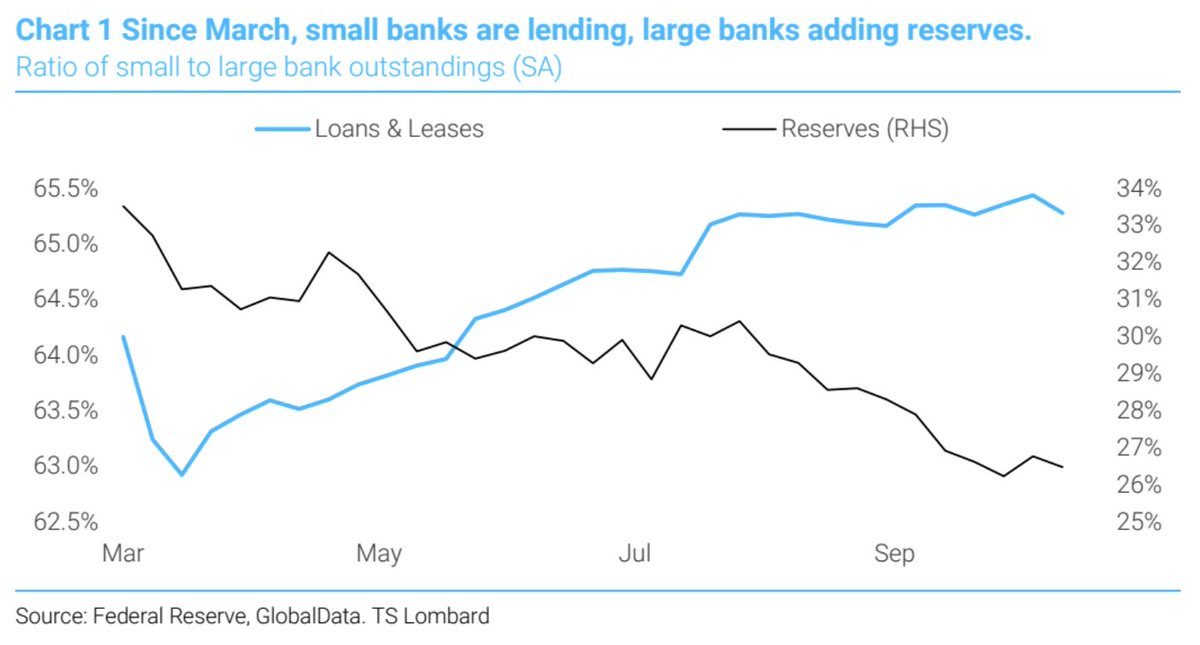 Data as of October 2023
Brett: but the tighter lending standards haven’t flowed through into wider high-yield spreads like they have in the past
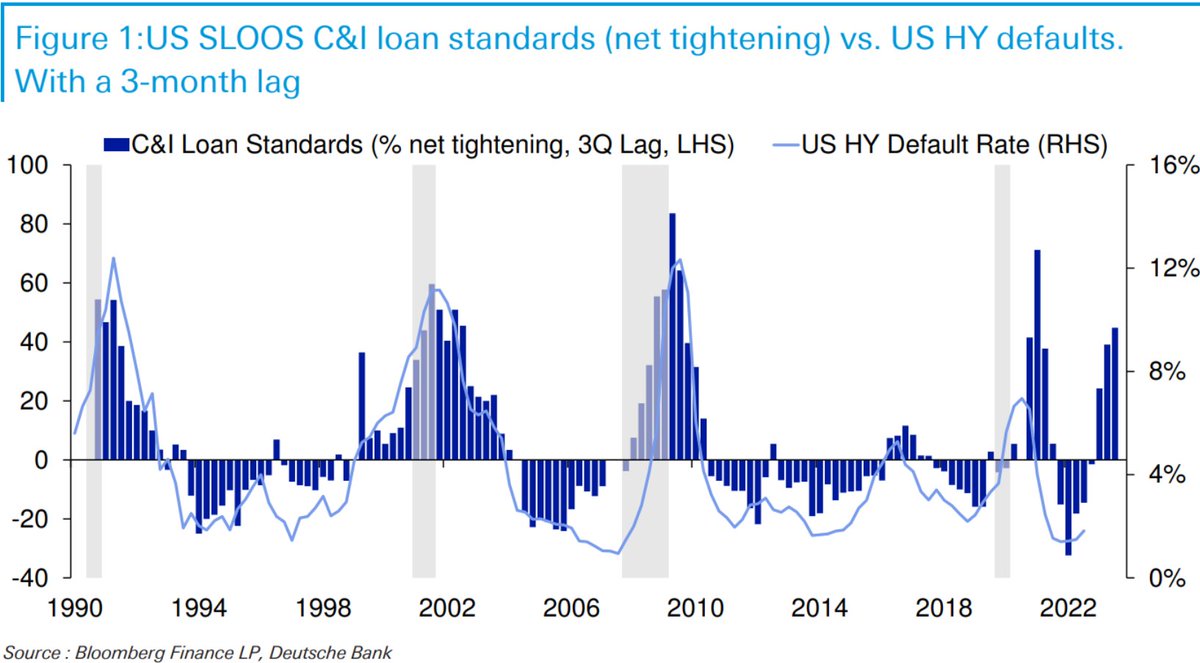 Data as of October 2023
Beckham: Asset flows have sector have been dominated by technology
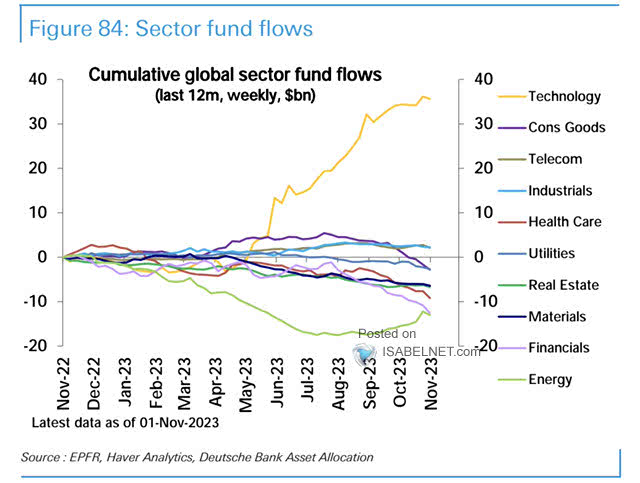 Data as of 11.08.2023
Dave: resulting in a continued valuation split between technology and the rest of the market
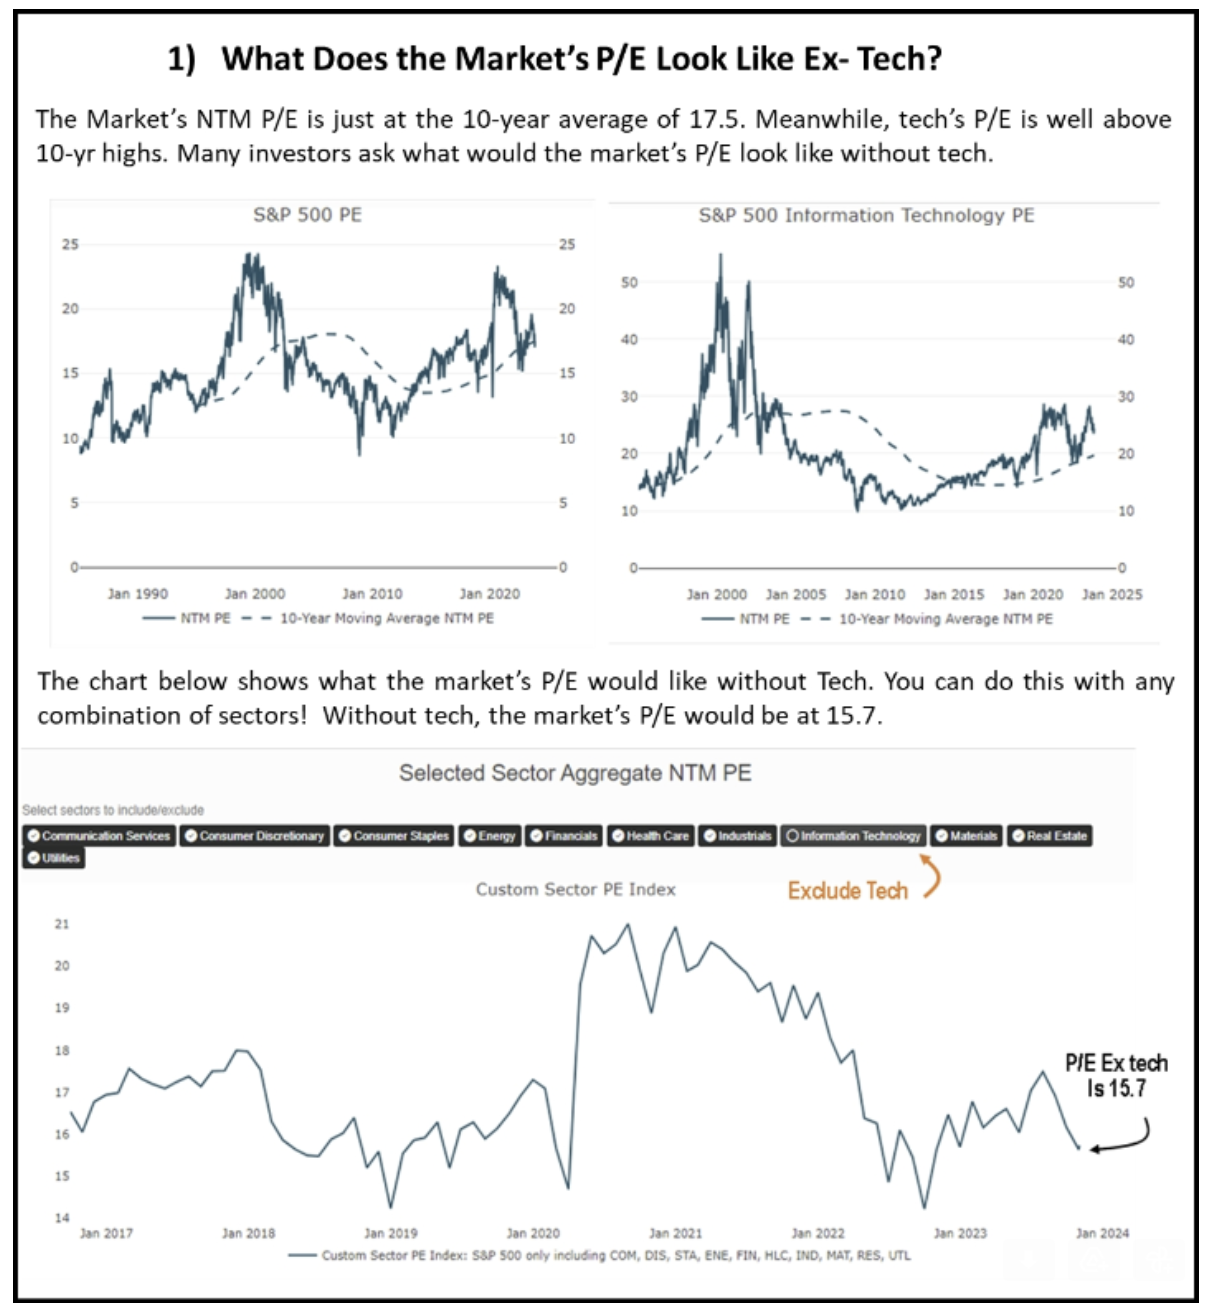 Source: Piper Sandler as of October 2023
John Luke: The cumulative inflation of the past few years is adding up to real longevity risk for those relying on fixed cash flows
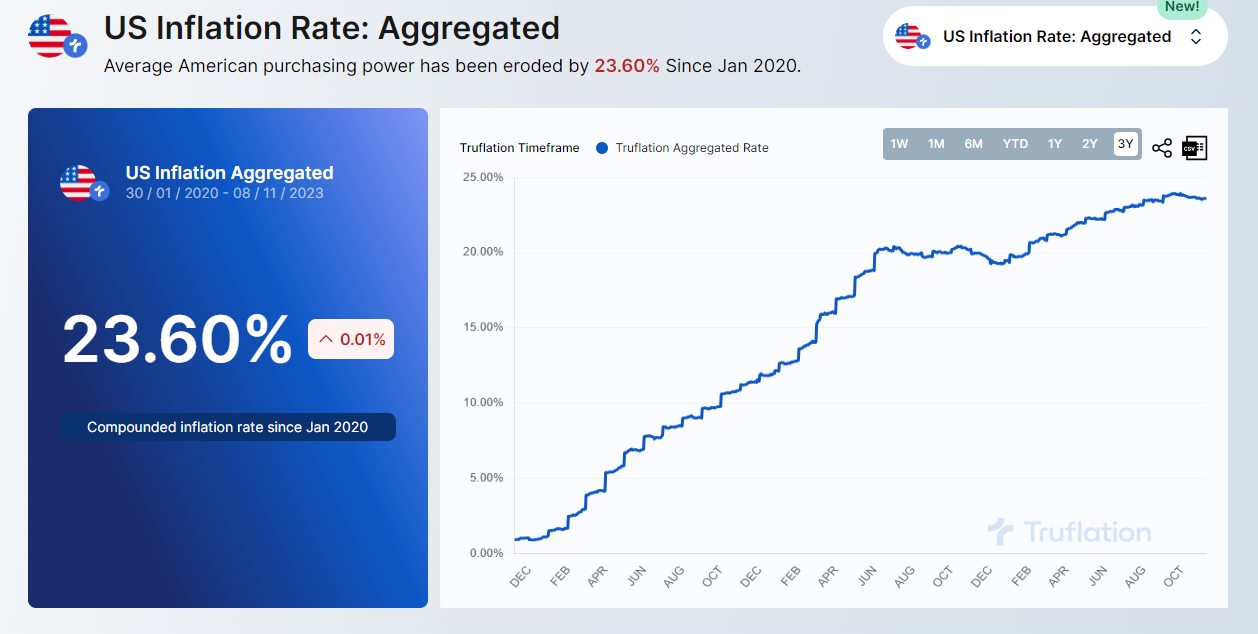 Data as of 11.08.2023
Dave: A reminder that markets have historically made their way through geopolitical events without much impact
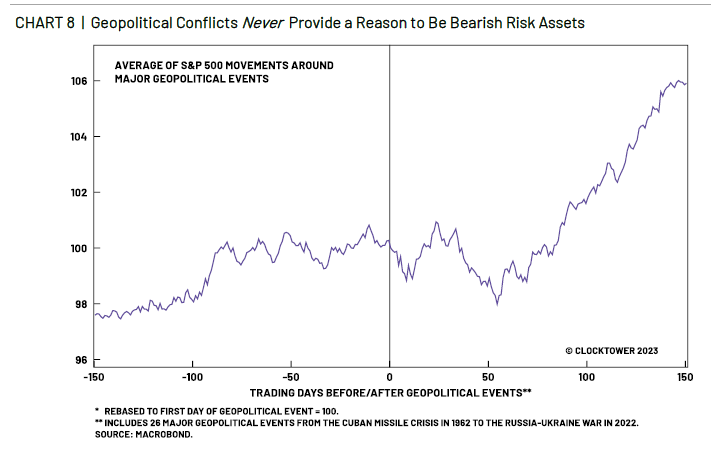 Data as of January 2023
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level or skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2311-12.
The Investment Hub carries the full Aptus research library — manager research, market dashboards, models, and a studio that renders it all on your firm's letterhead.
Sign in Request access