
Every so often, you see a shift in the data that lines up with a transitional moment; this week’s developments could be that moment. We just had three instances that could change the “imminent Fed Hikes” narrative: a) Fed Chair Kevin Warsh’s testimony on Capitol Hill, b) June CPI, and c) June PPI.
All three broke in the same direction; inflation softening, a signpost we aren’t ignoring.
Warsh had a solid week on the Hill. He testified in front of the House Financial Services Committee on Tuesday and the Senate Banking Committee on Wednesday, and he remained consistent with his point of Fed independence and the importance of anchoring inflation. He leaned hard on the dual mandate, called the inflation and employment goals “entirely consistent with each other,” and made sure he reasserted the Fed’s independence frequently. Markets responded favorably to his commentary. Warsh did note that even with the weaker inflation data, the mission is not accomplished.
Consumer Prices
June CPI came in soft across many measures:
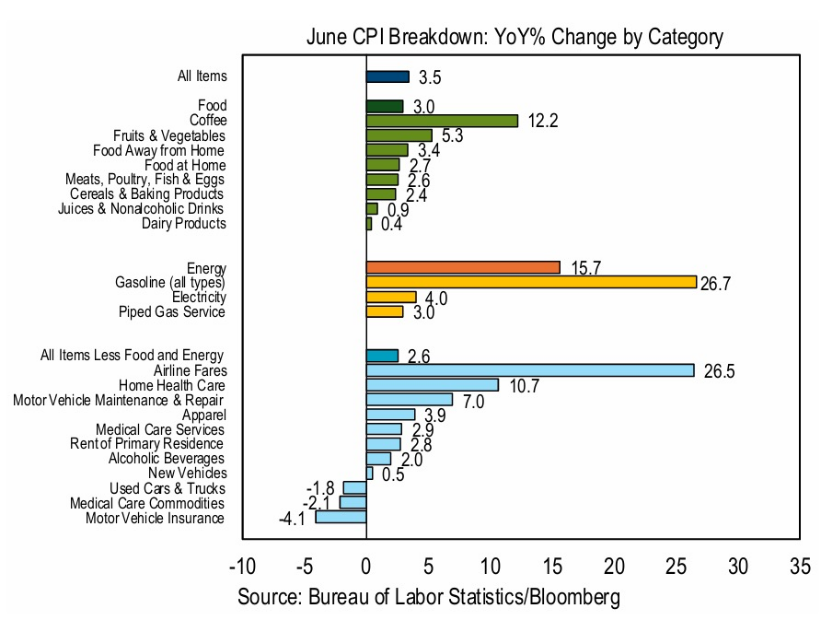 Graphic via Stifel as of 7/14/26
Headline CPI fell -0.4% in June, well below the -0.1% consensus and the largest monthly drop since April 2020. The year-over-year rate dropped from 4.2% to 3.5%, a full three-tenths better than expected. To no one’s surprise, the largest contributor to the decline in headline inflation was energy, as Gasoline prices fell 9.7% month on month.
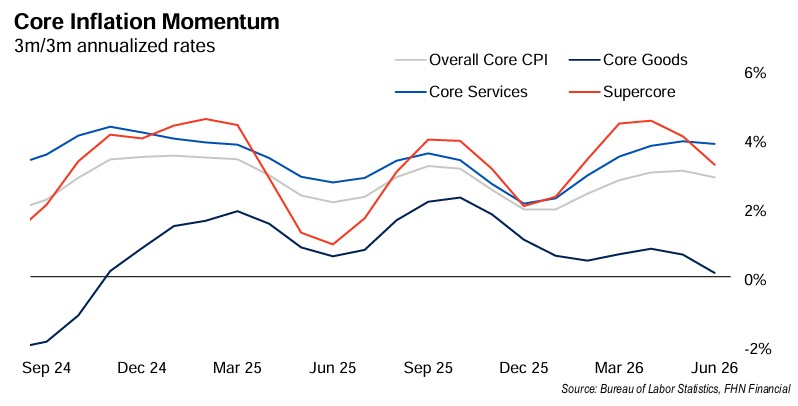 Source: FHN Financial as of 7/15/26
Core CPI was flat in June vs. May (versus 0.2% expected), pulling the year-over-year core rate down from 2.9% to 2.6%. Supercore inflation (core services excluding housing, closely watched by the Fed) fell -0.2%, the largest monthly drop since May 2020. Shelter rose just 0.1%, the smallest increase since January 2021.
Disinflation was remarkably broad in June. Investors should keep in mind the speed at which the March-May oil price spike made its way into virtually all prices, not just energy and food commodities, but also core goods and services.
In June, oil and fuel prices reversed a significant chunk of the previous three months’ increase, filtering across the report. If oil prices remain tame, we expect this reversal to continue.
Producer Prices
June PPI reiterated the softer inflation print from the day before. Producer prices fell -0.3% in June against a flat (0.0%) consensus, and the year-over-year rate dropped from 6.5% to 5.5%, the smallest annual increase since March. Core PPI rose just 0.2%, a tenth below expectations. Energy led the move, down -6.4% on the month, the largest drop since December 2022.
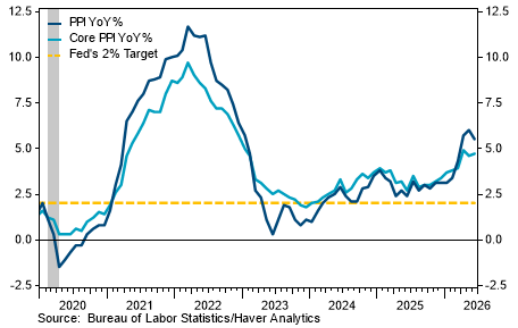 Source: Stifel as of 7/15/26
Goods costs dropped 1.4% in June, marking the largest monthly drop since July 2022. On the other hand, services costs rose 0.2% following a 0.1% decrease the month prior, as transportation and warehousing costs declined 0.1%, while trade costs rose 0.4% at the end of the second quarter.
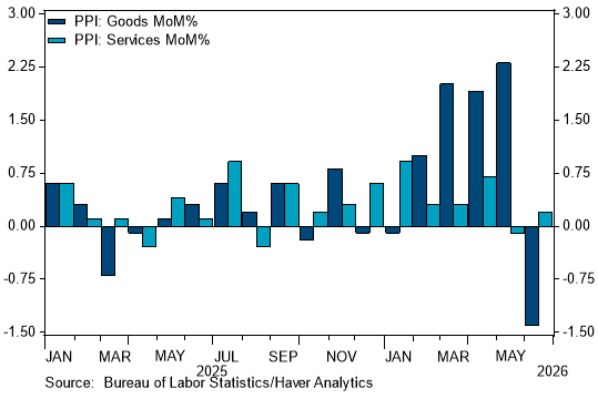 Source: Stifel as of 7/15/26
Final Thoughts
It looked like inflation may have peaked in May. The Fed’s ability to “wait and see” depends on long-run inflation expectations staying anchored (looks okay for now, see below). The more price increases we see in a row, the more the inflation anchor is threatened. So, while June provided some relief, oil prices are worth watching in July as the ceasefire in Iran has been broken.
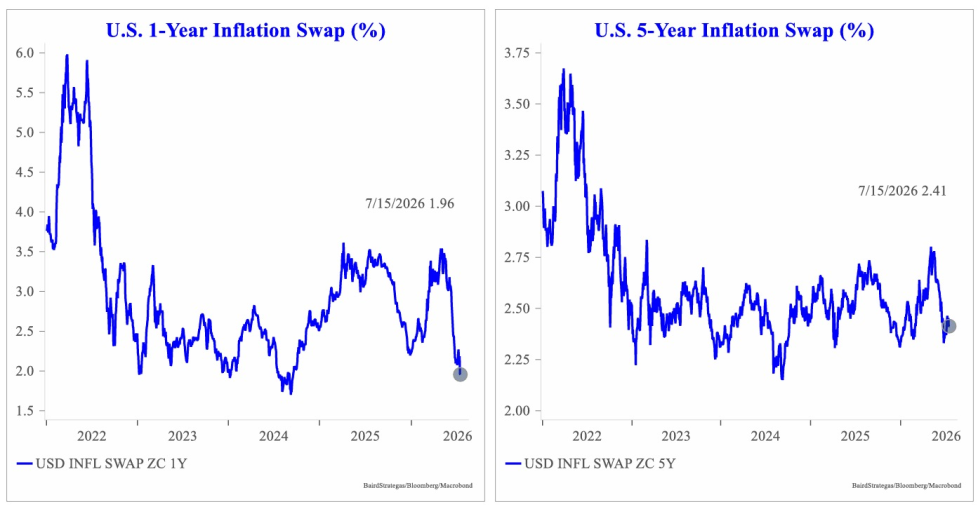 Source: Strategas as of 7/15/26
All said and done, the past few months have served as a reminder why the Fed looks through one-time oil shocks; it typically doesn’t last forever and is often self-correcting.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward looking statements cannot be guaranteed.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2607-17.