
Our team looks at a lot of research throughout the day. Here are a handful of charts we think are good summations of the current market, from strong corporate profits and resilient consumers to an AI-driven investment boom, healthy credit markets, persistent weakness in housing, and a bond market facing a very different backdrop than it has in the past. Have a great weekend!”
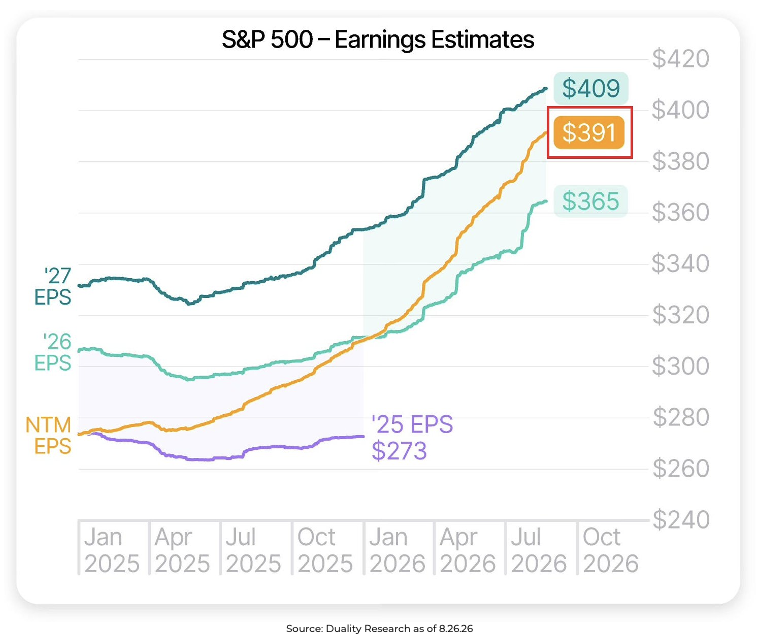
Beckham: Second quarter earnings were strong, but third quarter estimates at the start of earnings season have barely moved. The 3Q number sits at $89.49 against $88.64 when reporting season began.
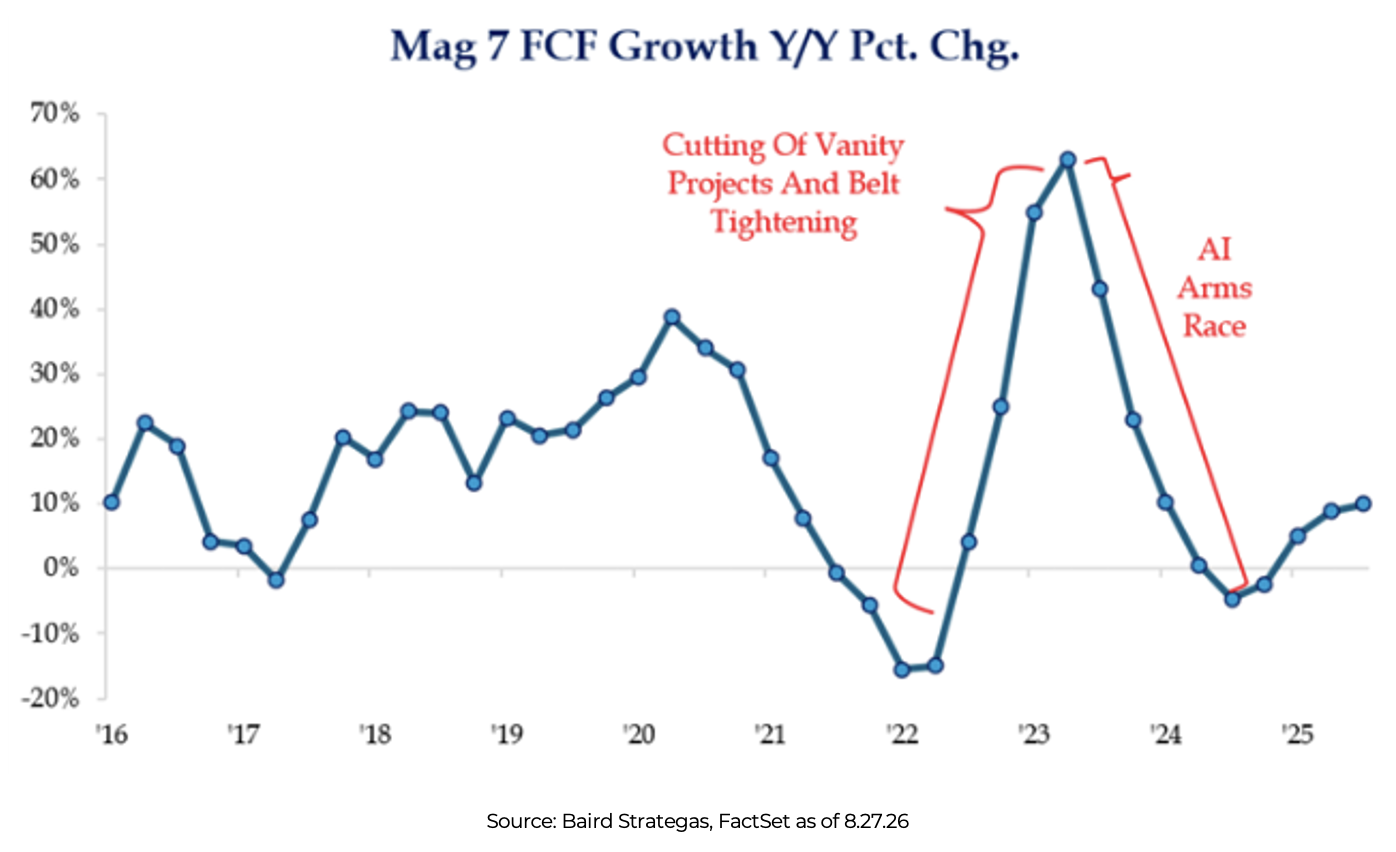
Brad: Meanwhile, the AI arms race is weighing on free cash flow. Mag 7 free cash flow growth peaked above 60% in 2023 before turning negative. The positive view is that despite all the capital investment, free cash flows have once again turned positive back to ~10%.
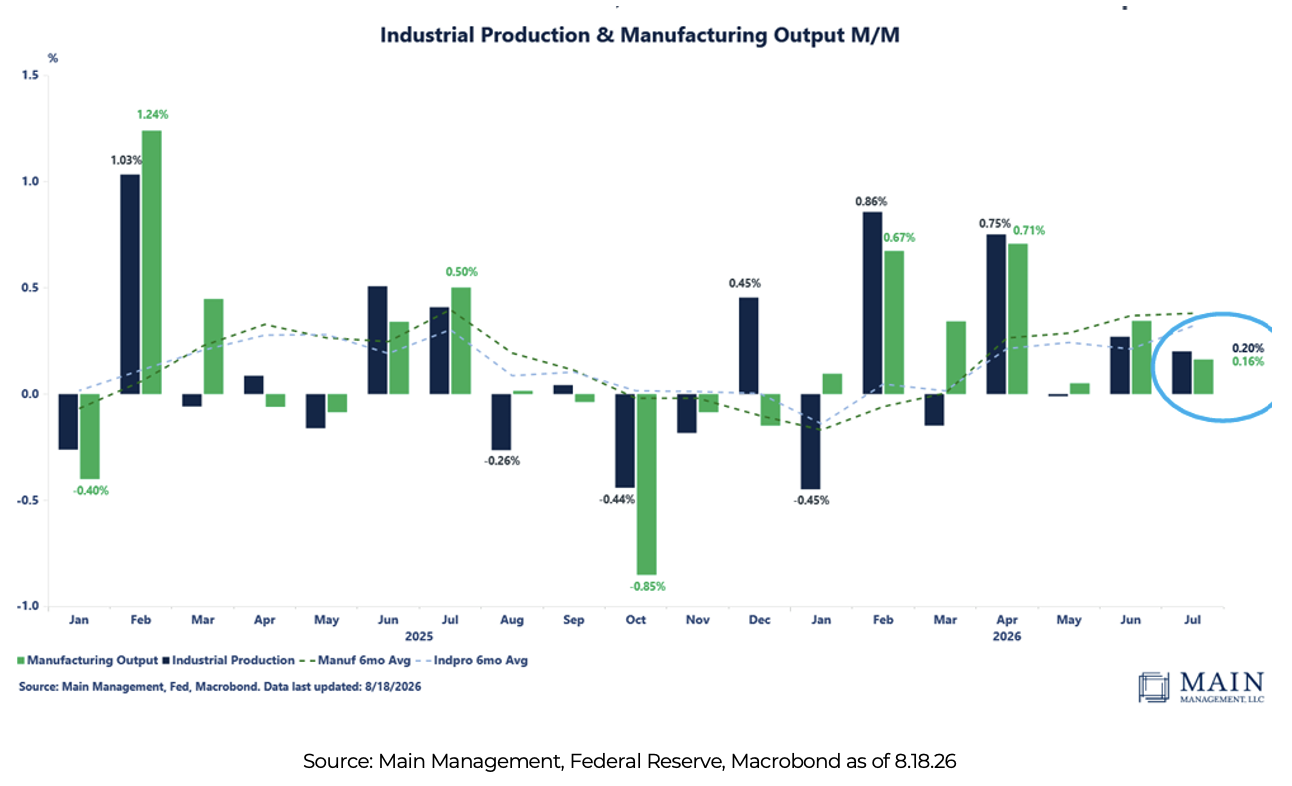
Dave: That spending is showing up in the real economy with manufacturing output having now risen six months in a row, which is the longest streak since 2002.
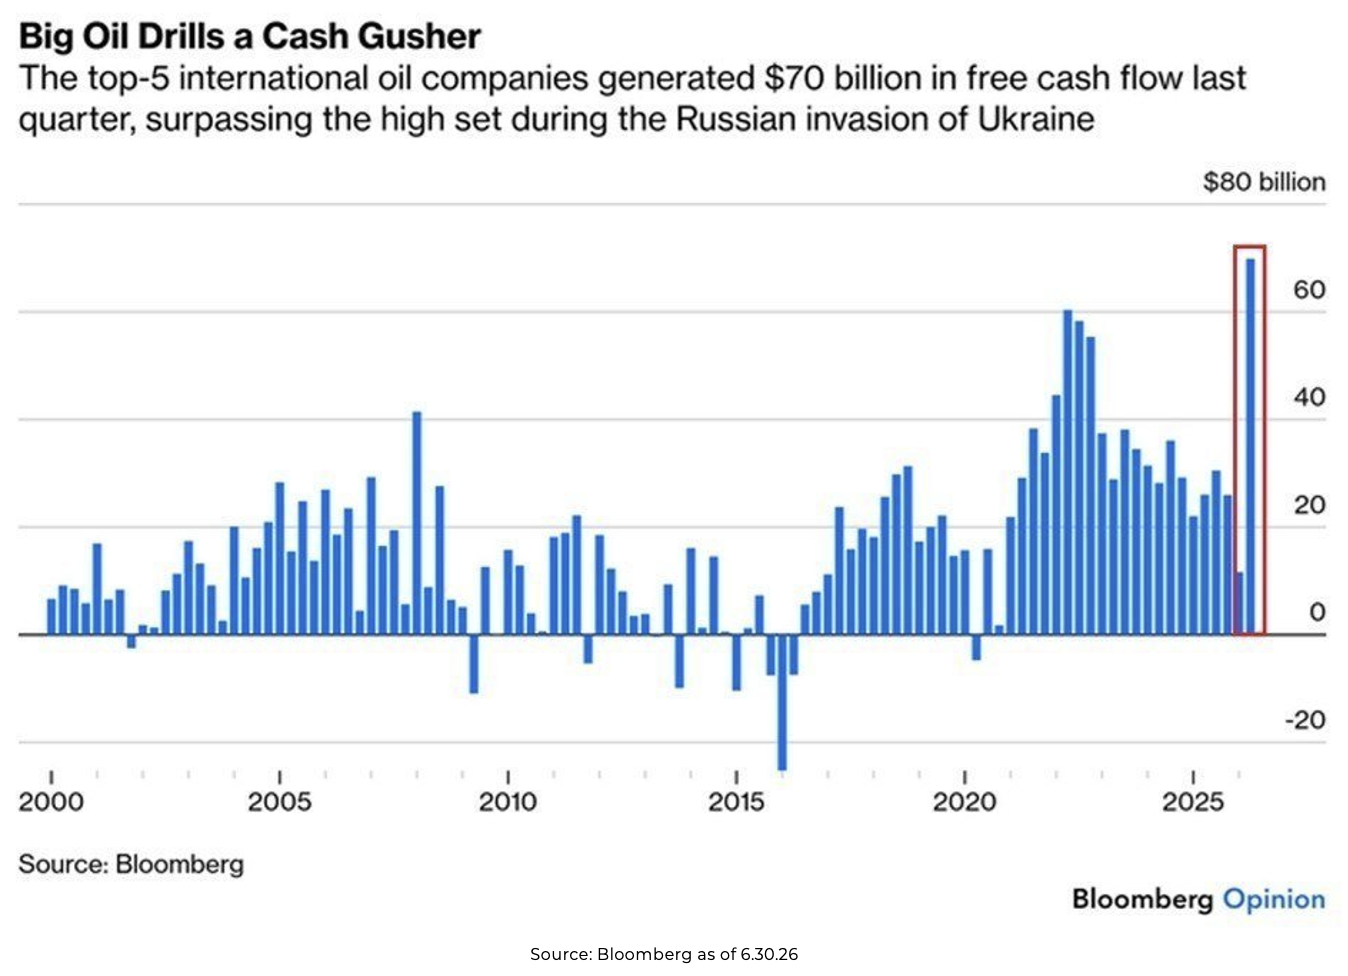
Mike: Meanwhile, the companies powering the manufacturing boom are printing cash. The top five international oil majors generated $70 billion of free cash flow last quarter, which tops the peak set during the invasion of Ukraine.
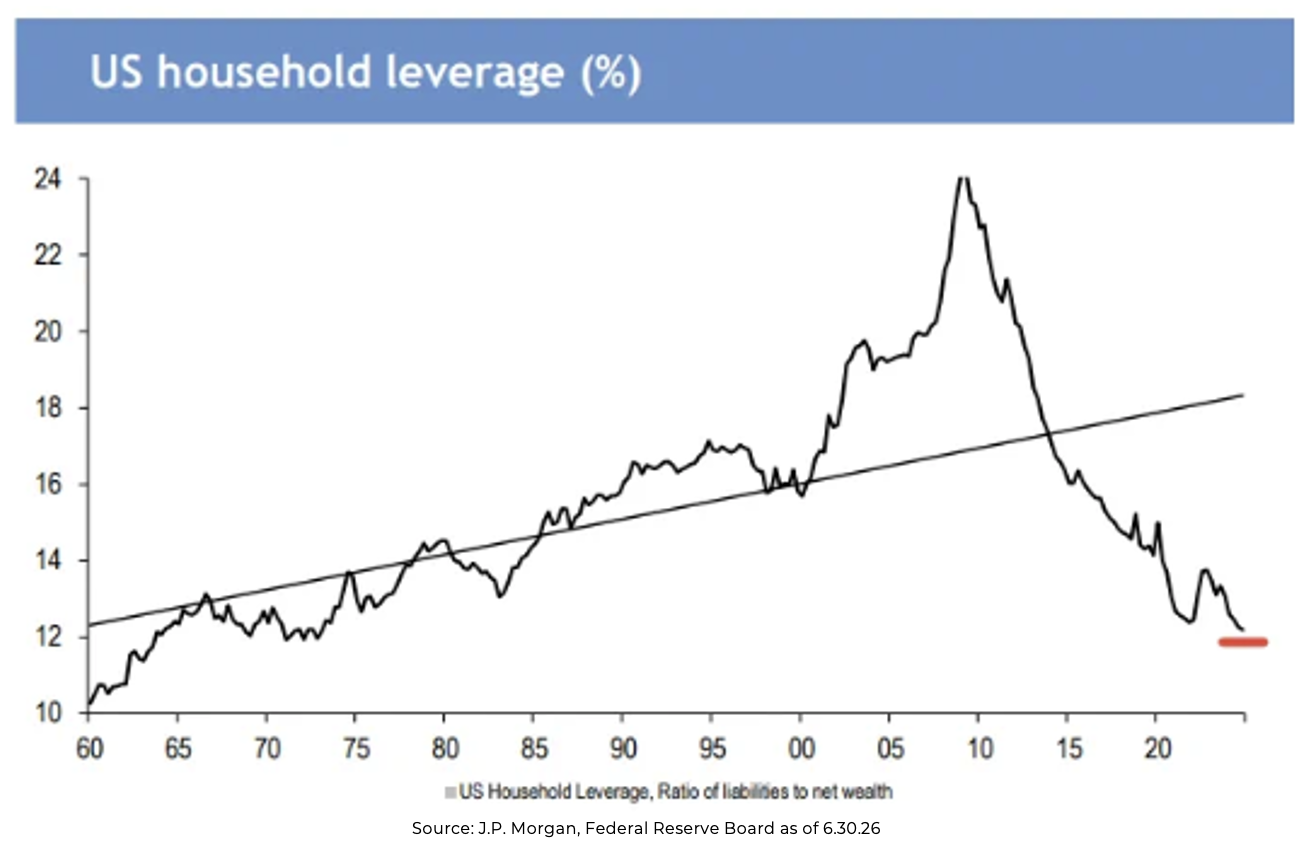
John Luke: The consumer is in no danger of breaking either. Household liabilities are down near 12% of net wealth and sit well below the six-decade trend.
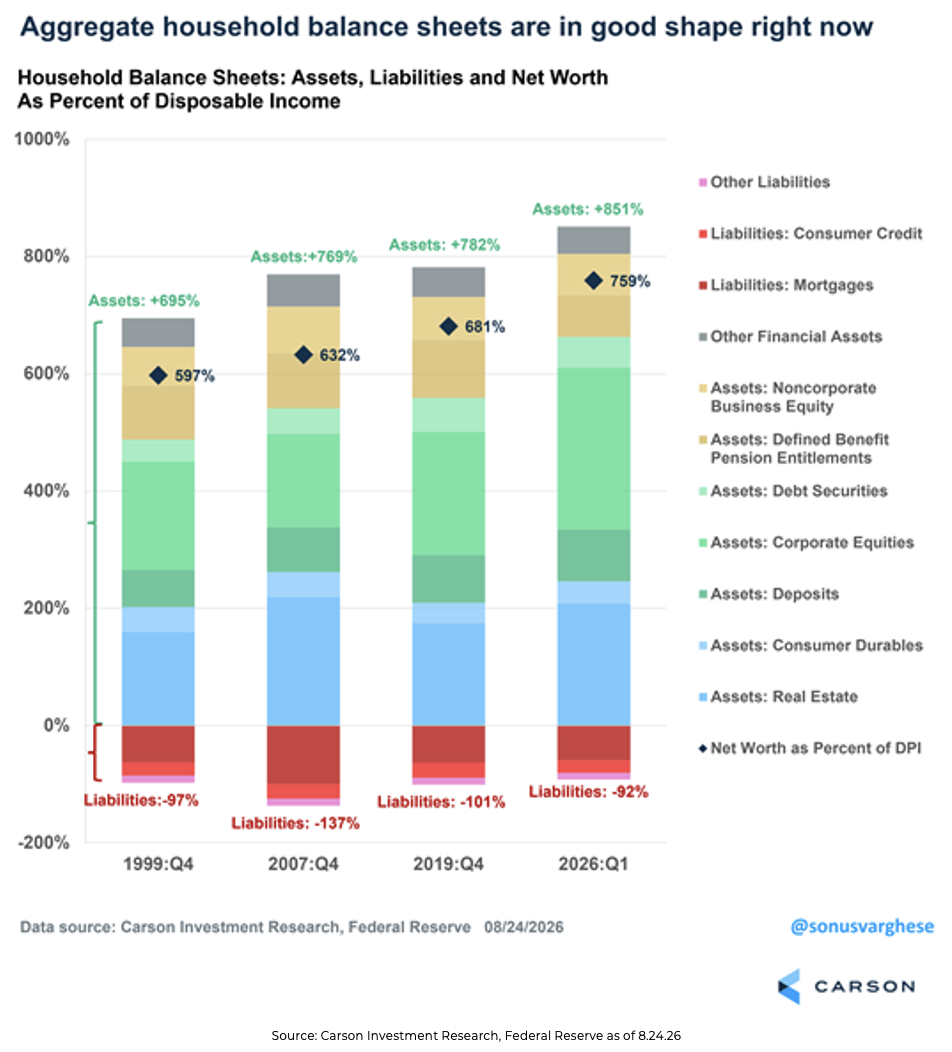
John Fox: That coincides with the strongest household balance sheet in the series. Net worth is 759% of disposable income against 681% before COVID.
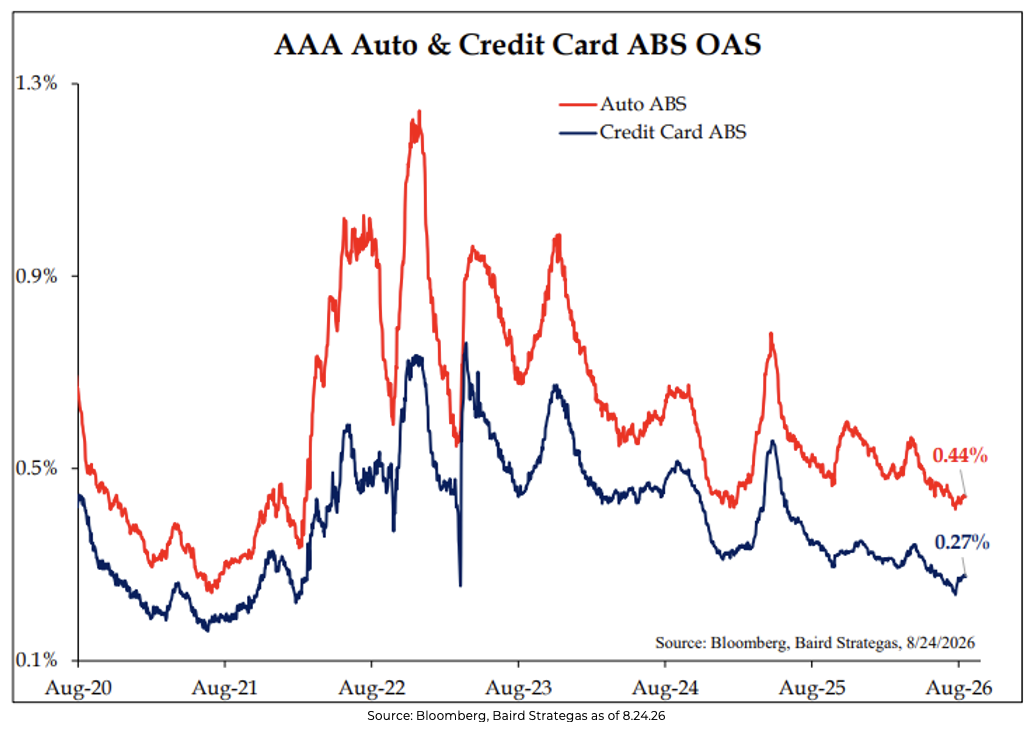
JG: Lenders would agree. AAA auto ABS spreads sit at 0.44% and credit card ABS at 0.27%, which is materially lower than levels that flagged trouble in 2022.
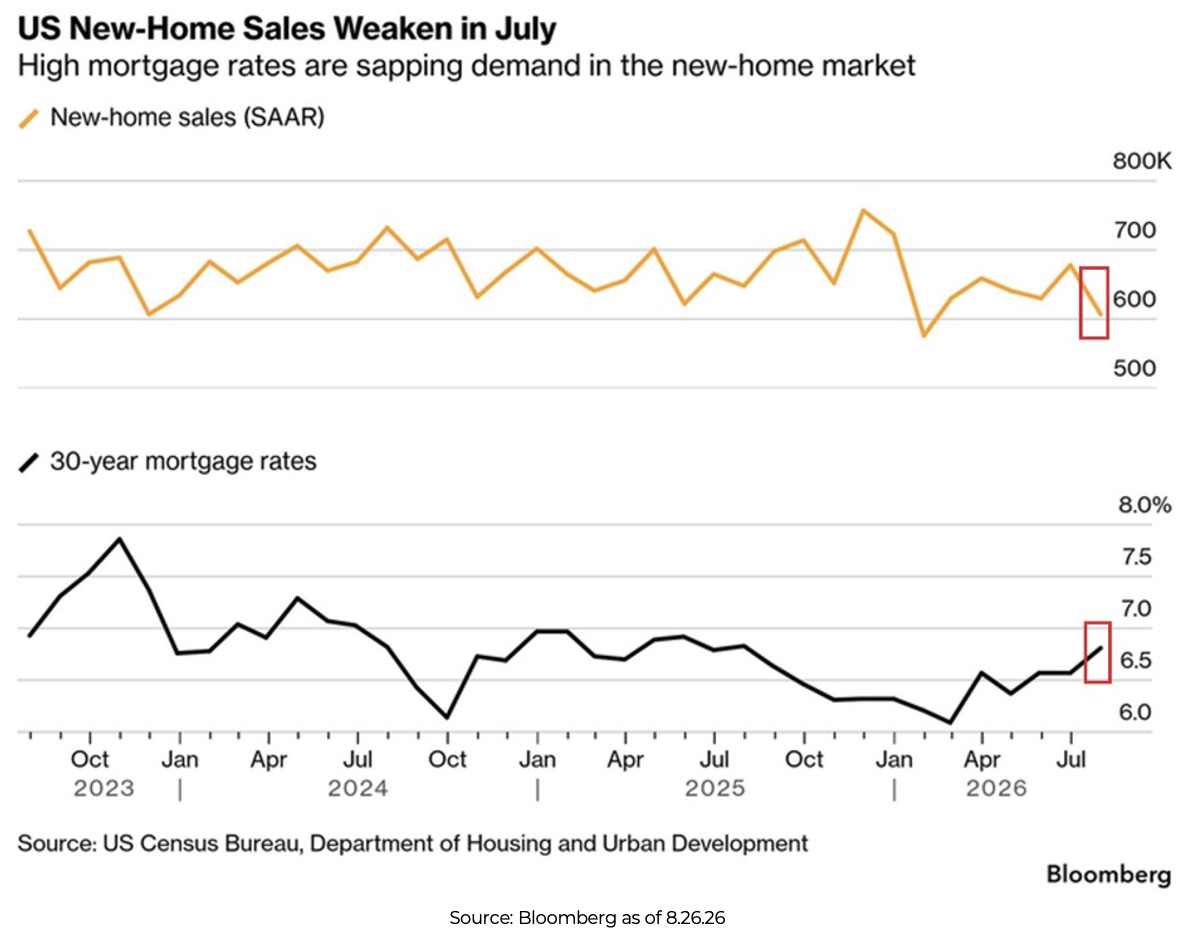
Derek: Housing remains the weakest pocket. New home sales have slid and continue to flatline over the past few years as interest rates remain an impediment.
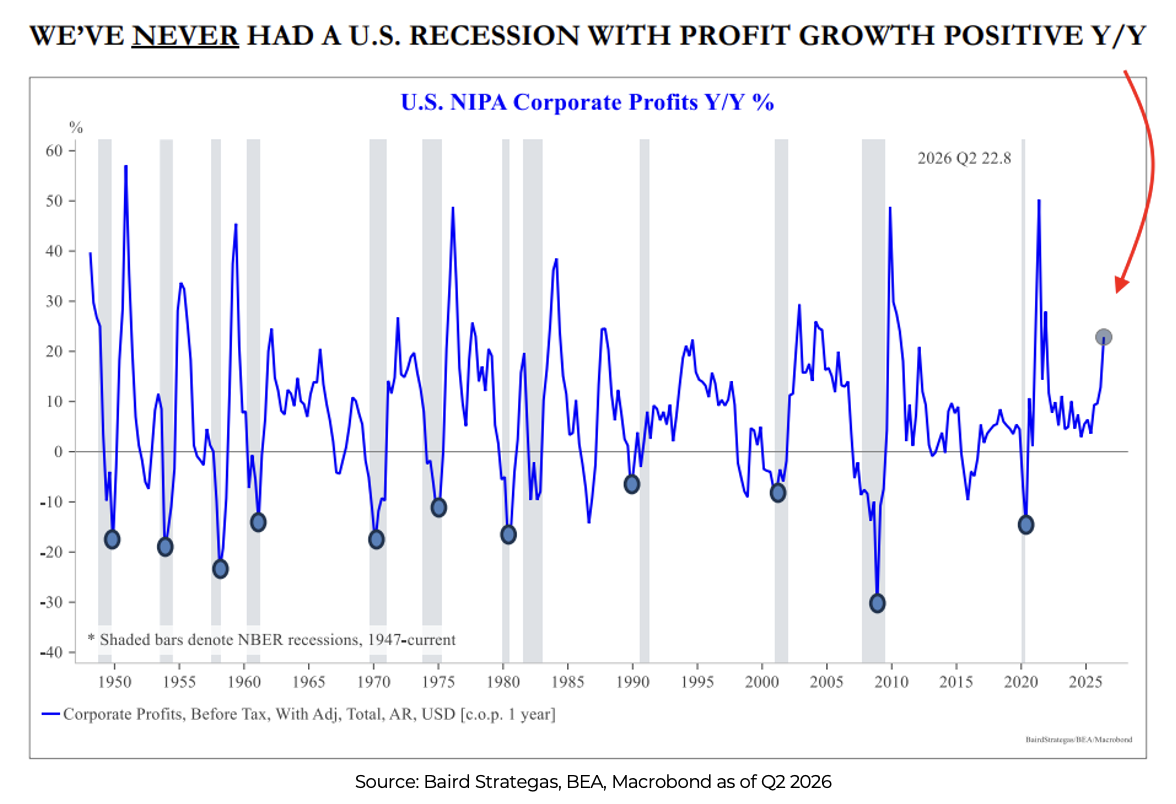
Brian: Recession callers keep running into one challenge. Corporate profits are up 22.8% year over year, and this country has never entered a recession with profit growth positive.
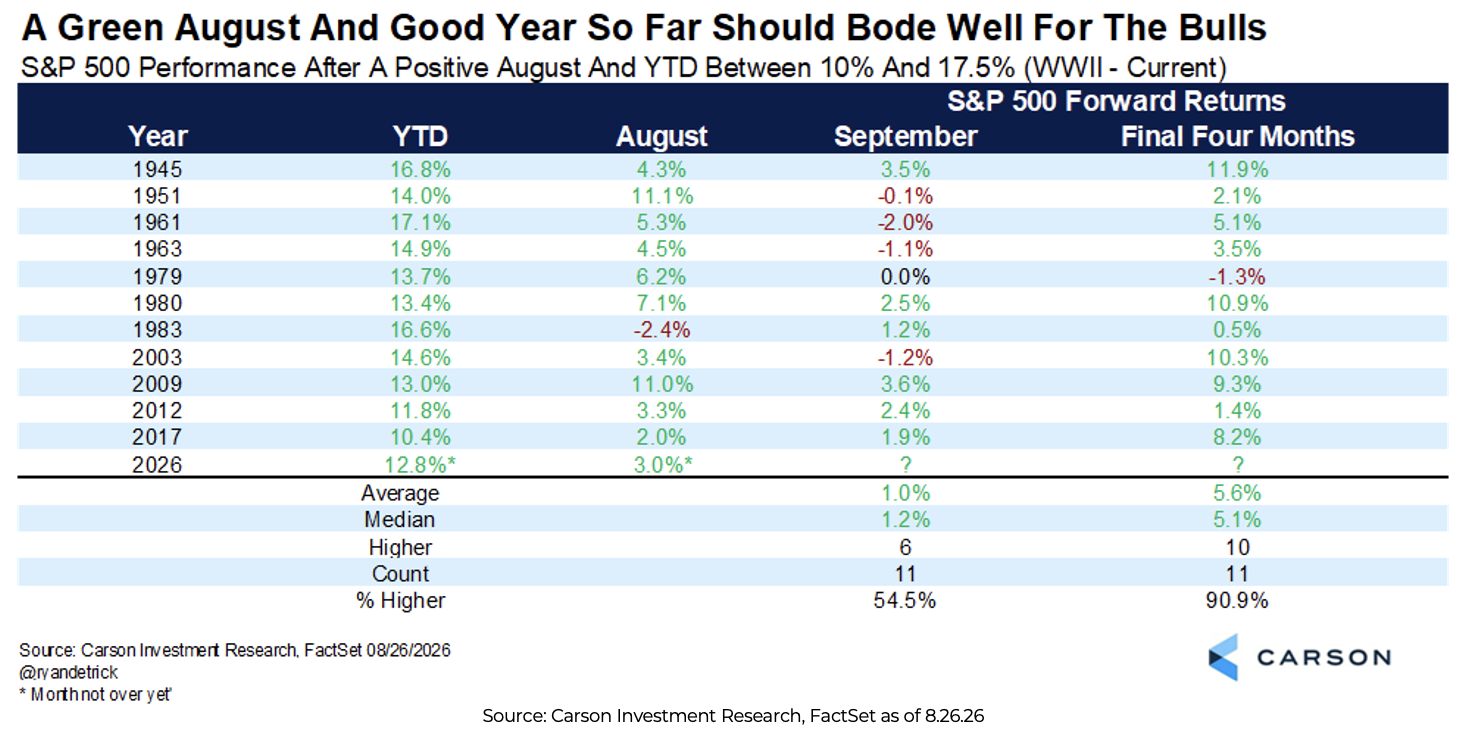
Mark: The calendar is on the bulls’ side as well. Since WWII, a green August paired with a double-digit year-to-date gain has led to a higher final four months in 10 of 11 cases, averaging 5.6%.
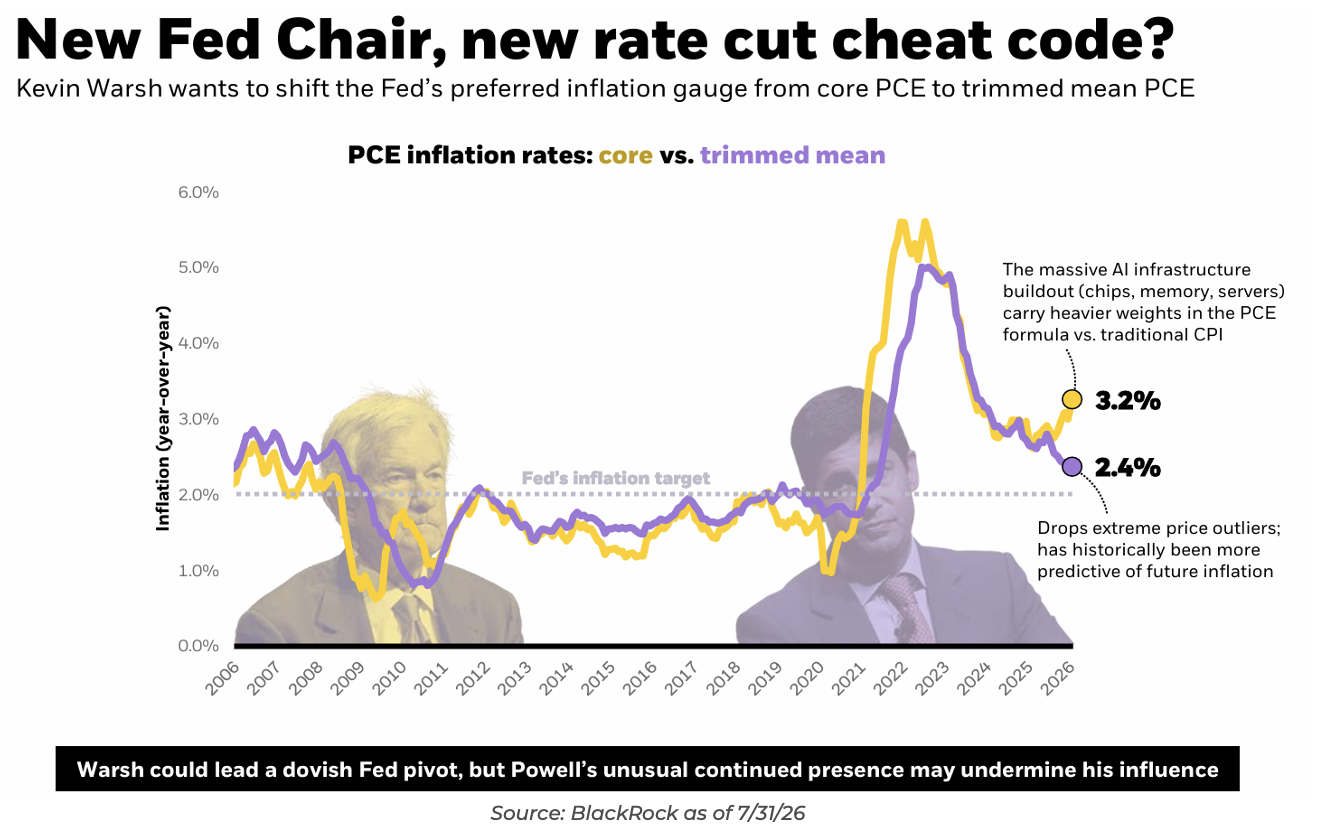
Jake: The Fed remains the wild card. Fed Chair Warsh wants trimmed-mean PCE as the preferred gauge, and that measure reads 2.4% while core sits at 3.2%.
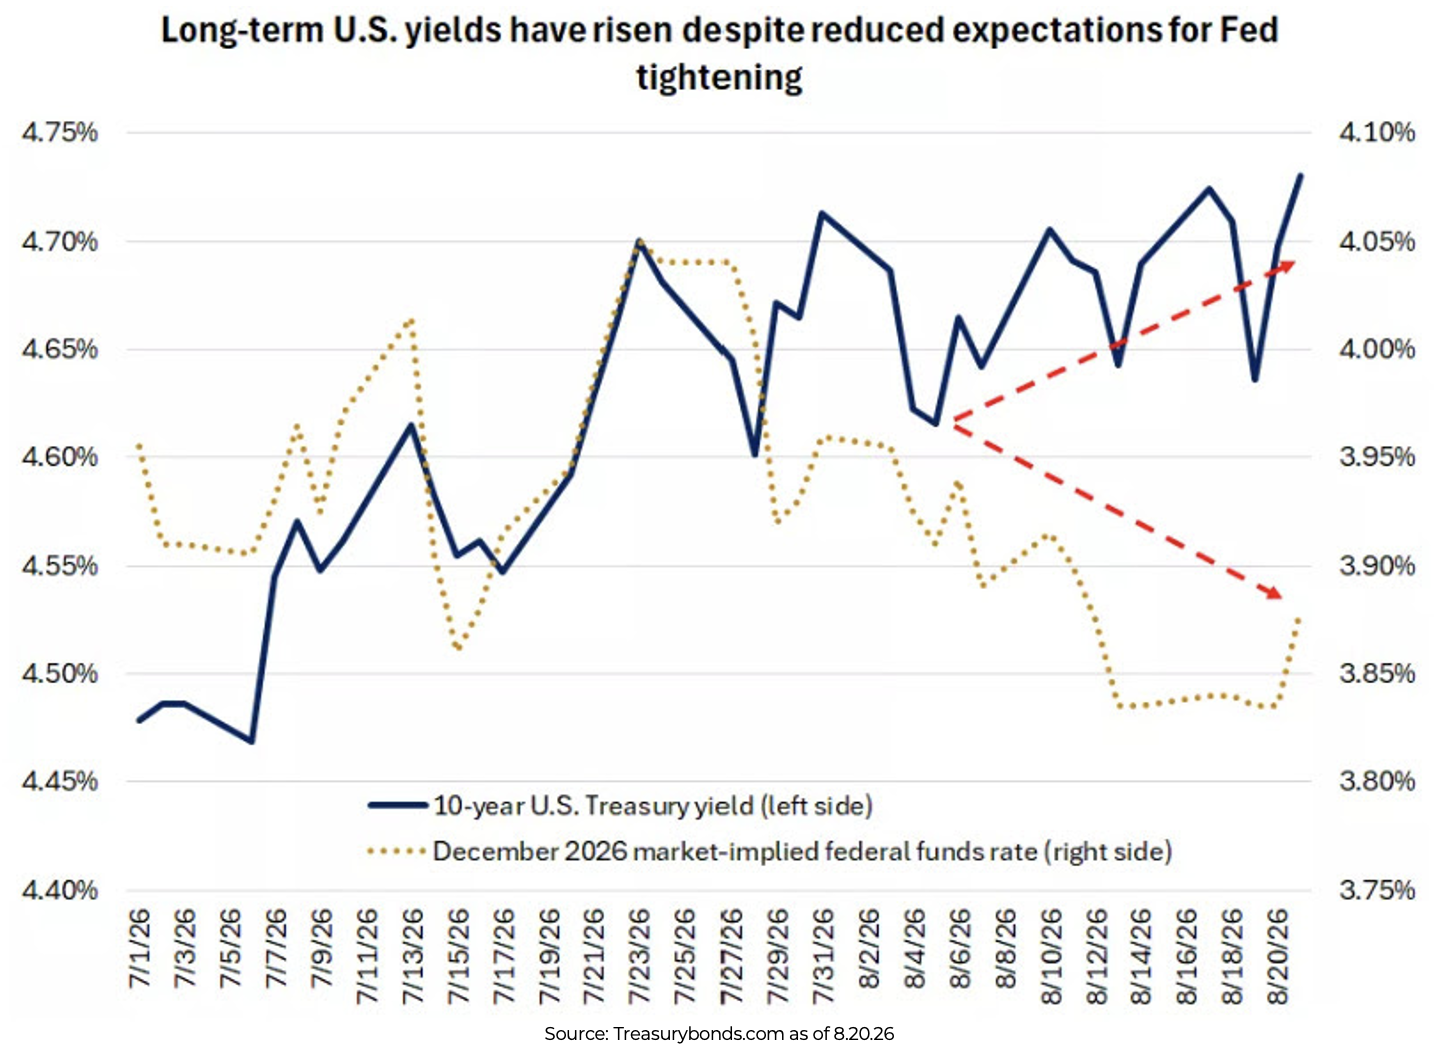
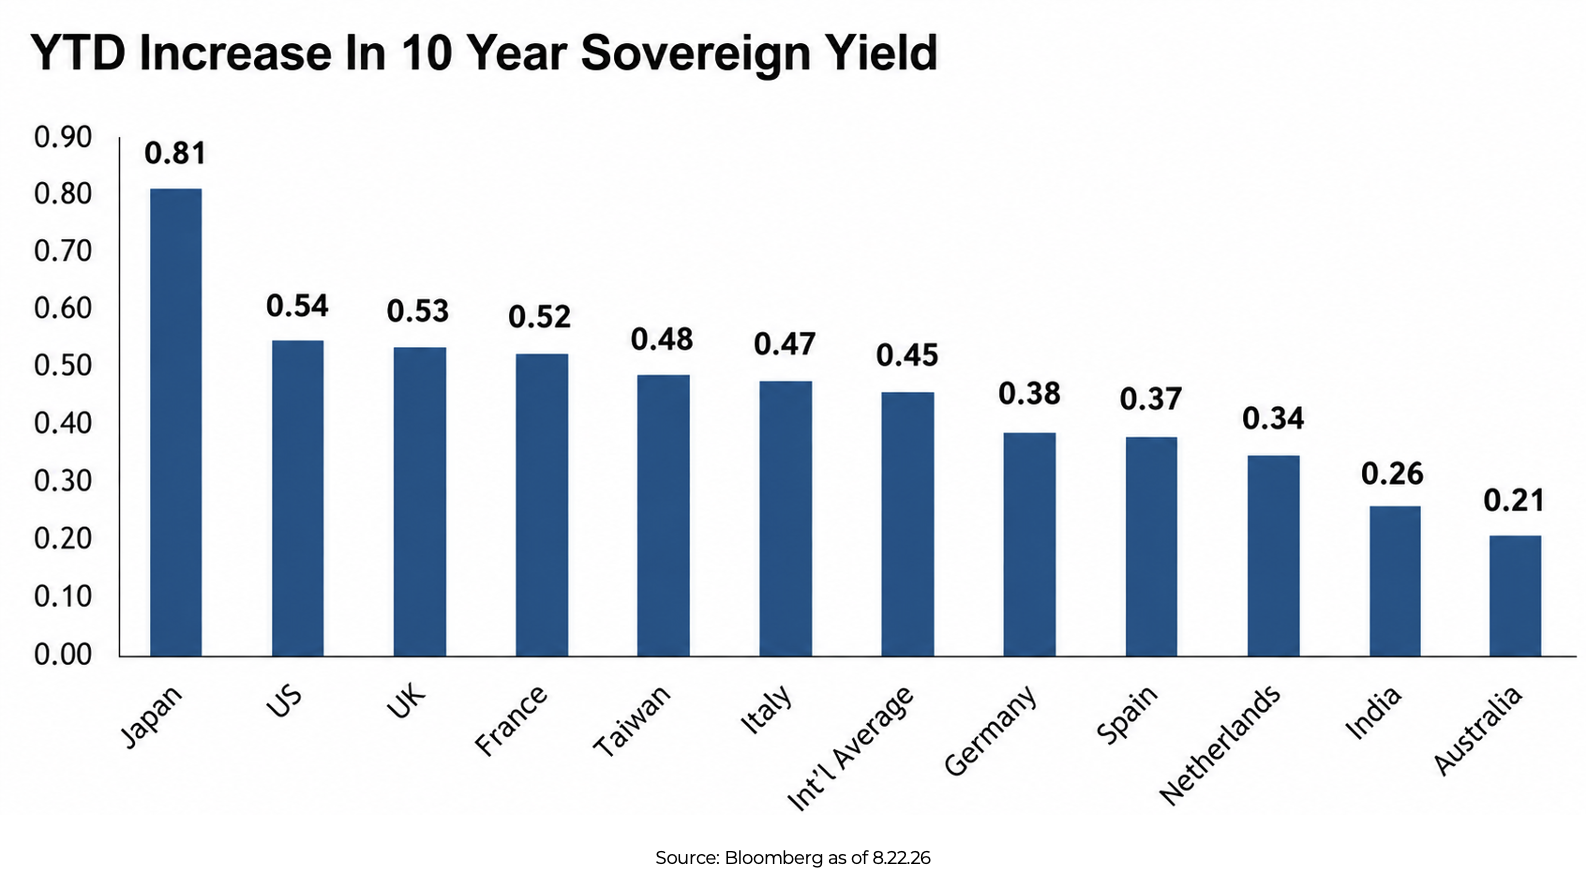
Brett: While cuts are starting to get priced in, long rates are going the other way. The 10-year has climbed to 4.73% while the market’s December 2026 funds rate keeps falling.
Ten: It is not just us. Ten-year yields are higher on the year everywhere, with Japan up 81 bps and the U.S. next at 54 bps.
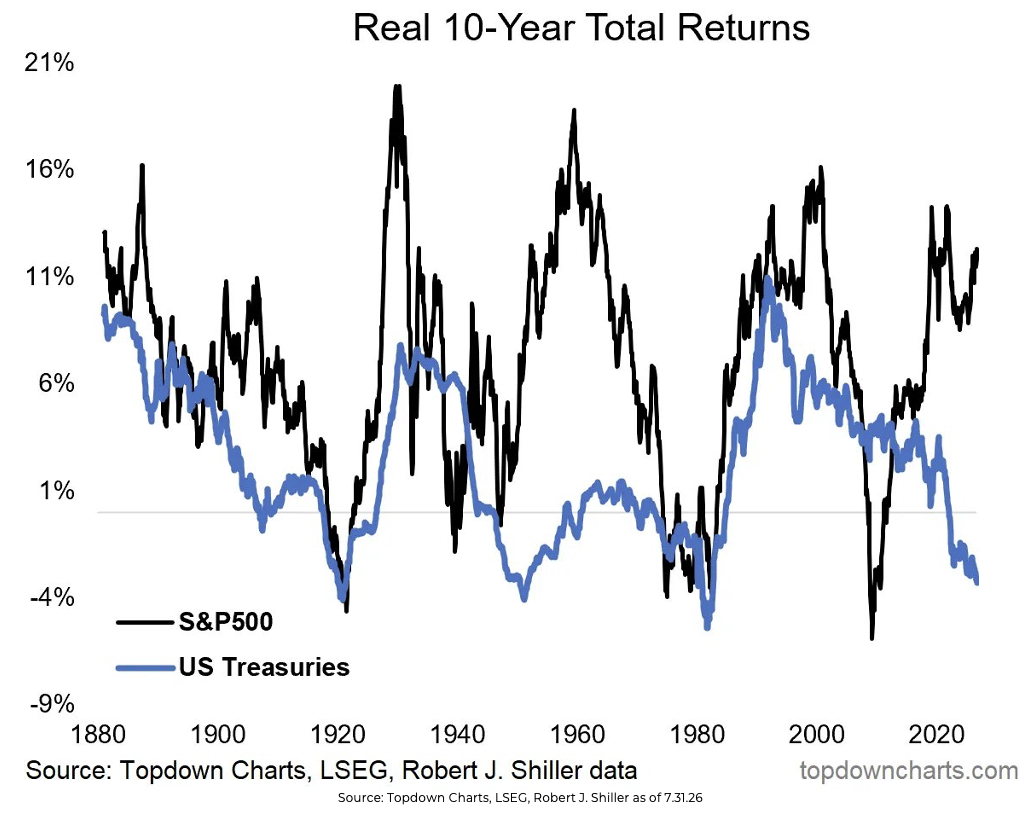
Joseph: A full decade of returns shows why nominal bonds may no longer reliably play their old role. Real 10-year total returns for Treasuries were negative, the worst since the early 1980s, while the S&P 500 sits above 11%.
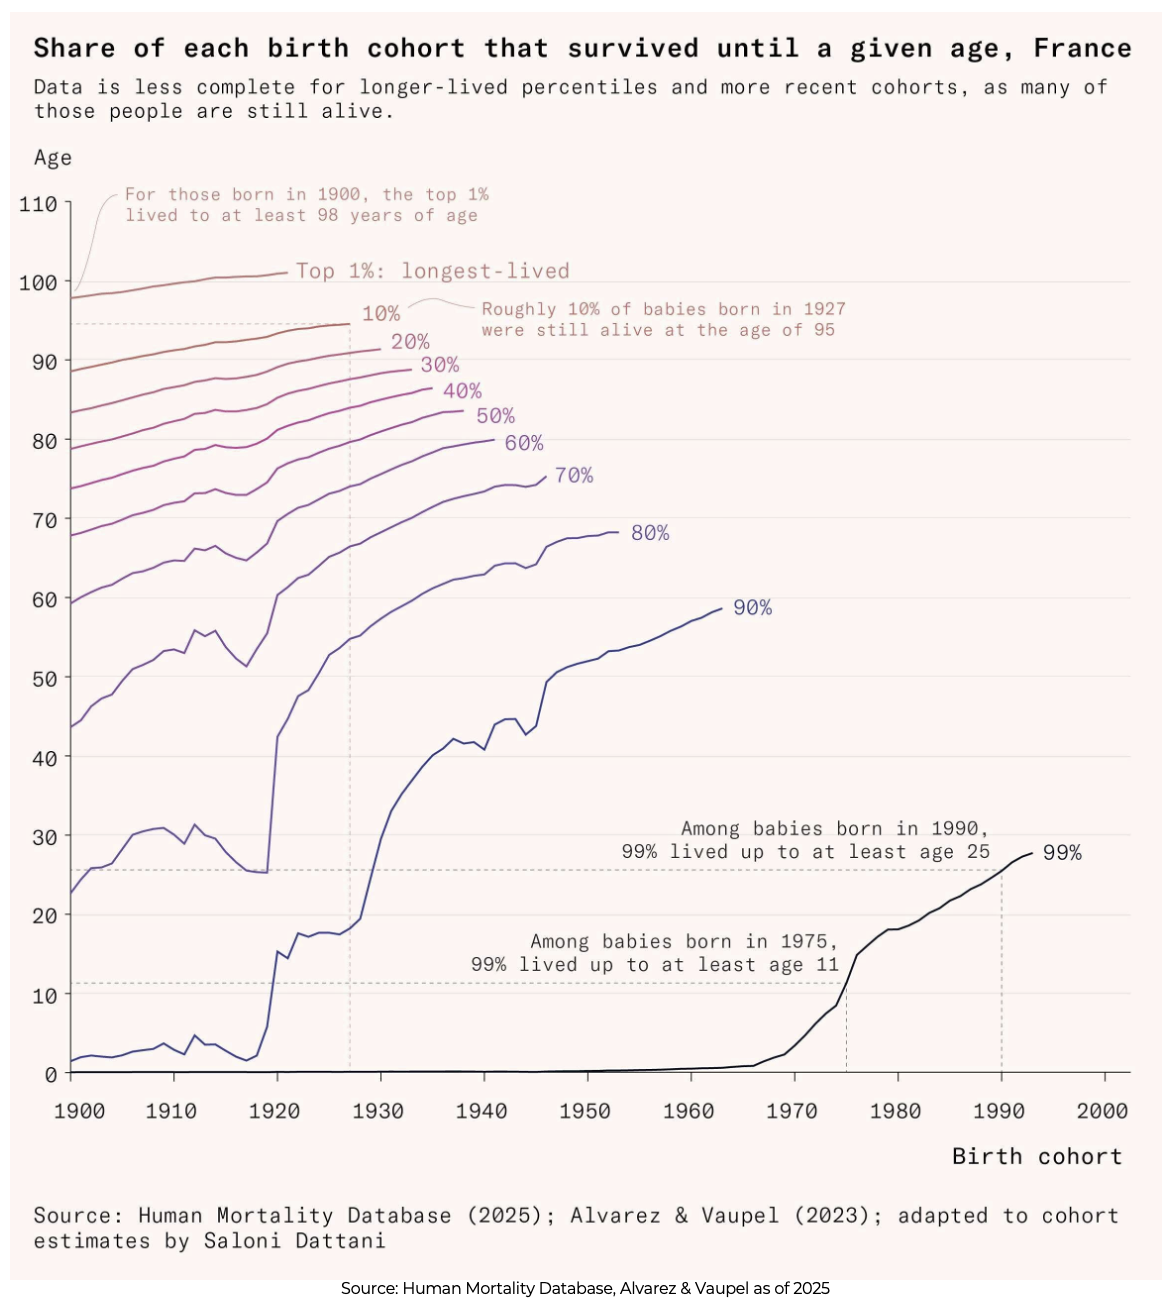
JD: Despite everything going on in the world, it’s always good to remember how much things have improved over time. Ninety-nine percent of babies born in 1990 lived to at least 25, and that longevity is the real argument for capitalism and investing in decades rather than quarters.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2608-34.