
Our team looks at a lot of research throughout the day. Here are a handful of charts we think are good summations of investor activity, from a hawkish repricing in rates against cooling wages, to the narrowest market breadth since the dot-com era, record earnings beats, starting bond yields that set up better returns ahead, and households on solid footing. Have a great weekend!
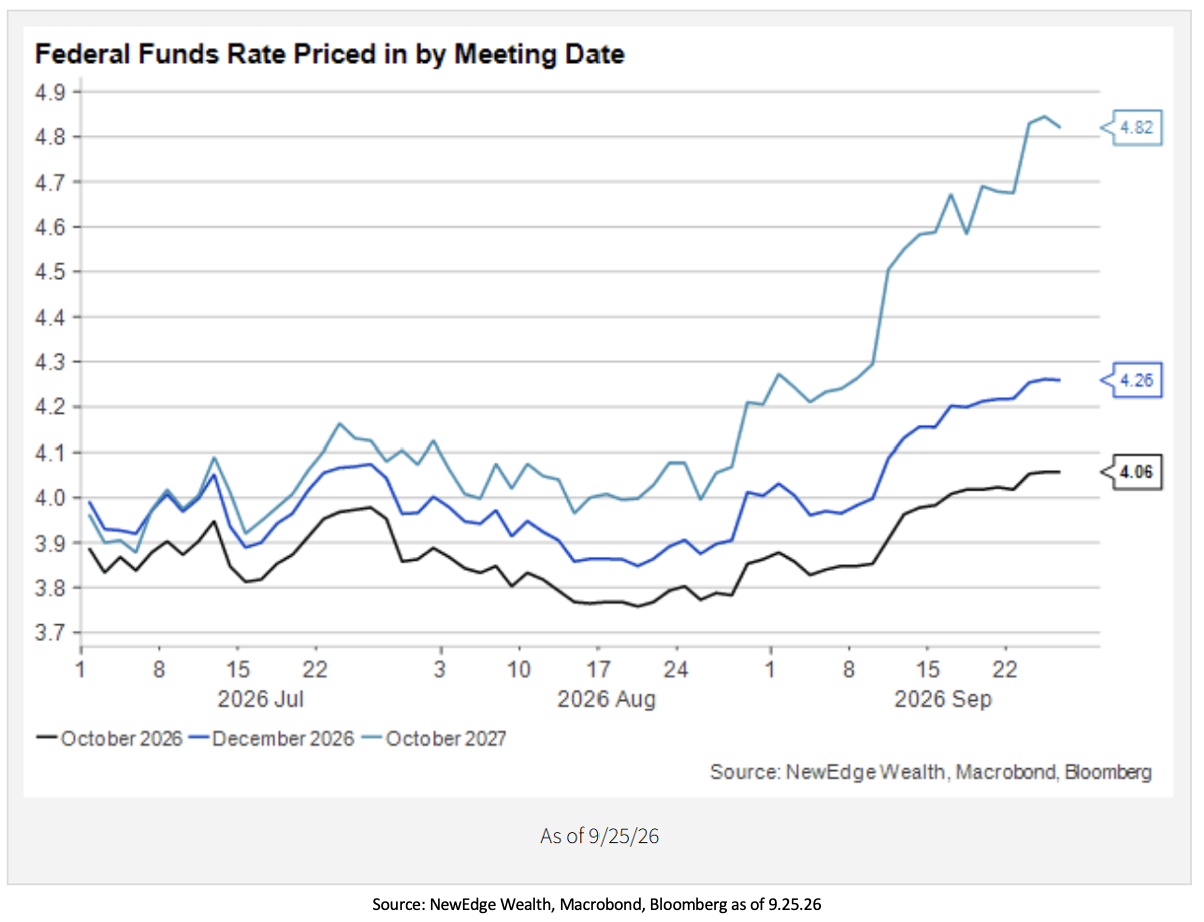
Jake: Interest rates have leaned towards a hawkish Fed fast. Fed funds pricing for October 2027 jumped to 4.82% from roughly 4.0% in late August.
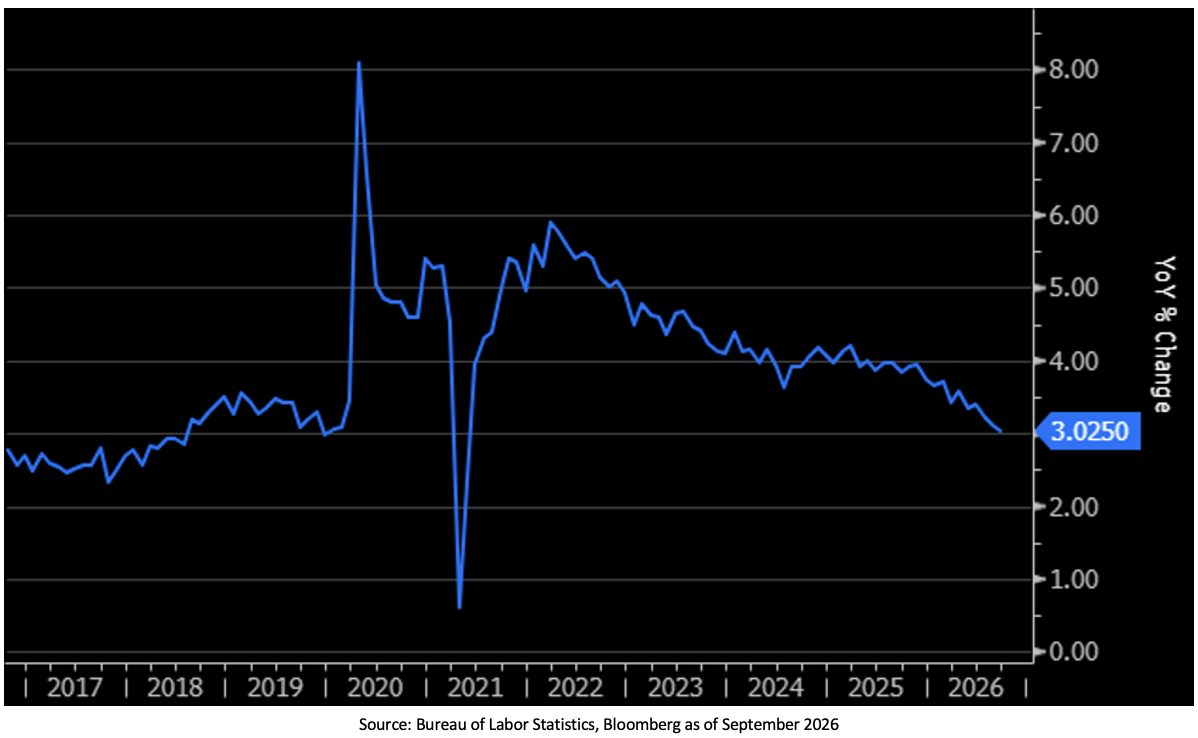
Dave: Yet wages do not appear to be the problem. Average hourly earnings grew 3.02% YoY in September, down from the 2022 cycle high near 5.9% and back within pre-pandemic norms.
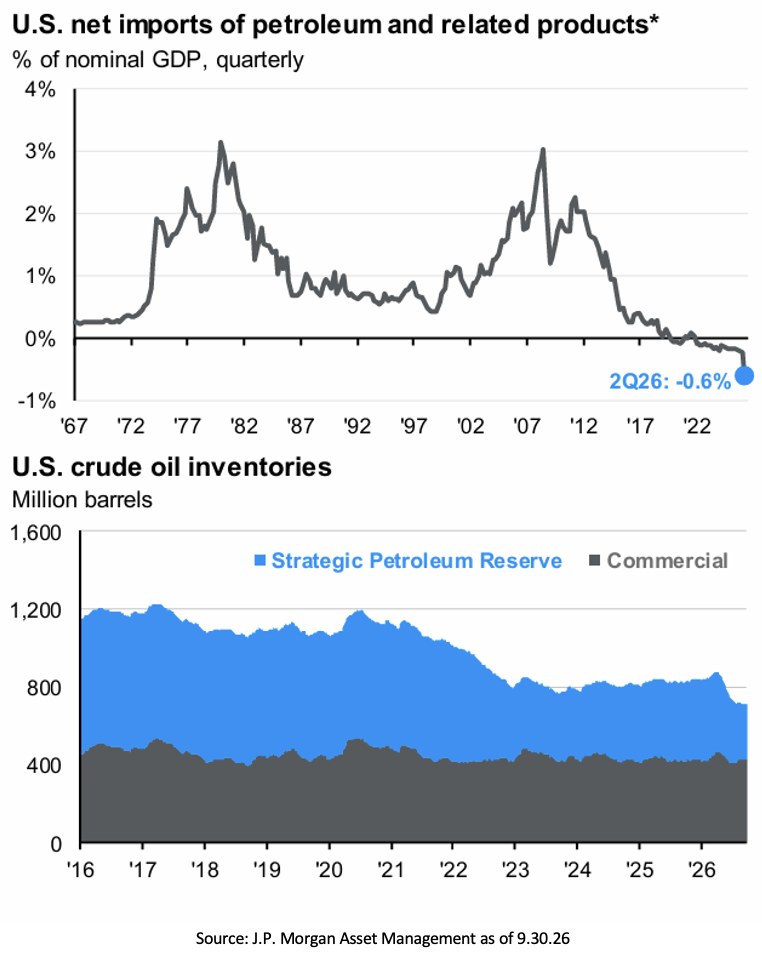
Brian: The energy spike that has pushed rates higher does not have the same economic impact it once had. Net petroleum imports sit at -0.6% of GDP, the deepest net exporter position in data back to 1967.
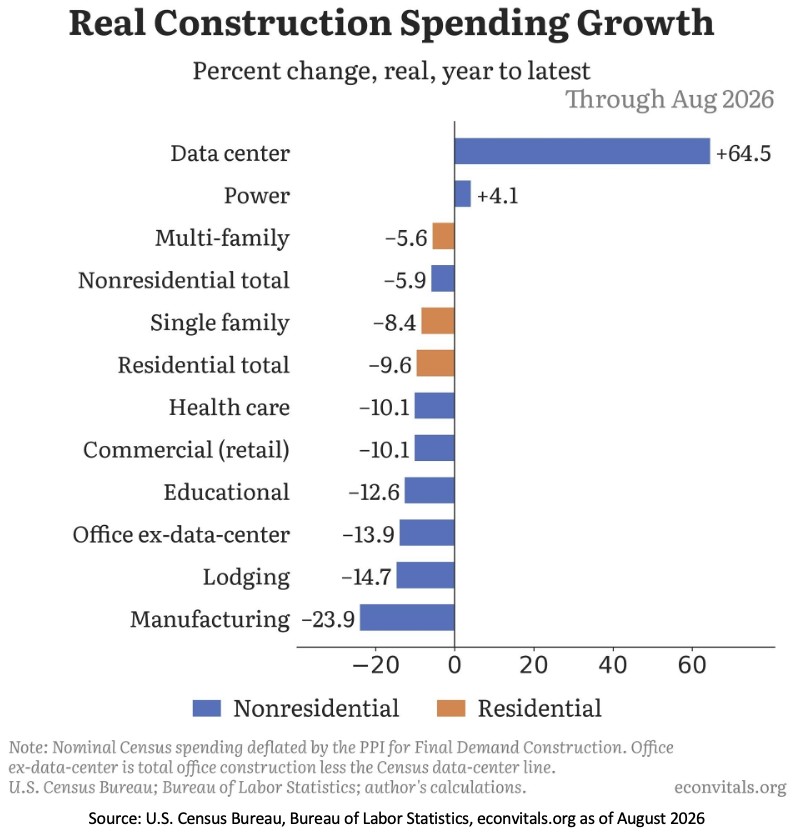
Mike: The real economy is cooling everywhere except AI (or perhaps crowding out everything else). Real construction spending is up 64.5% for data centers over the past year, while manufacturing is down 23.9% and residential is down 9.6%.
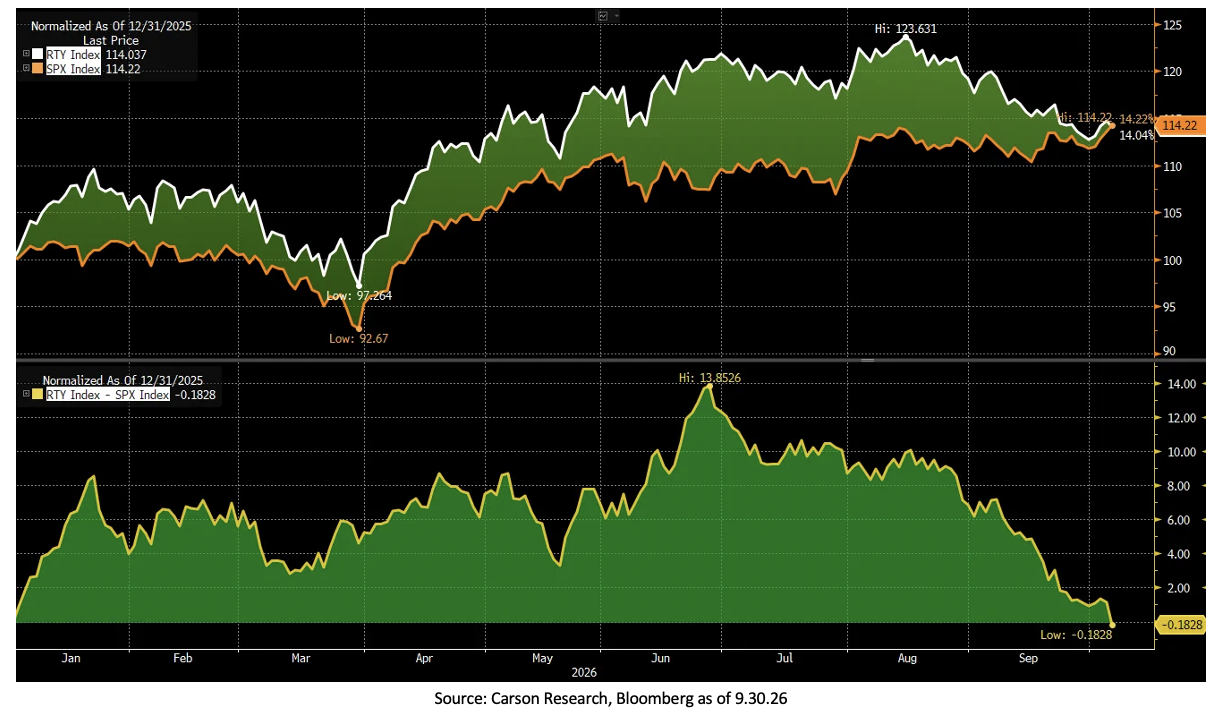
Derek: Markets are absorbing higher rates in a very start and stop fashion within their respective asset class. For example, this year’s outperformance of small caps is gone. The Russell 2000 had led the S&P 500 by 13.85% on June 26 and now trails.
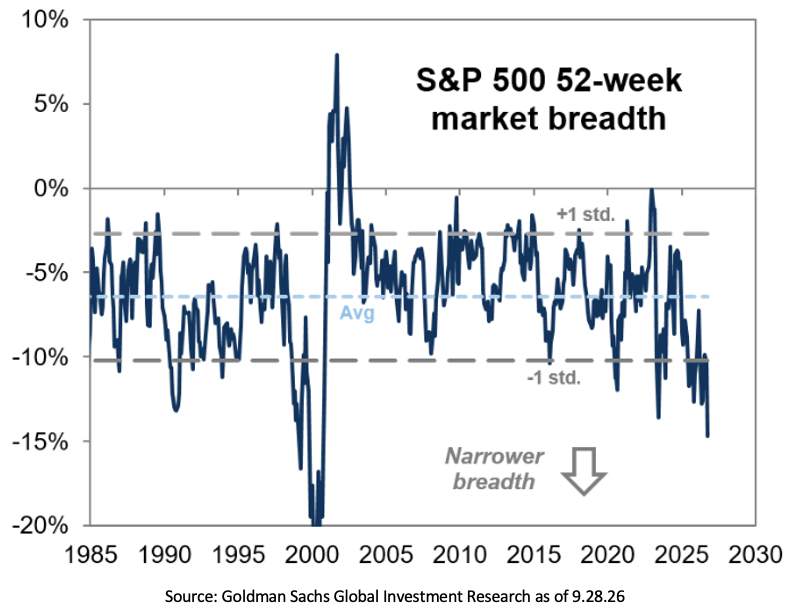
Joseph: Within the S&P 500 Index, breadth is the narrowest since the dot-com era. The S&P 500’s 52-week breadth gauge sits near -15%, well below its -1 standard deviation band.
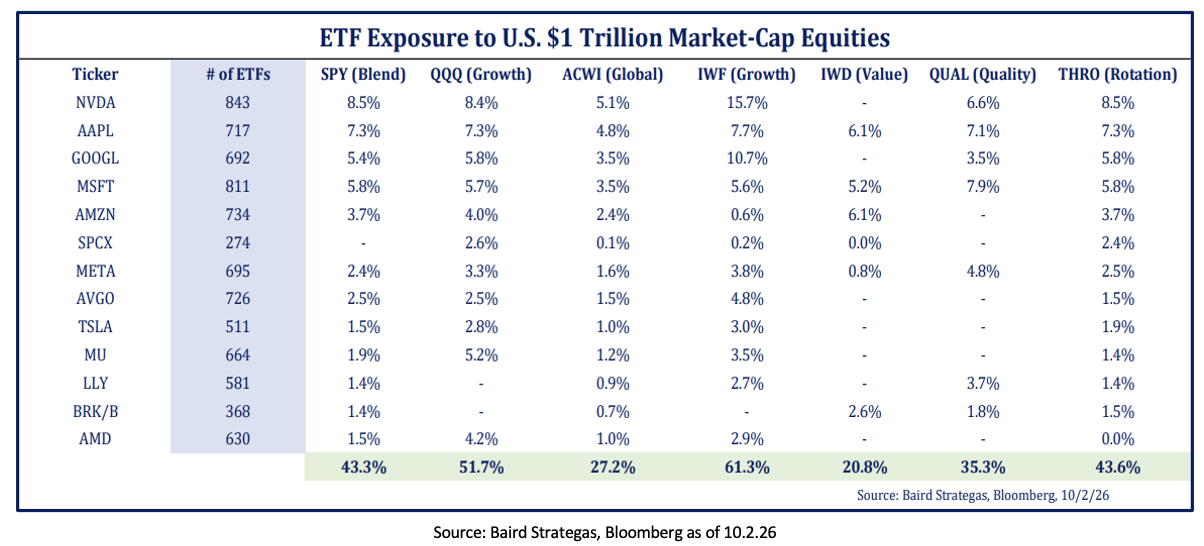
Brett: Part of the reason may be the increased nature of passive investing. NVDA alone sits in 843 ETFs, and 13 trillion-dollar stocks now make up 43% of SPY and 61% of IWF.
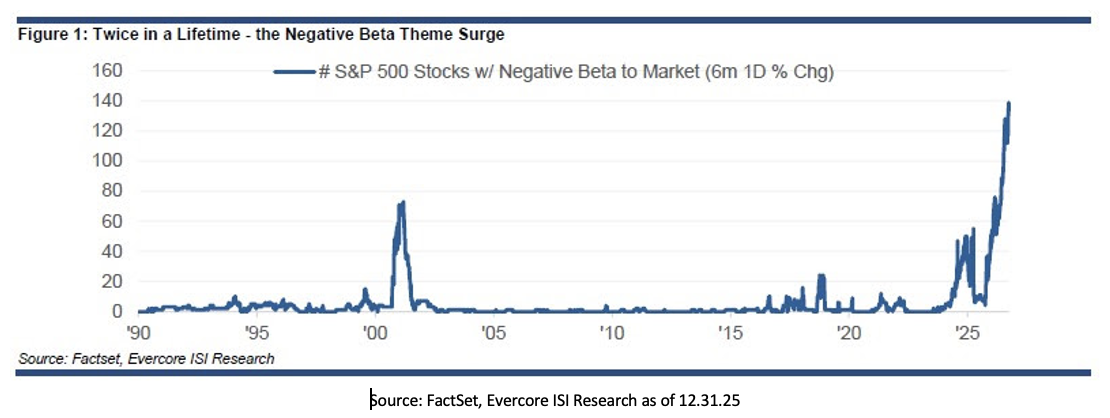
Bennett: The dispersion underneath is extreme, with about 140 S&P 500 stocks now carrying a negative six-month beta to the index, roughly double the dot-com peak.
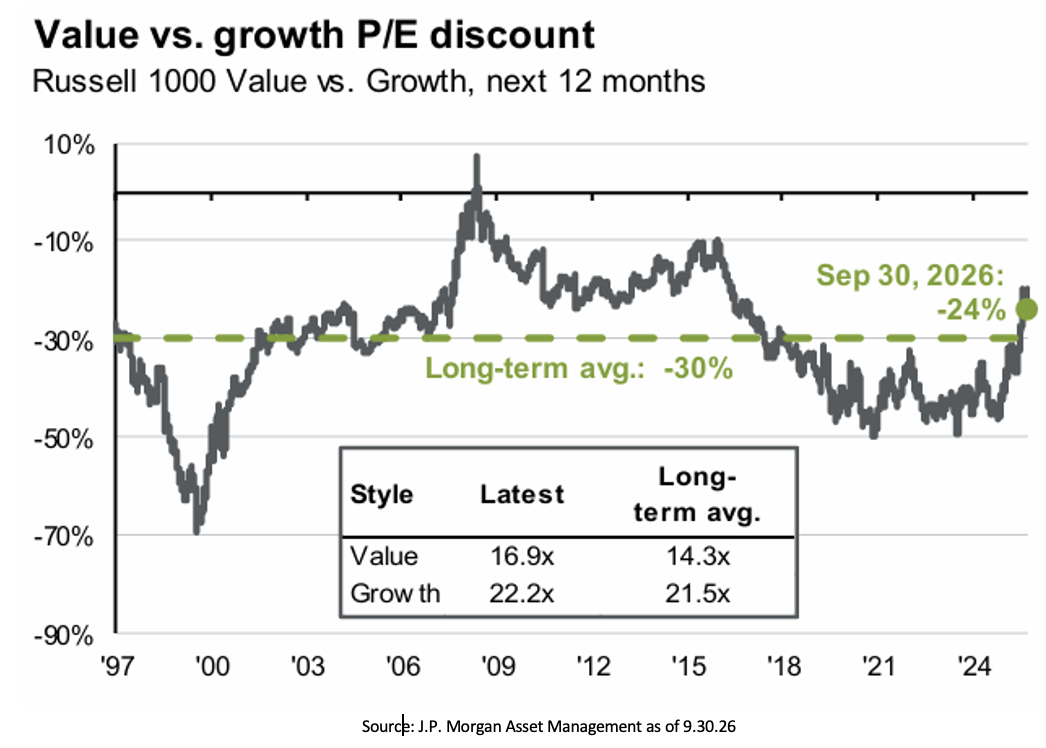
Mark: Yet strong fundamentals of the largest growth companies have pushed value’s P/E discount to growth to 24%, inside its 30% long-term average for the first time since 2018.
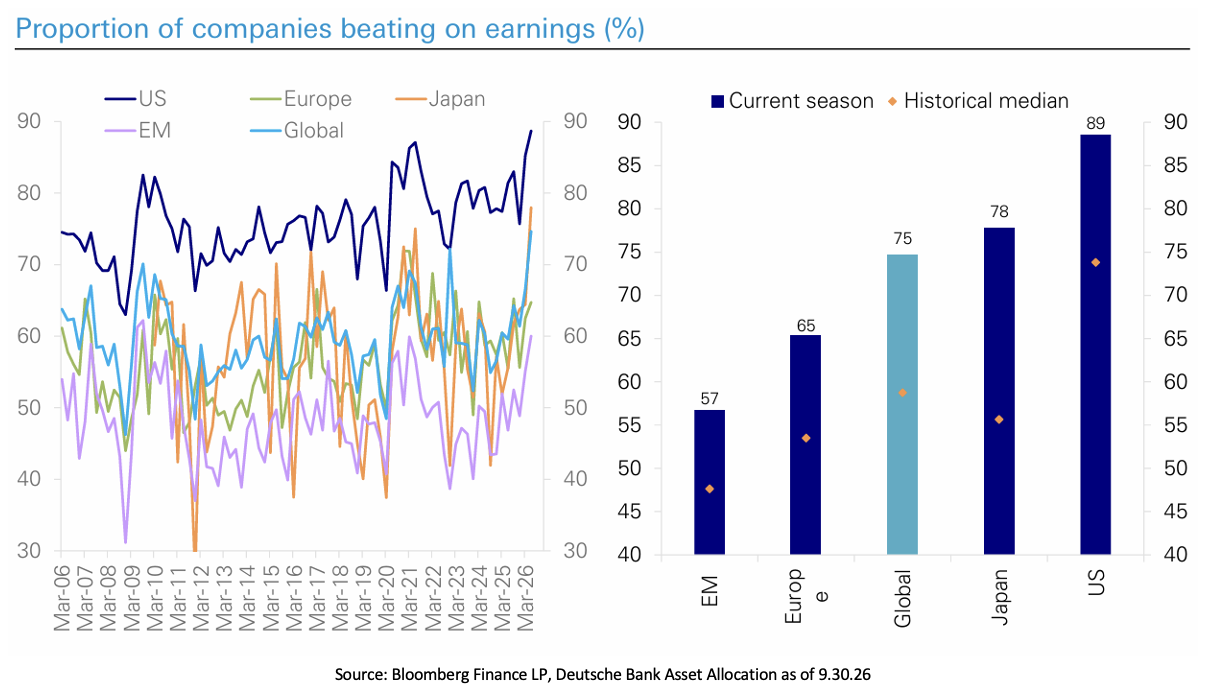
Beckham: Fundamentals are holding up well across all markets. A record 89% of US companies beat estimates this season, well above the ~74% historical median.
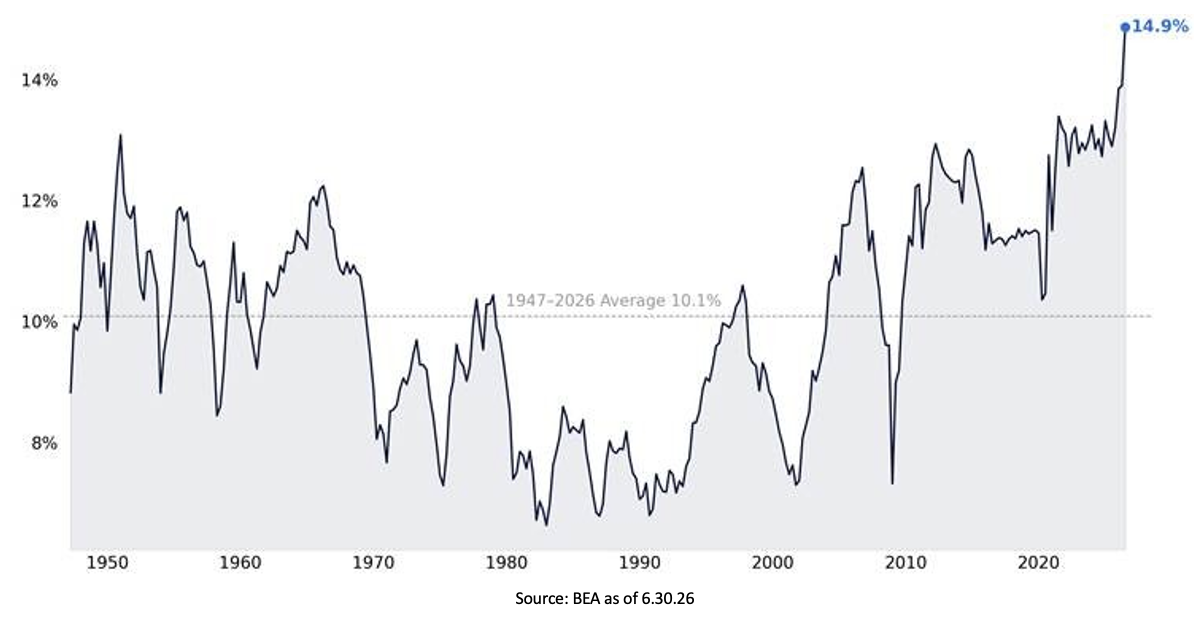
John: This has pushed corporate profit to 14.9% of GDP, the highest share on record going back to 1947, and well above the 10.1% long-term average.
Ten: The strength in stocks has been met by a mirror image in bonds that have lagged. Rolling returns on the 10-year Treasury are still near the worst on record, with real 5- and 10-year returns around -3% annualized.
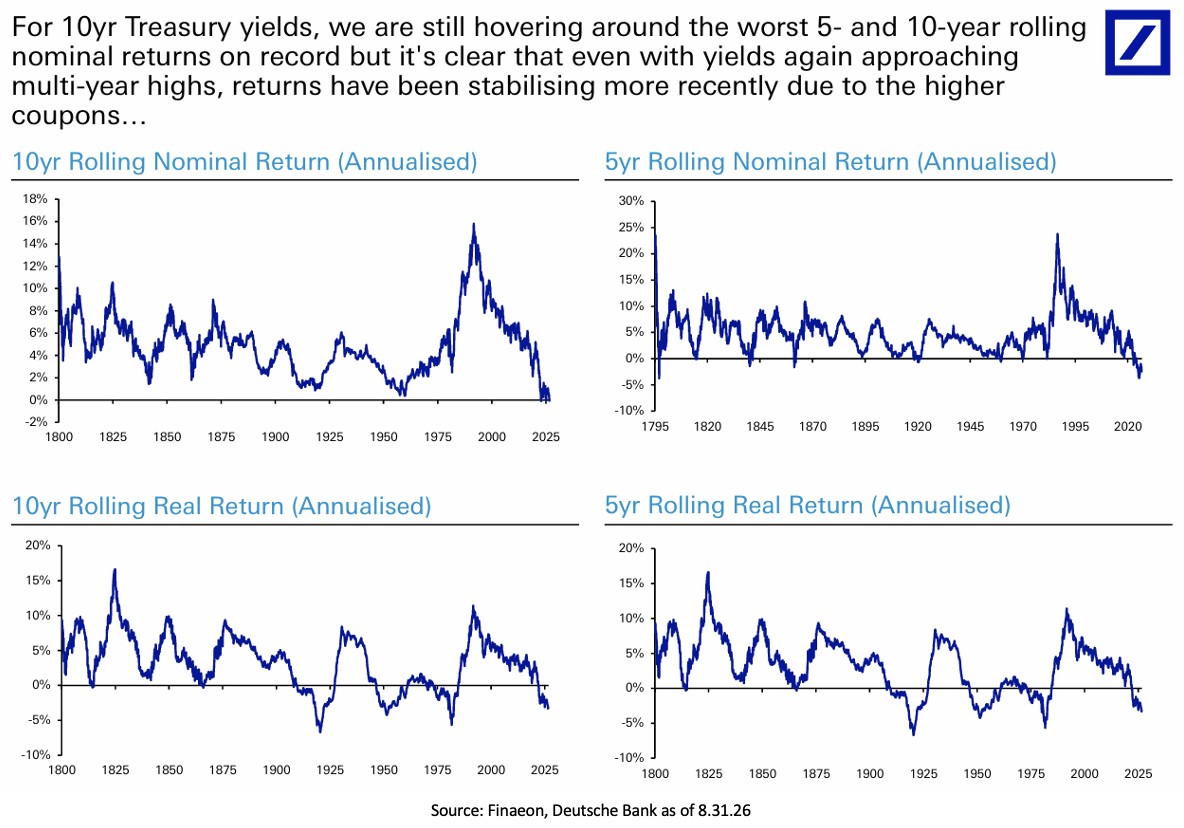
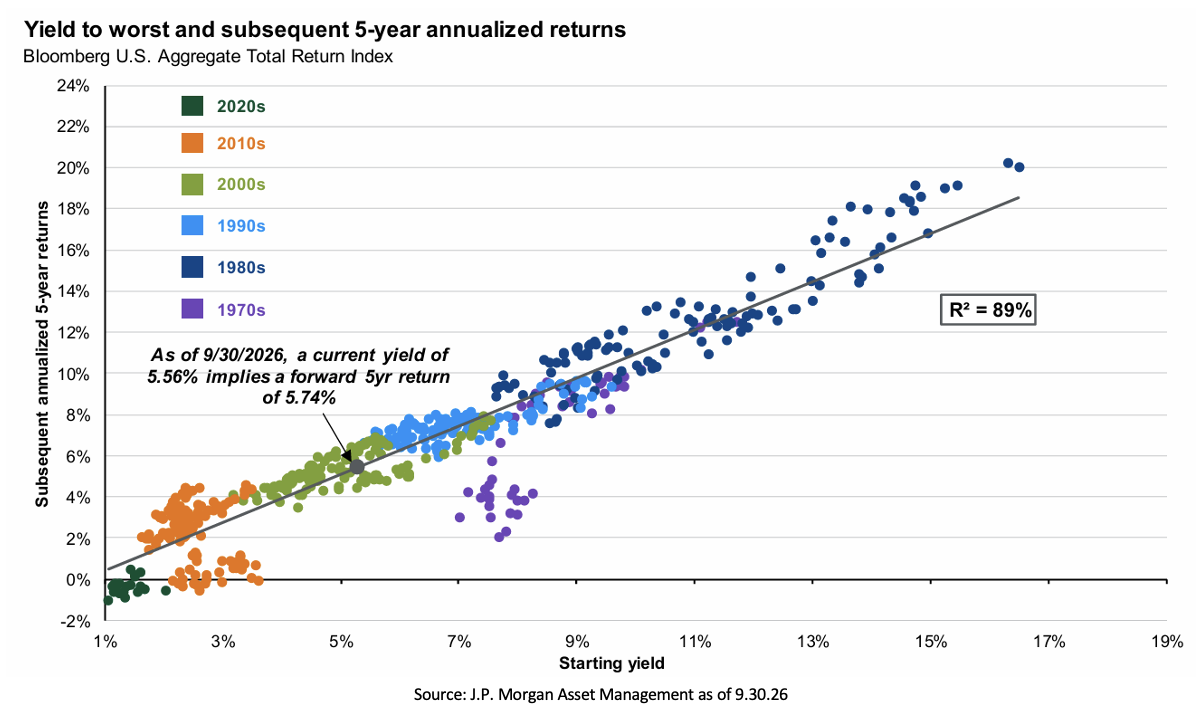
John Luke: That does set up better returns ahead. With the 10-year at 5%+ starting yield, the Agg is poised for 5%+ annualized returns over the next seven years.
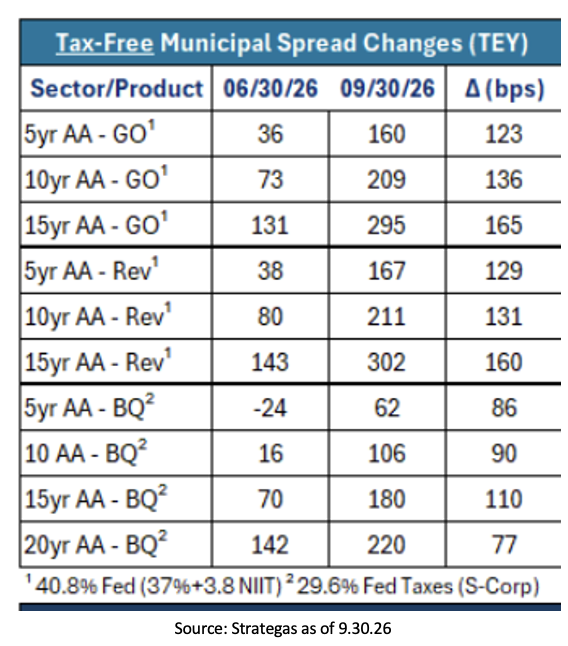
JG: Munis repriced even faster during Q3. Tax-equivalent spreads on AA GOs widened 123 to 165 bps across the curve last quarter.
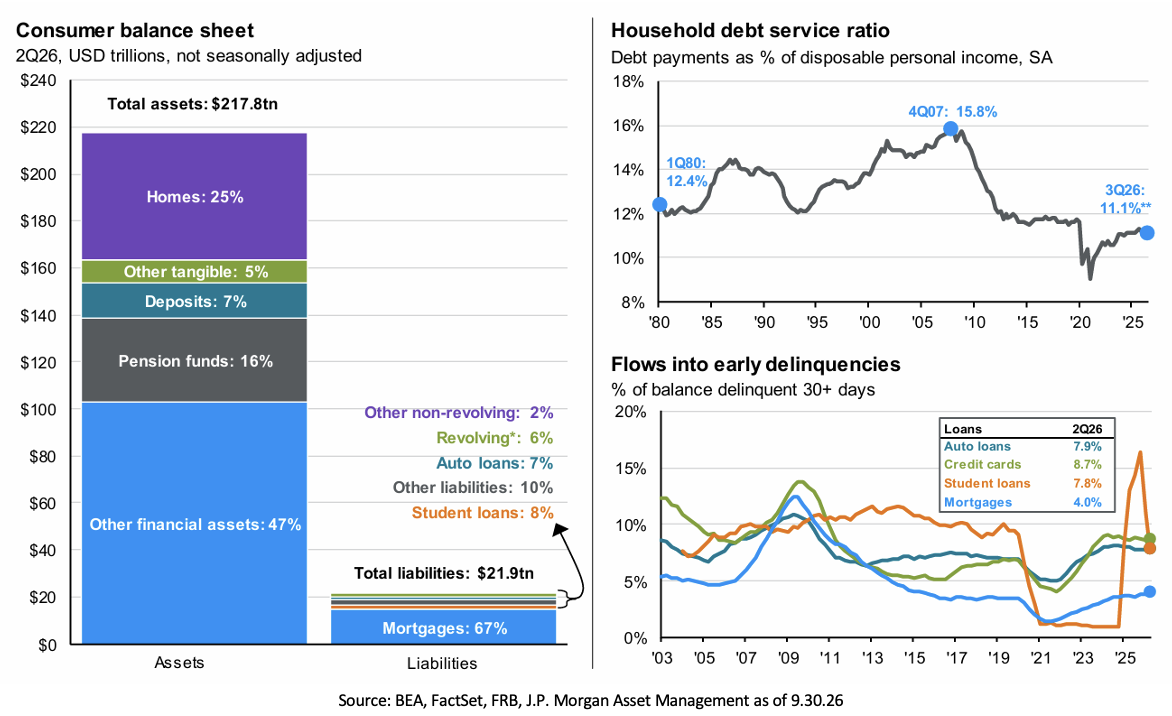
Brad: Households are on solid footing. Debt payments take just 11.1% of disposable income versus 15.8% at the 2007 peak.
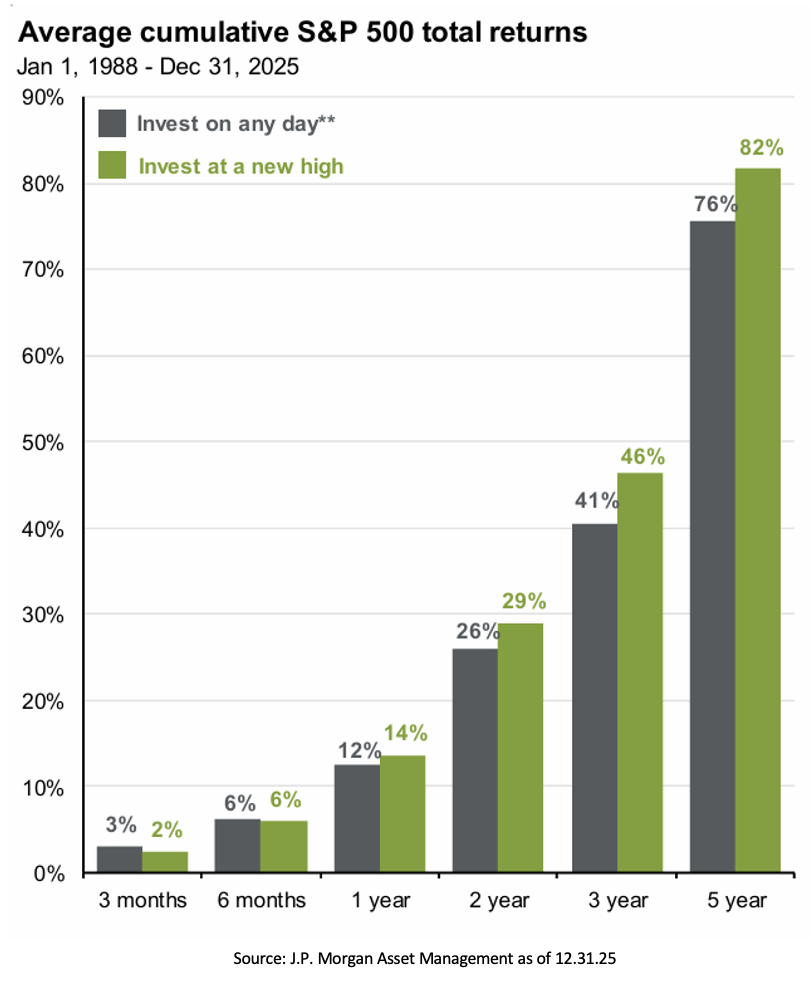
JD: The S&P 500 is back at all-time highs, and history says that is no reason to wait. Since 1988, investing at a new high returned 82% over five years on average versus 76% on any day.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2610-9.