
The FOMC left the fed funds rate unchanged, with no action for the fifth consecutive meeting, even as inflation lingers above target. No change was the broad consensus; however, there were whispers of potential for a rate hike (the market was pricing about a 30% chance going into the meeting).
The FOMC statement remained short and was nearly identical to the last meeting. There were three dissents. Beth Hammack, Neel Kashkari, and Lorie Logan preferred to raise the target range for the federal funds rate by 0.25%. Today marked the most dissents since the September 2016 meeting. Notably, Jay Powell was not one of the 3 dissenters, although, in my opinion, the market responded as if he had, as the long end of the yield curve rose meaningfully following Warsh’s press conference.
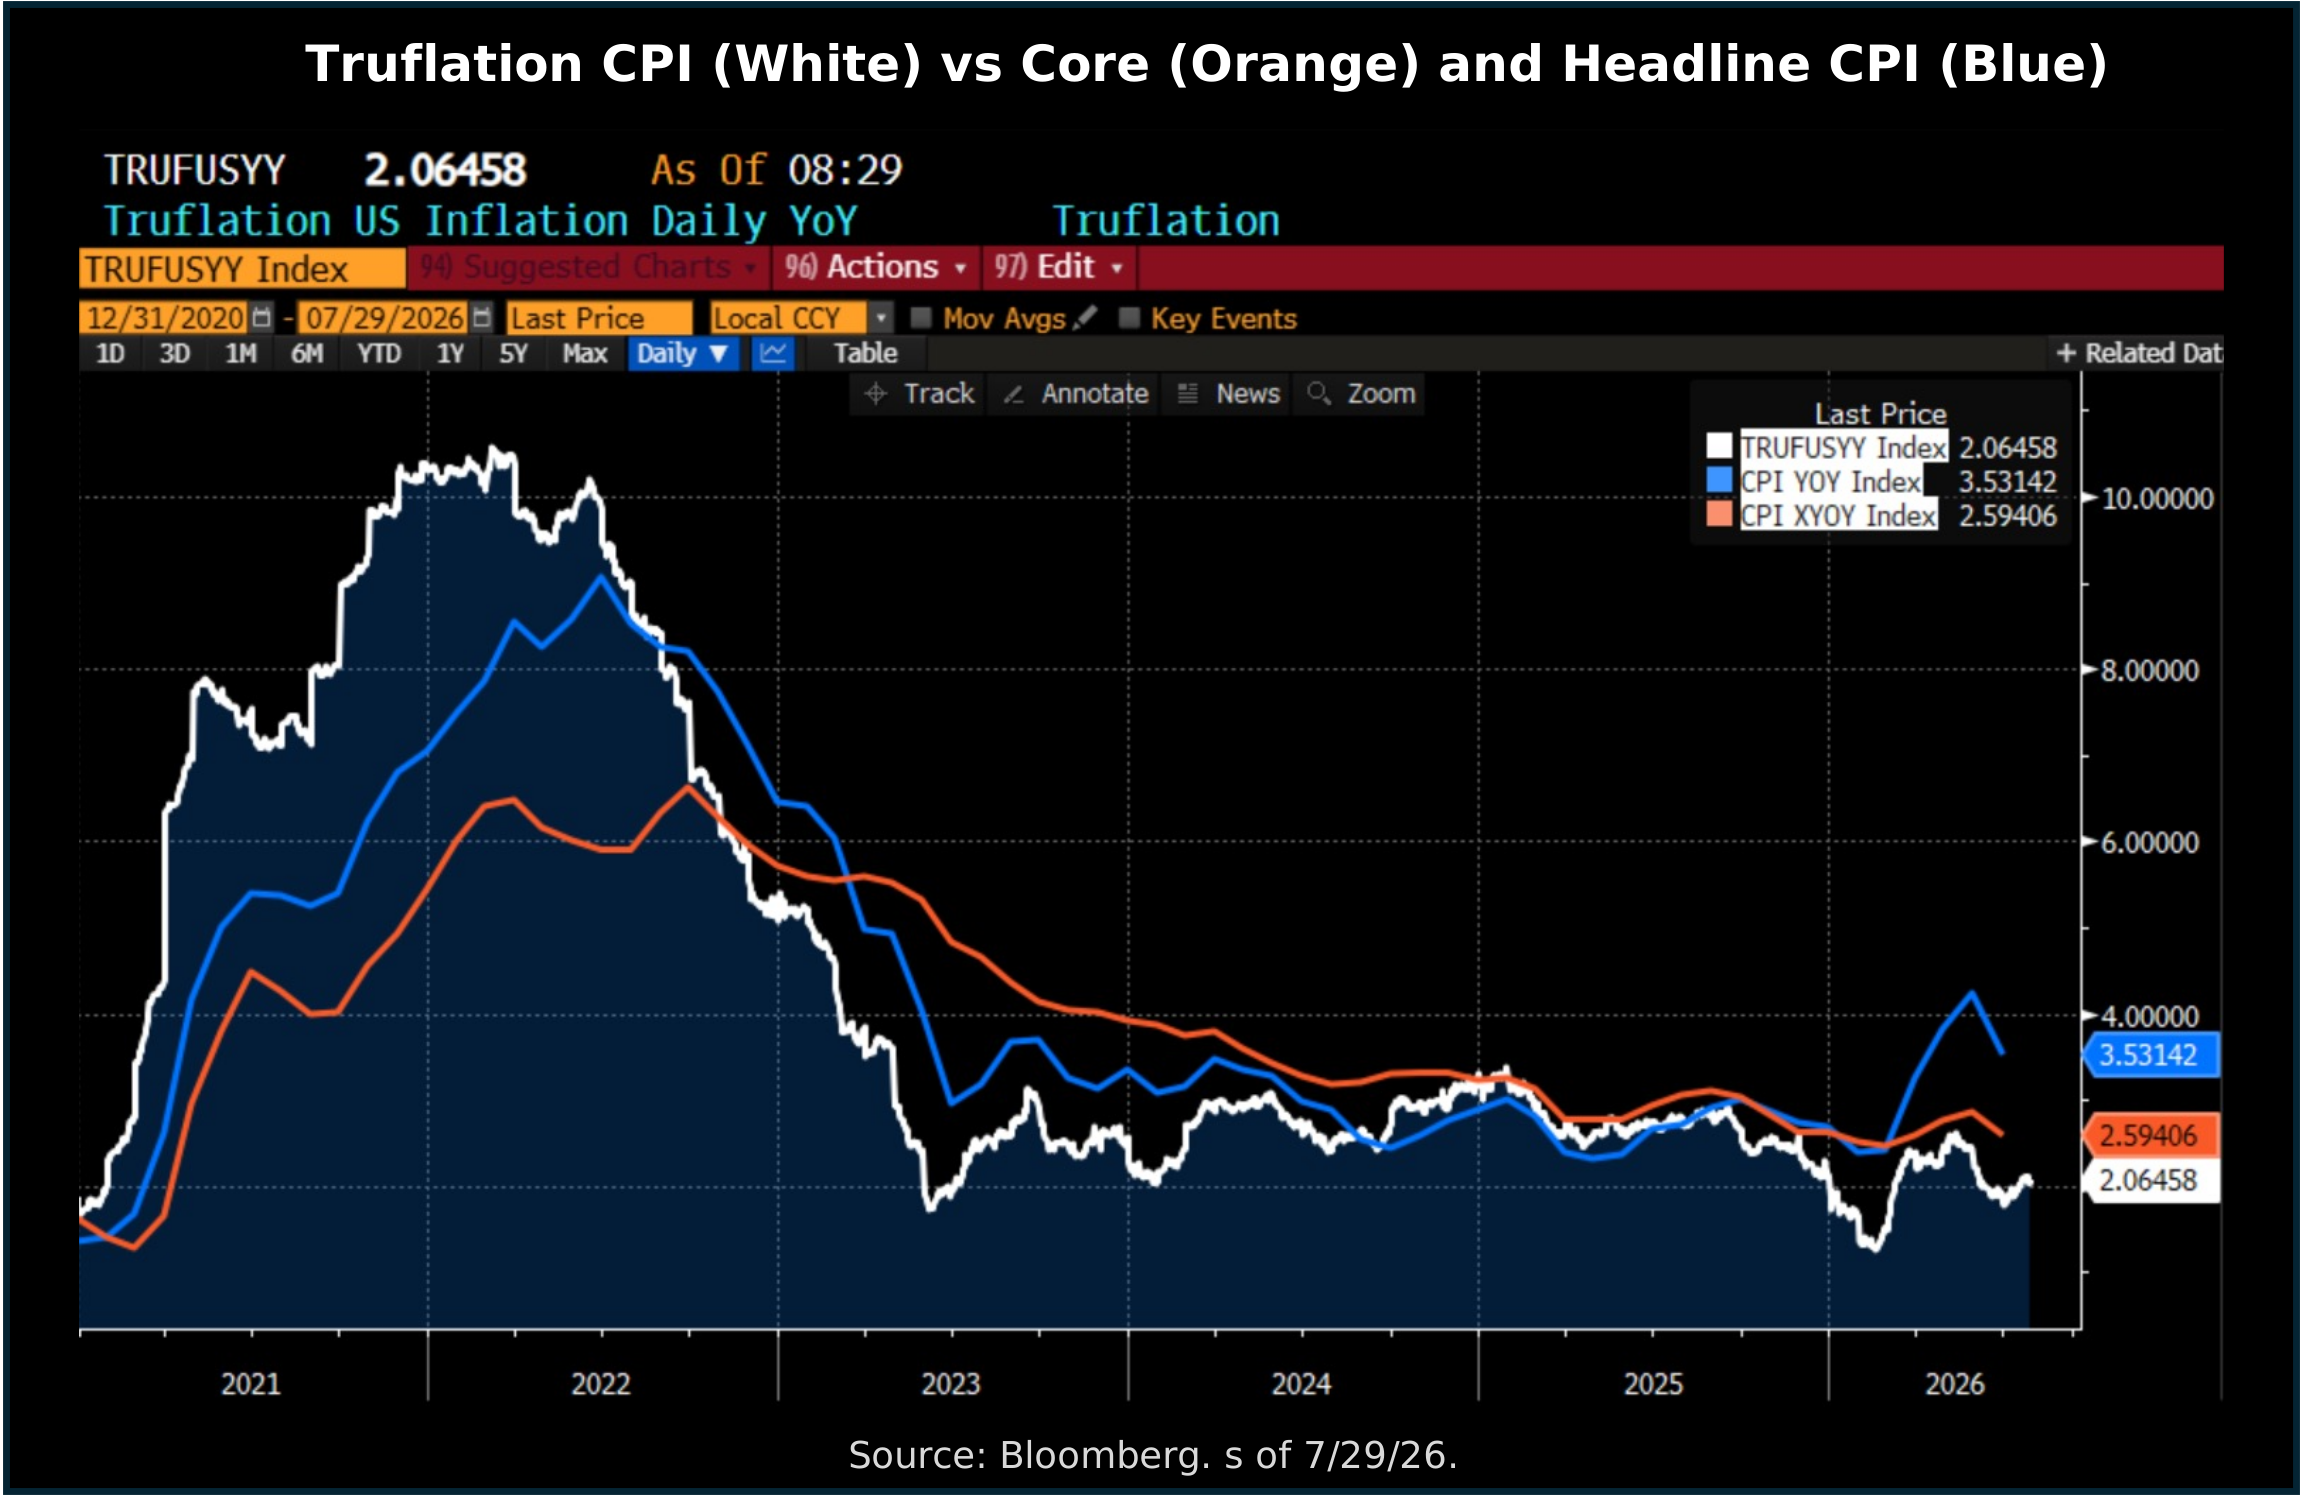
The graphic above shows Truflation CPI (white), Core CPI (orange), and Headline CPI (blue) since the beginning of 2021. The reasons I included the graphic are that Truflation CPI is sitting at 2.06%, close to the Fed’s target, and that Truflation has been a good indicator of where inflation is going. Nothing within Truflation tells us inflation is reaccelerating.
Side note: if one of the Fed’s task forces is focused on better data, do you think Truflation might be in the running?
Warsh Press Conference
Warsh noted the debate (“family fight”) amongst the FOMC participants during the meeting. He laid out 4 key areas:
1. The implications of the previous five years of high inflation
2. The economic shocks of recent years
3. Price increases from these shocks (energy prices as well as memory price increases/ AI capex spend) and whether they indicate broad inflation or not
4. Monetary tools
With Warsh’s tenure as Fed chair just 8.5 weeks, there weren’t a ton of answers given to the above points. Several members of the media voiced frustration with the lack of action by Warsh given his emphasis on “there is no soft inflation target, it’s 2%,” thinking he should have hiked rates today. The market (judged by the long end of the curve) is questioning Warsh’s patience, and we will be interested to see how the next batches of data shake out. If inflation continues to show no progress, Warsh will have to act.
Rate Probabilities – SEPT Looks Live
It would have been a big lift to get the necessary votes for a rate hike today, and with the cool June inflation numbers, upcoming Jackson Hole symposium, two more inflation reports before the September meeting, and a labor market with slightly slowing momentum, it was the easier choice for the committee to extend the pause. This was not surprising, as Warsh has emphasized a moderate pace to policy-making while allowing some time for recently created task forces to report their findings. The three dissents suggest the decision to maintain the current target range hinged on a close vote, and several at the Fed are less inclined to be patient; the stage for a possible rate hike in September appears likely unless the inflation data cooperates.
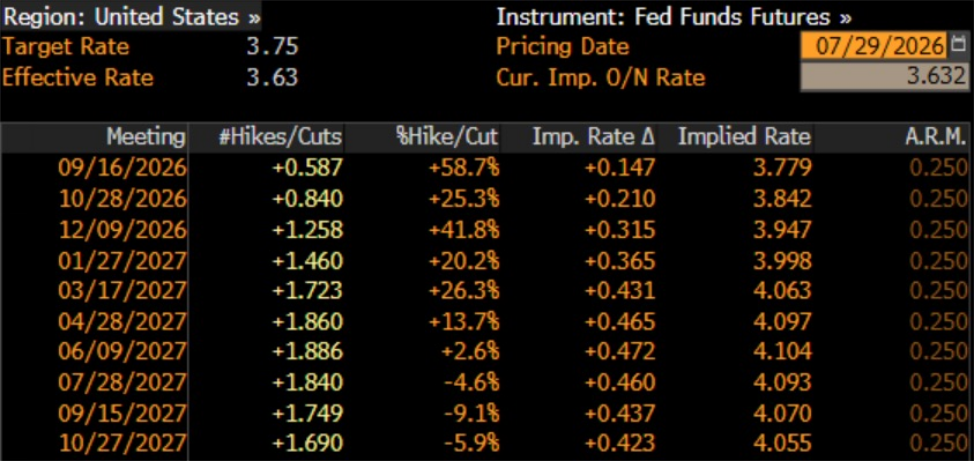 Source: Bloomberg. As of 7/29/26.
Summary
We would note that given the tightening in financial conditions, the market is doing a chunk of the Fed’s work for them. The 10yr at the last Fed meeting was 4.45%, and the 10yr ended today at 4.67%. The 2yr at the last Fed meeting was 4.05% and closed today at 4.26%. Kevin Warsh claimed the lack of Fed forward guidance has allowed this to play out, where a tightening in real and nominal rates has done some of the work for the Fed.
Warsh had a few notable comments (paraphrased):
“Let’s let the market play the ball, not the referee”.
“The market since our last meeting has reacted not to DOTs or Fed speeches but to real data and events”.
“The goal isn’t to surprise markets.”
“When we (the Fed) don’t spoon-feed the market, the market can give us a truer view of how it (broadly) views things”.
There was much angst about what the Fed would do. The bigger problem, as I see it, is people (investors, media, etc.) have gotten so used to the Fed’s overcommunication for so long that they are unprepared to be surprised by anything. Warsh is bringing a new style to his Fed leadership. Investors should expect less Fed jockeying and focus more on listening to the markets. Warsh brings back the refreshing idea of returning pricing to the markets and restoring information to prices (thanks, Dredge). After >60 months of missing the mark (under Powell), the inflation problem isn’t Warsh’s doing; cut the guy some slack (a little patience) and allow a new perspective on Fed leadership a chance.
Next up, Jackson Hole, one month from today.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward looking statements cannot be guaranteed.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2607-33.