
Fed Chair Warsh’s Jackson Hole remarks provided the market with what participants hoped for: A more thorough view from the Fed on the economy and inflation, which appeared to satisfy investors’ concerns. Overall, I’d rate his comments as more hawkishly tilted than the message he delivered at the July FOMC press conference.
He made pretty bold comments regarding the underlying inflation trends, which have not meaningfully improved, and gave a reaction function that if they don’t improve quickly, there is more work to do. This reassured market participants that Warsh and team aren’t going to sit back and continue to wait for the inflation target to be achieved (already at 65 months of failure and counting).
A few other notable comments
-
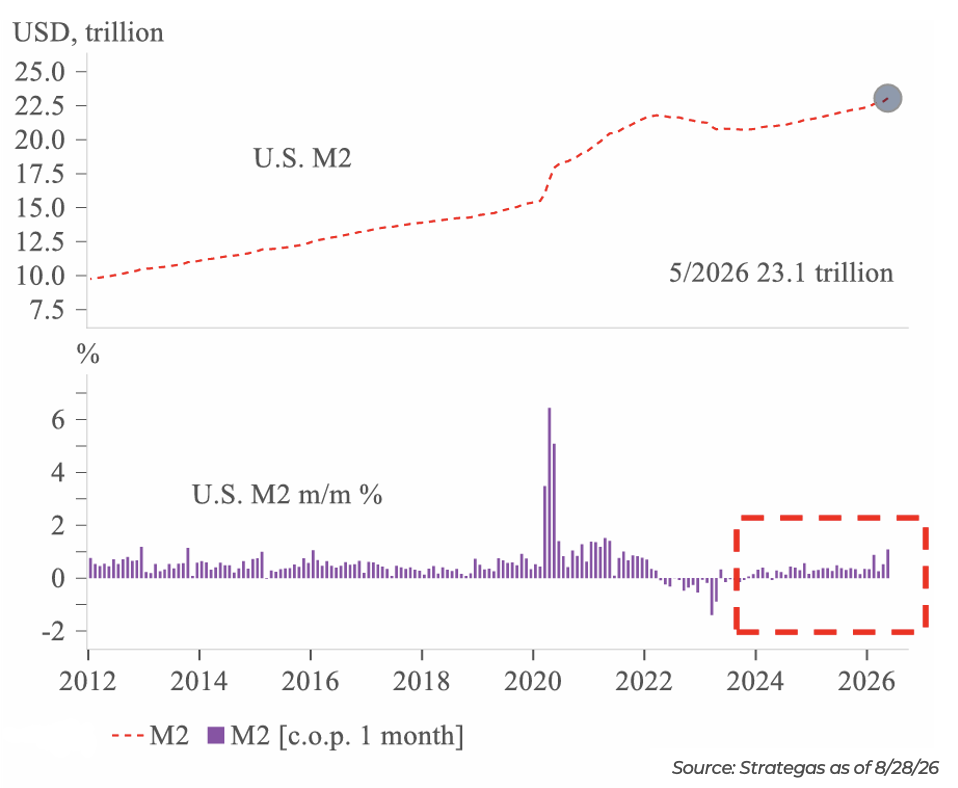
- “Money matters”, so unlike his recent predecessors, it appears like Warsh will pay much more attention to monetary aggregates such as M2 Money Supply growth. Monetary stats have been choppy but of late appear to be turning back up, as shown below.
-
- “I would be hard pressed to describe broad financial conditions as restrictive.” Comments above on M2 confirm.
-
- There was also the hint of a pushback on Treasury Secretary Bessent: “The Fed needs clear market signals, as unfiltered as possible,” including from prices and volumes in Treasuries.
Moving the Inflation Target DEBUNKED!
Warsh made two notable distinctions today, which were undoubtedly lessons learned following his so-so July FOMC performance.
First, after casting doubt on the future of the Fed’s inflation target at the July meeting, he said today:
“There should be no misunderstanding: The Fed’s price-stability objective of 2%, as measured by the personal consumption expenditures (PCE) price index, is a firm, fixed target.”
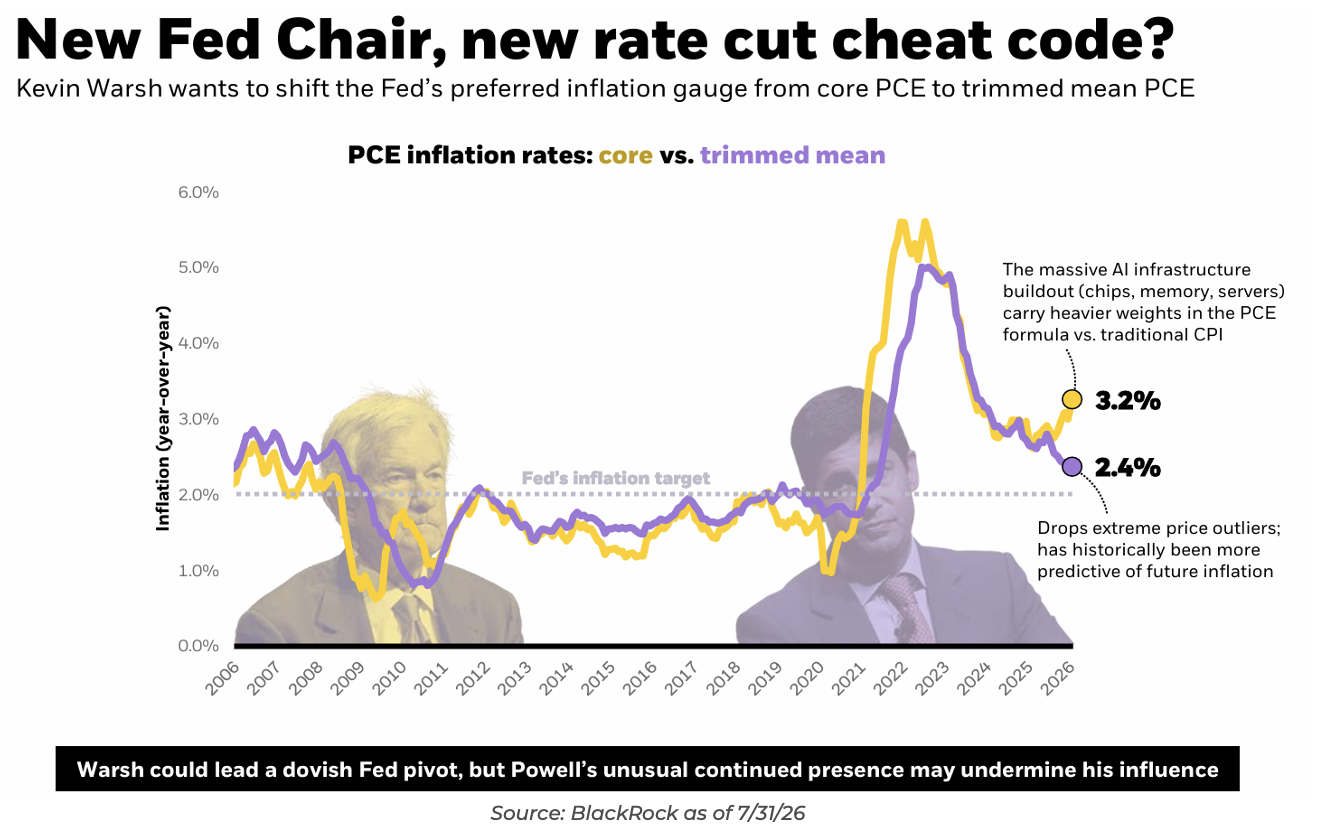
Many market commentators have quipped that Warsh would abandon PCE for some type of trimmed mean, which he clearly shot down today. The markets hate a moving target, and clarifying the benchmark here creates a clear crosshair for the market to focus on.
Second, after equivocating on what tool the Fed should rely on to achieve its objective, he said,
“Short-term interest rates are the predominant tool to achieve the dual mandate.”
Many considered Warsh more likely to use the balance sheet reduction as the key tool to tighten policy rather than rates, while that is a tool he made clear is actually not THE tool.
July PCE
The last of July inflation numbers, the Fed’s preferred measure, arrived on Wednesday morning via the Personal Income and Spending report.
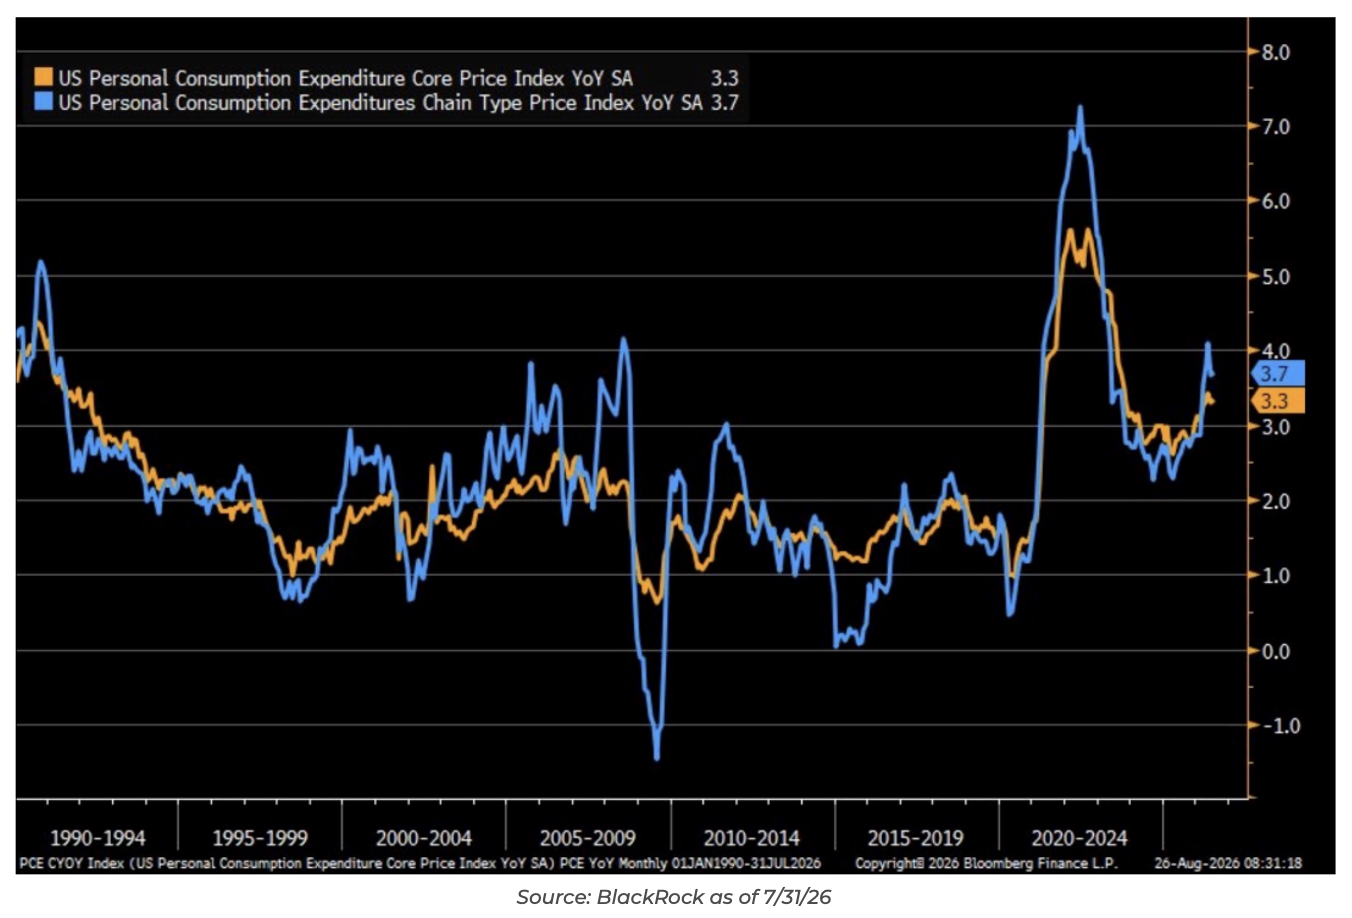
Core PCE rose 0.2% as expected, higher than the 0.1% June reading. YoY core PCE rose 3.3%, also matching expectations, and June’s result. Overall PCE increased 0.2%, above the 0.1% expectation and the -0.1% June result, as gas prices resumed their climb in July as the Iranian ceasefire dissolved.
The YoY rate remained at 3.7% vs. 3.6% expected. We’re well off the 4.1% level we hit back in April as gas prices hit their cycle high, but still well above levels consistent with the Fed’s target of 2%.
The core PCE rate, while matching expectations, was higher than the core CPI YoY rate of 2.5%, and that will be something the Fed’s recently convened data measurement task force will no doubt be looking at.
A key factor influencing CPI lower than PCE is the higher weight on housing (the largest single item in CPI), and with that component in a disinflationary phase, it’s helping push CPI (notably) below PCE.
The Month Ahead
September is a live meeting with the market now pricing slightly over a 50% chance of a hike (sliding up from the mid-30s). This feels more in line with what we’ve heard from the growing hawkish chorus of other Fed officials, as well as considering the three July dissents. We still think a large factor in determining that meeting’s outcome will be the August employment and CPI reports; markets will be watching closely to drive the debate in one direction or the other.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward looking statements cannot be guaranteed.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2608-35.