
Our team looks at a lot of research throughout the day. This week’s charts follow a bond market repricing risk across the curve, from a global yield selloff and a record refinancing calendar to real yields back near pre-financial-crisis levels, alongside an AI buildout increasingly carrying both growth and market returns as earnings estimates keep climbing. History suggests equities can absorb the higher-rate backdrop since earnings, not multiples, are doing the driving, though the market’s calm surface is masking more stress underneath than it looks.
Have a great weekend!
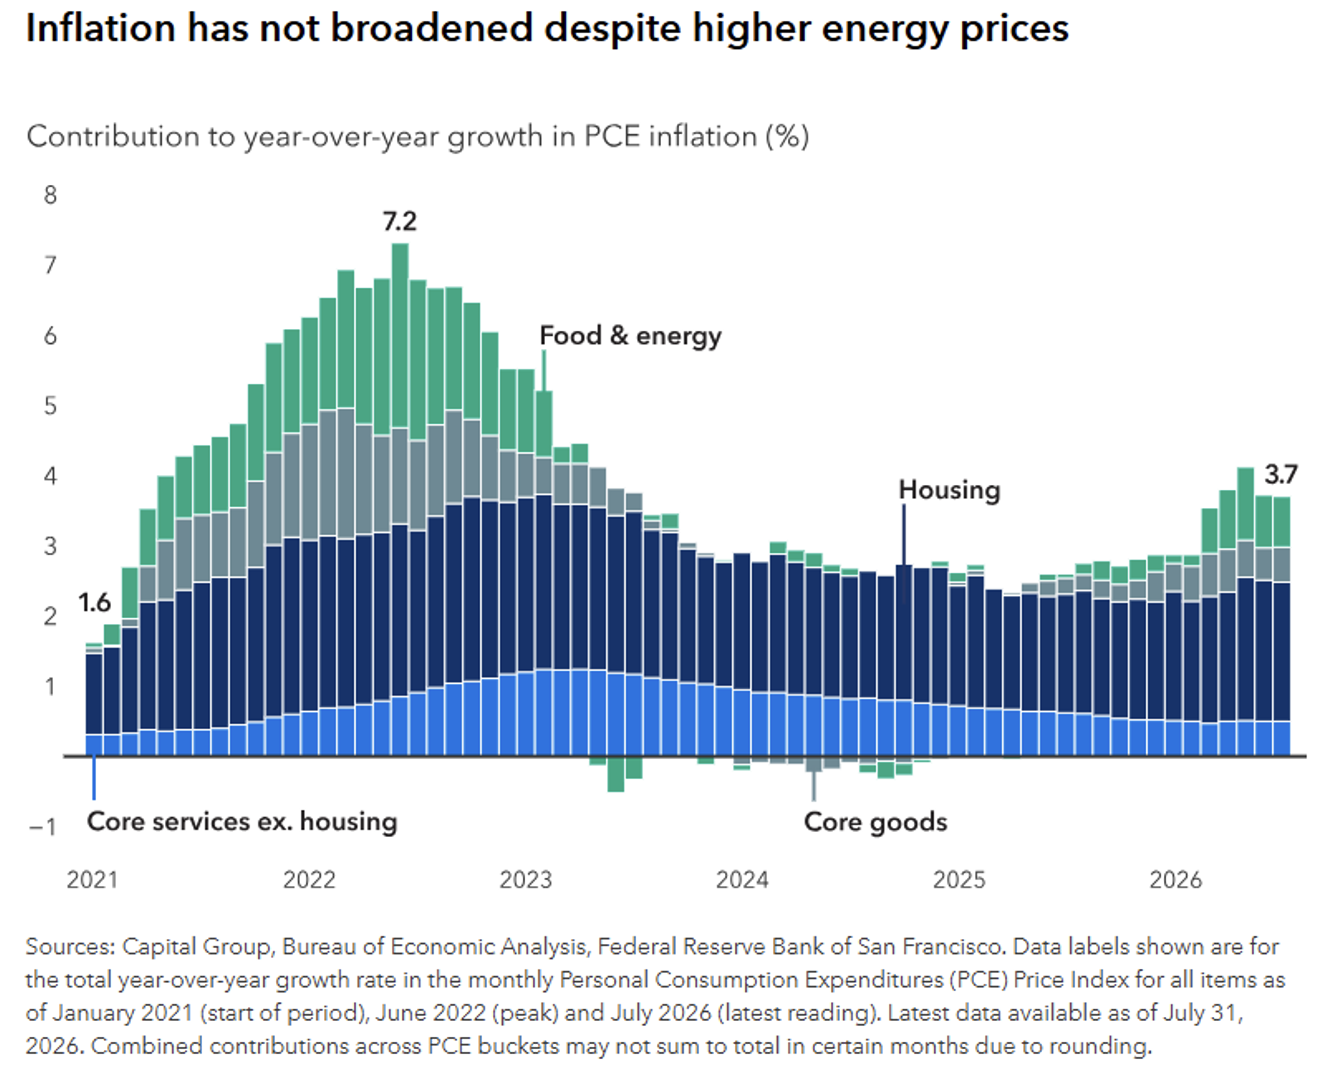
Jake: Headline PCE inflation is back up to 3.7%, but the mix looks nothing like 2022. Food and energy are doing the pushing this time, not the broad-based repricing that took it to 7.2%.
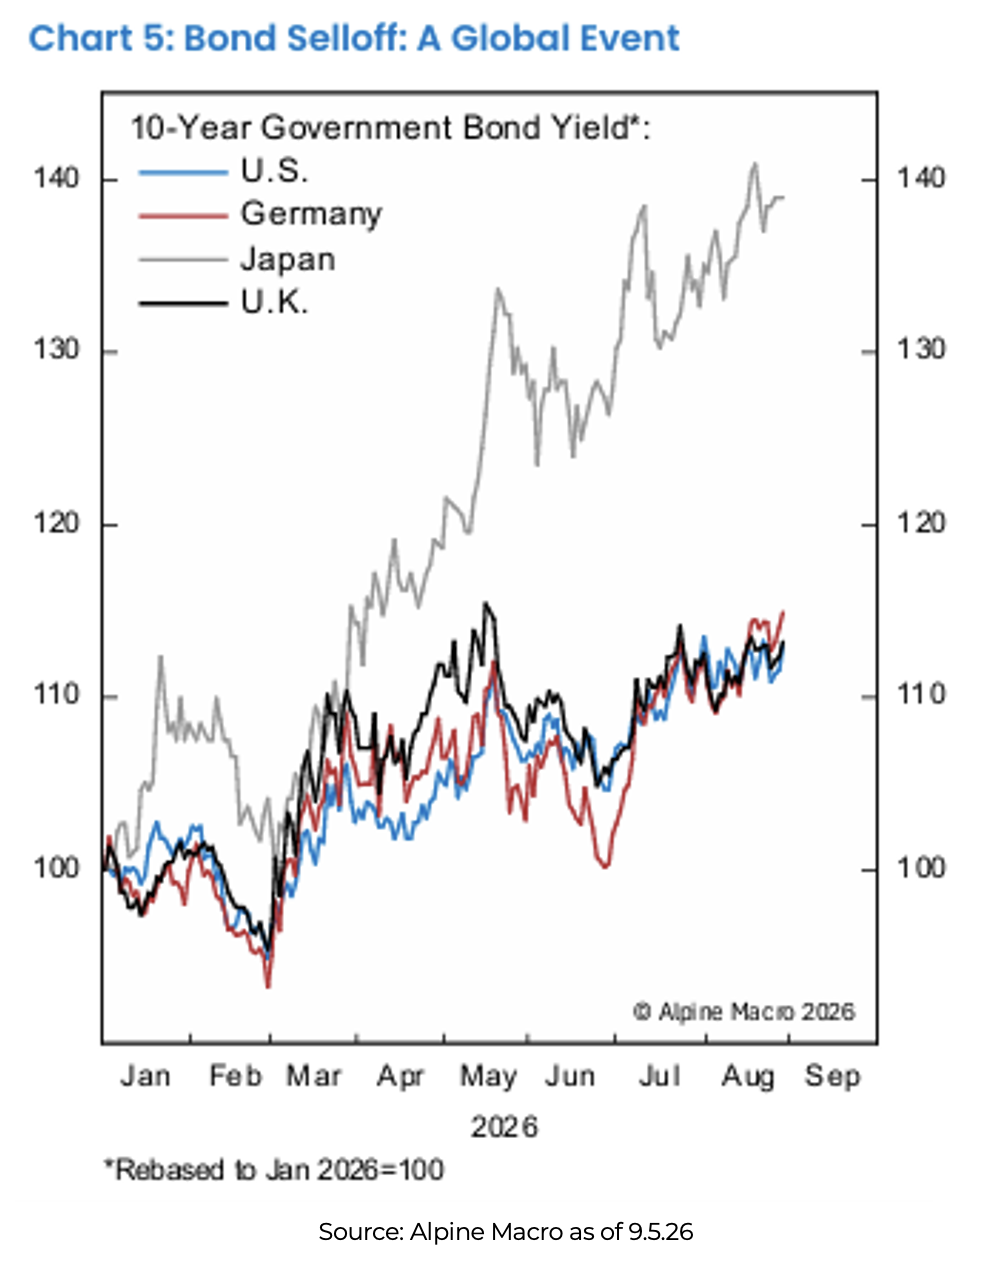
John Luke: Meanwhile, the bond selloff is not just a US story. Ten-year yields are up materially in the US, Germany, and the UK since January, and Japan’s is up nearly 40%.
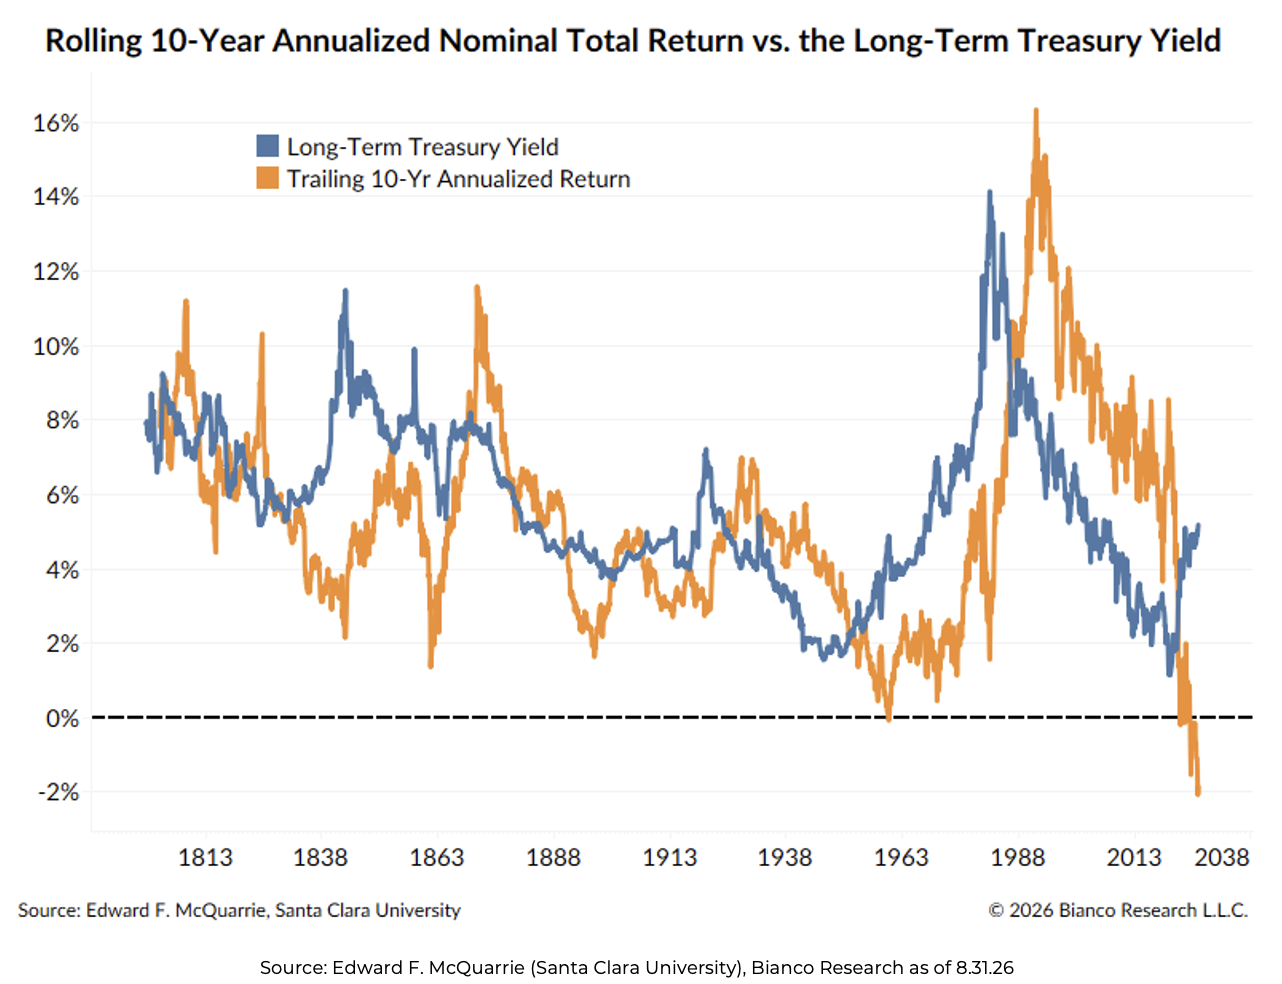
Beckham: The uptick in borrowing costs has created a rare instance of negative trailing 10-year returns on long Treasuries. Going back to 1813, that has only happened a handful of times, and it just happened again.
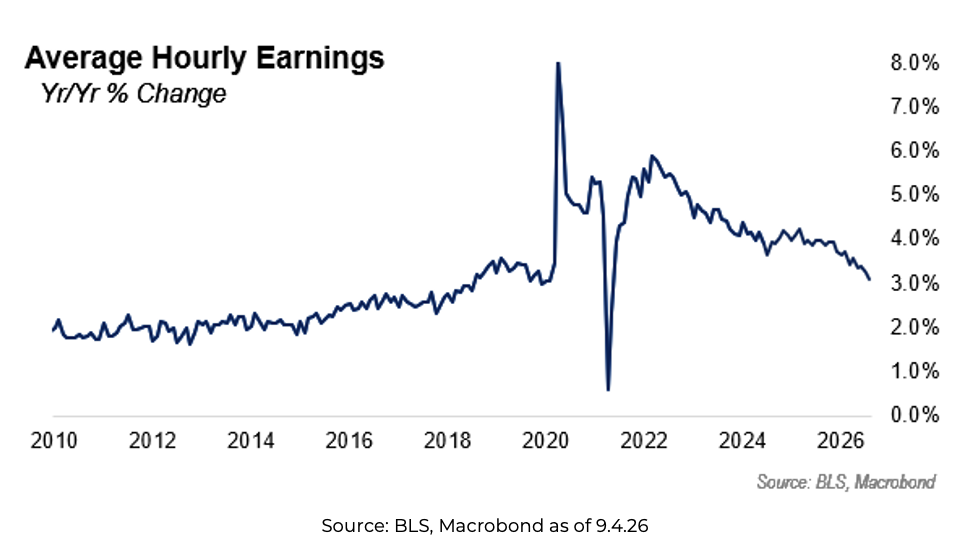
Dave: That is happening even as wage growth continues to cool. Average hourly earnings are back near 3% year-over-year, close to its pre-pandemic norm and still enough to keep consumers spending.
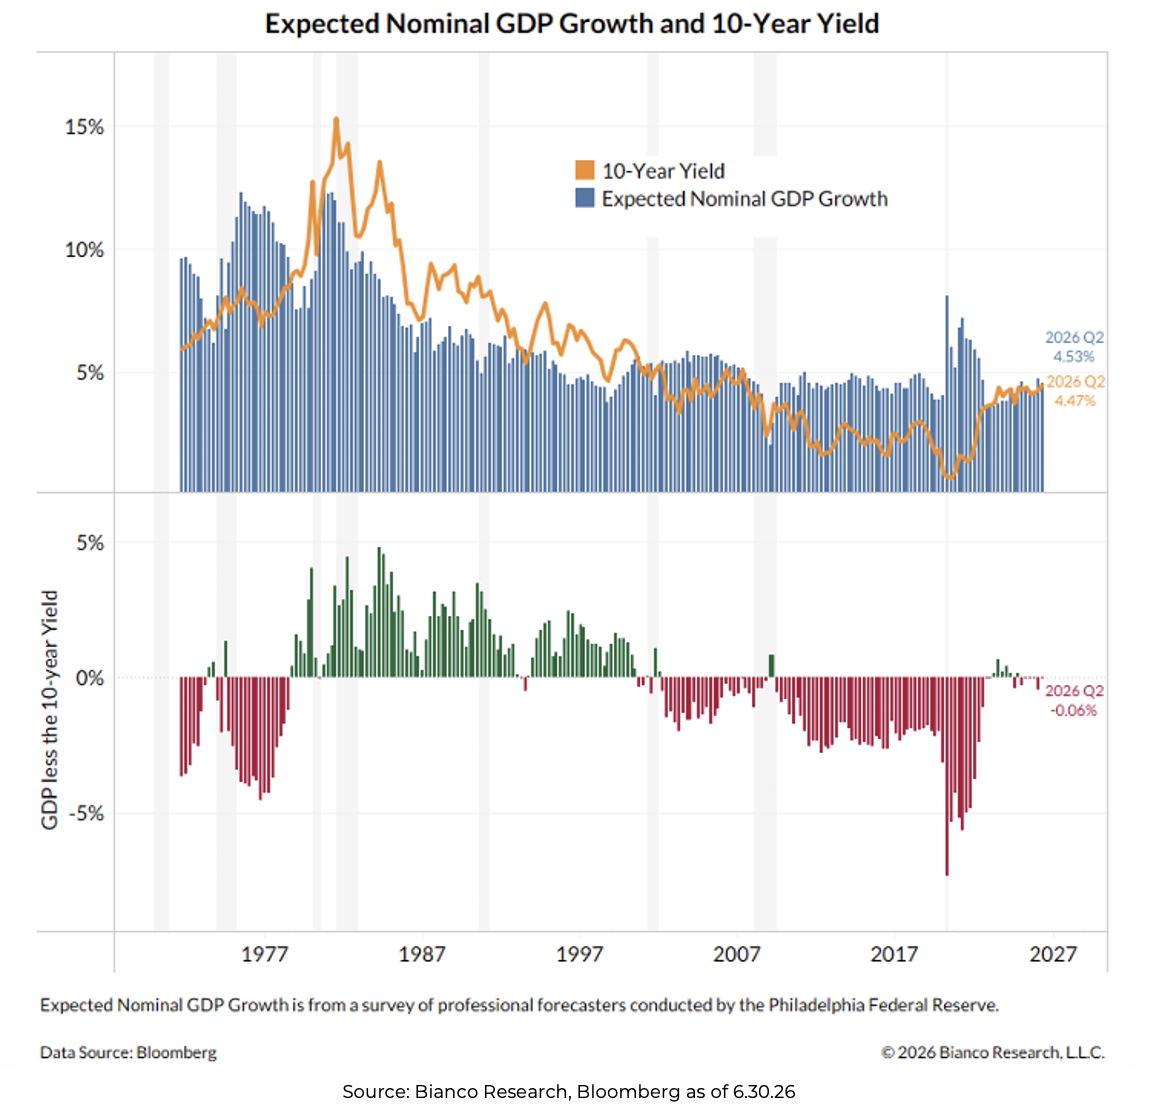
John Fox: The math behind current yields is more straightforward. Expected nominal GDP growth and the 10-year yield are now within six basis points of each other, about as close as they have been in years.
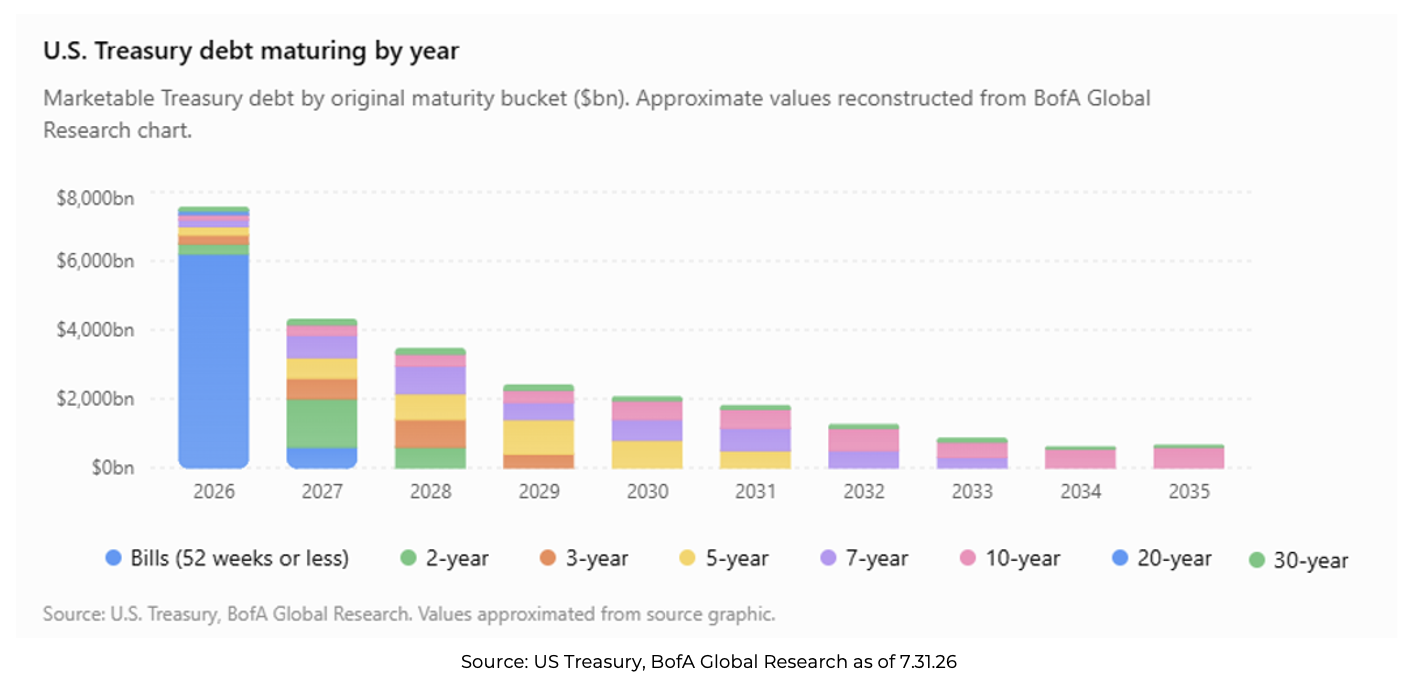
Derek: That gap has narrowed as the refinancing calendar gets heavier. Nearly $7.6 trillion of Treasury debt matures in 2026 alone, most of it in short-dated bills that will need to be rolled at market rates.
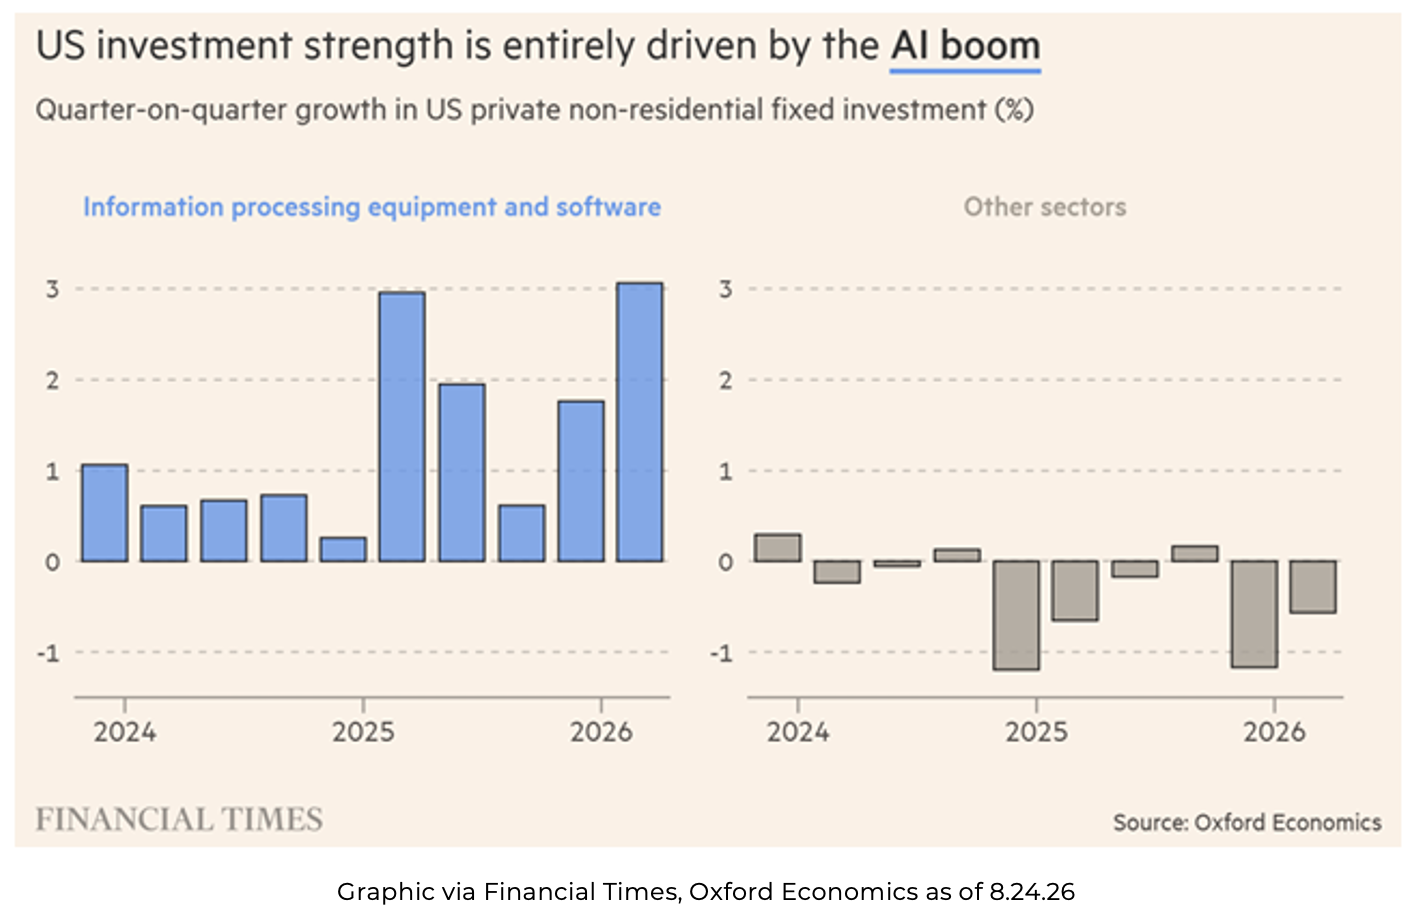
Brad: Despite higher rates and any potential crowding-out effect, the AI buildout keeps running hot. Investment in information processing equipment and software is growing more than 3% a quarter while every other category of private investment is shrinking.
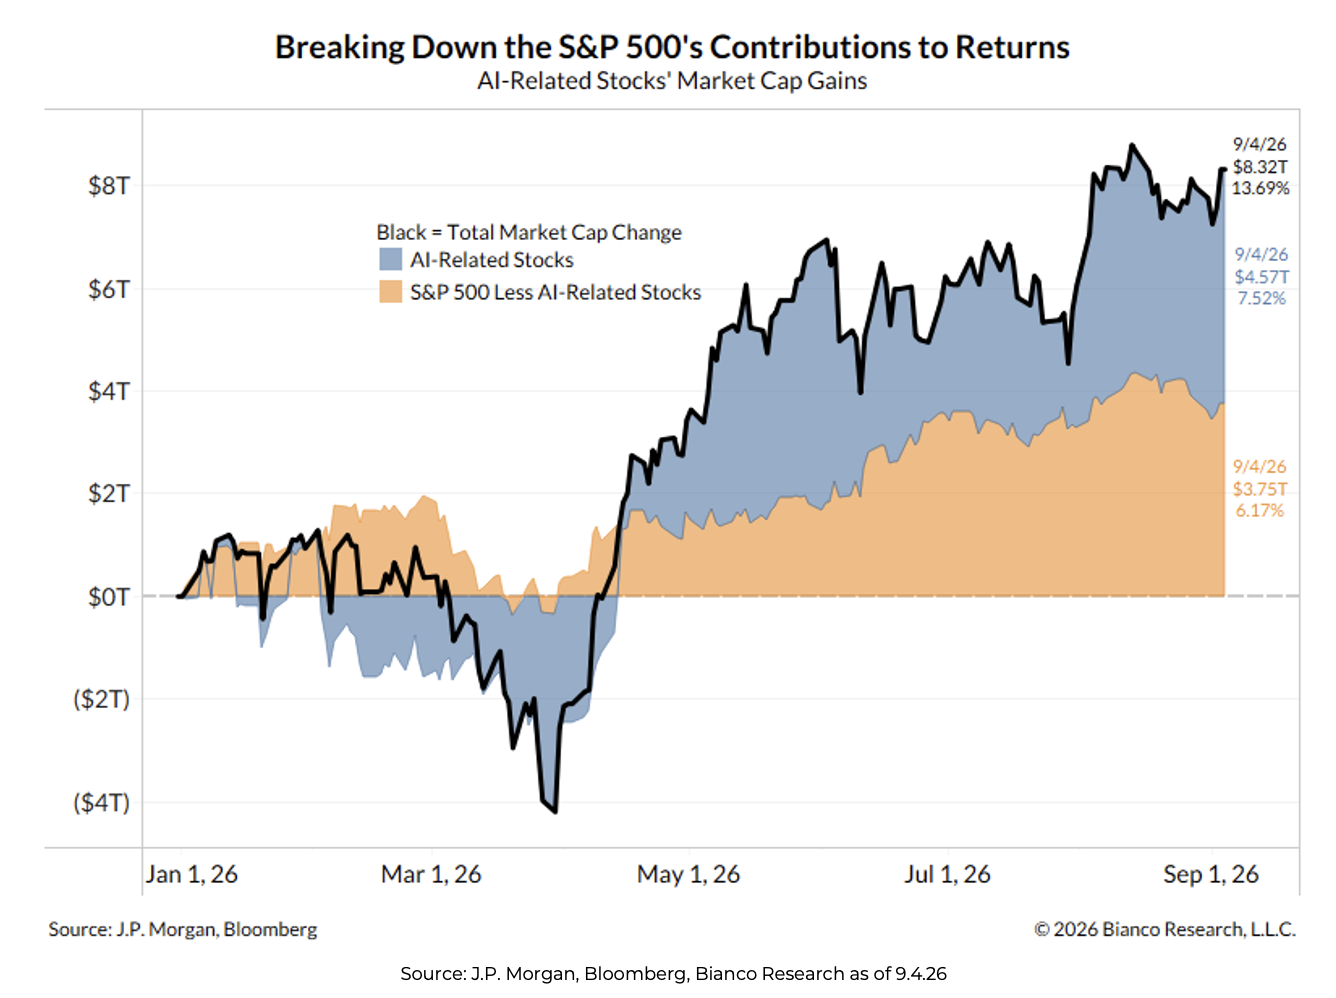
Mark: The market is pricing that buildout accordingly. AI-related stocks account for $4.57 trillion of the S&P 500’s $8.32 trillion market cap gain this year, more than the rest of the index combined.
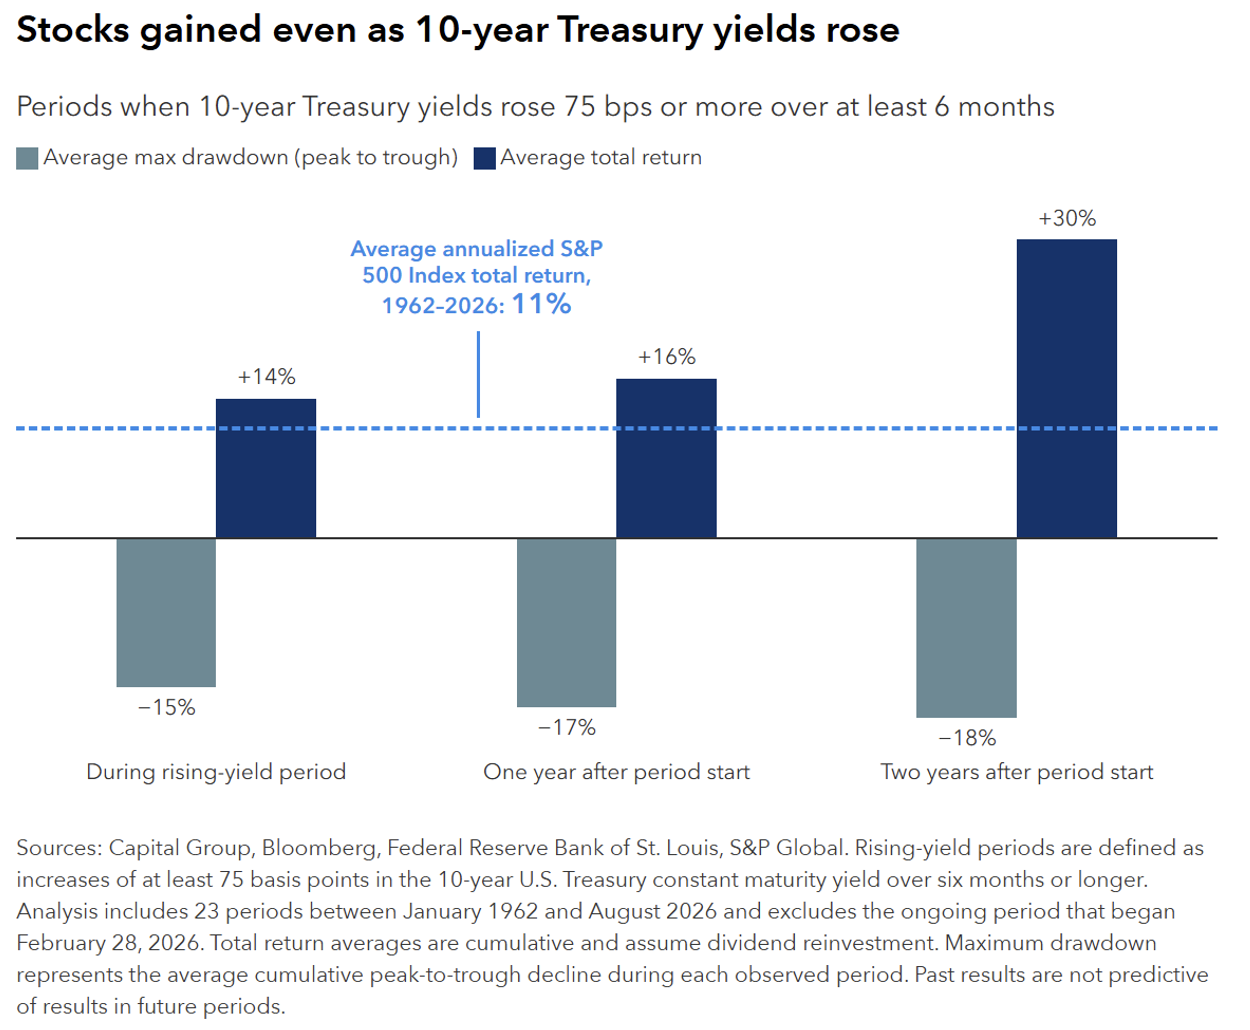
JD: A rise in rates hasn’t been bad for equities the past year, and going forward there is reason to believe it won’t as well. Across the 23 times since 1962 that the 10-year rose 75 basis points or more, the S&P has averaged a 30% total return two years later.
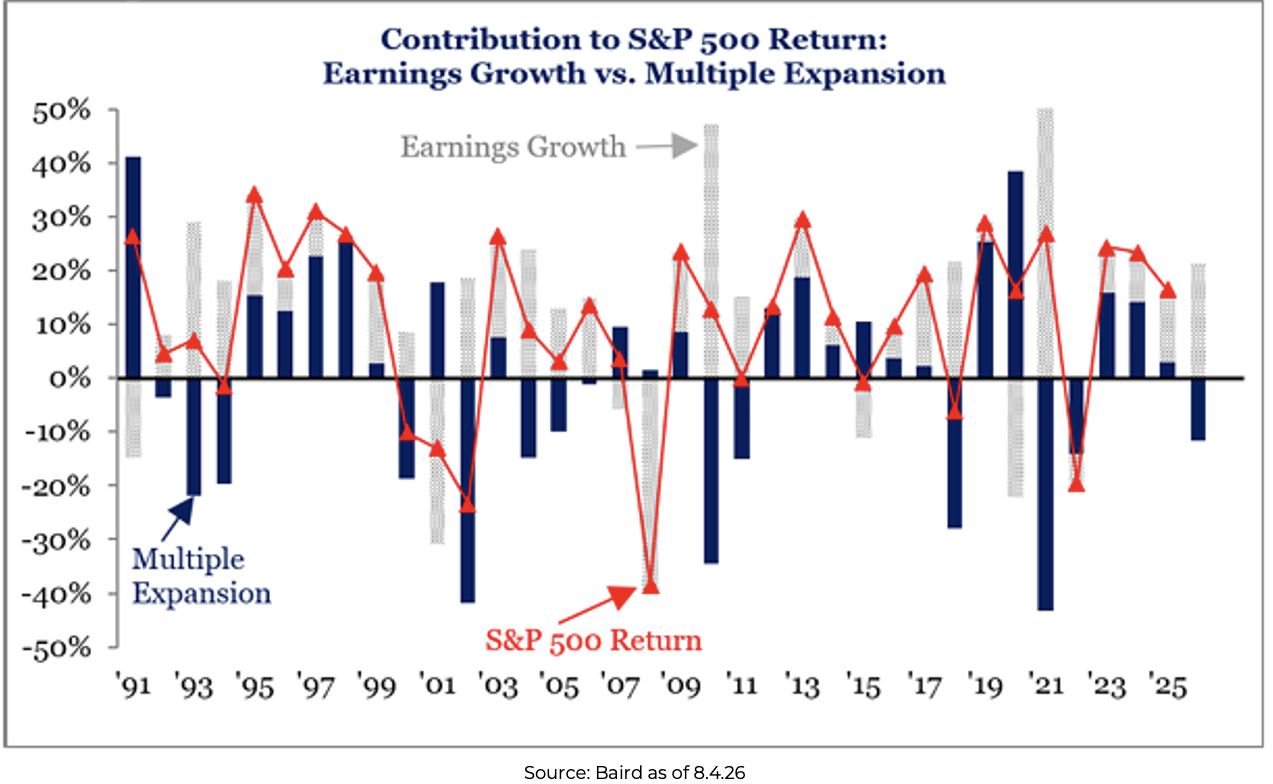
Brett: Part of the reason stocks can absorb that is that earnings, not multiples, are doing the driving again. Multiple expansion has been more of a drag than a tailwind on returns in recent years.
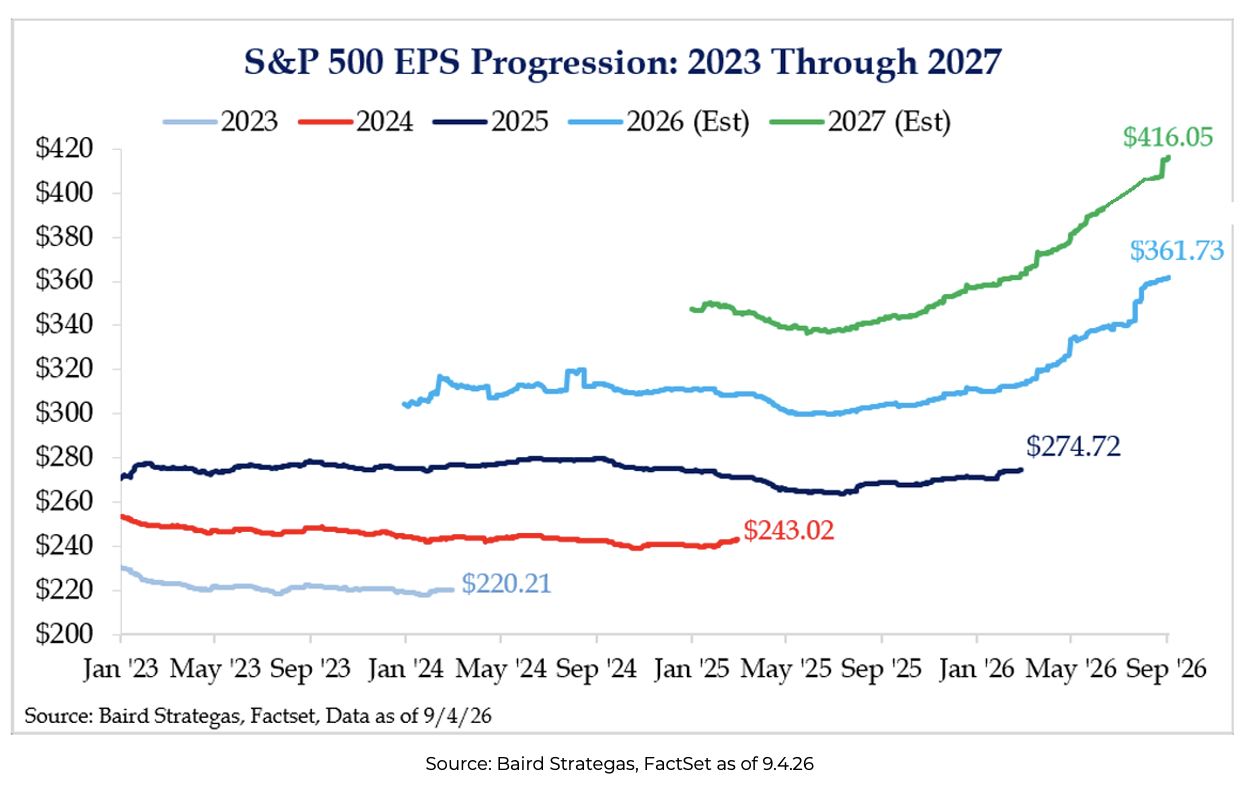
John: And those estimates keep marching higher instead of fading the way they usually do. Consensus now has S&P 500 earnings at $361.73 for 2026, a 31.7% jump from 2025, with 2027 penciled in at $416.05 for another 15%.
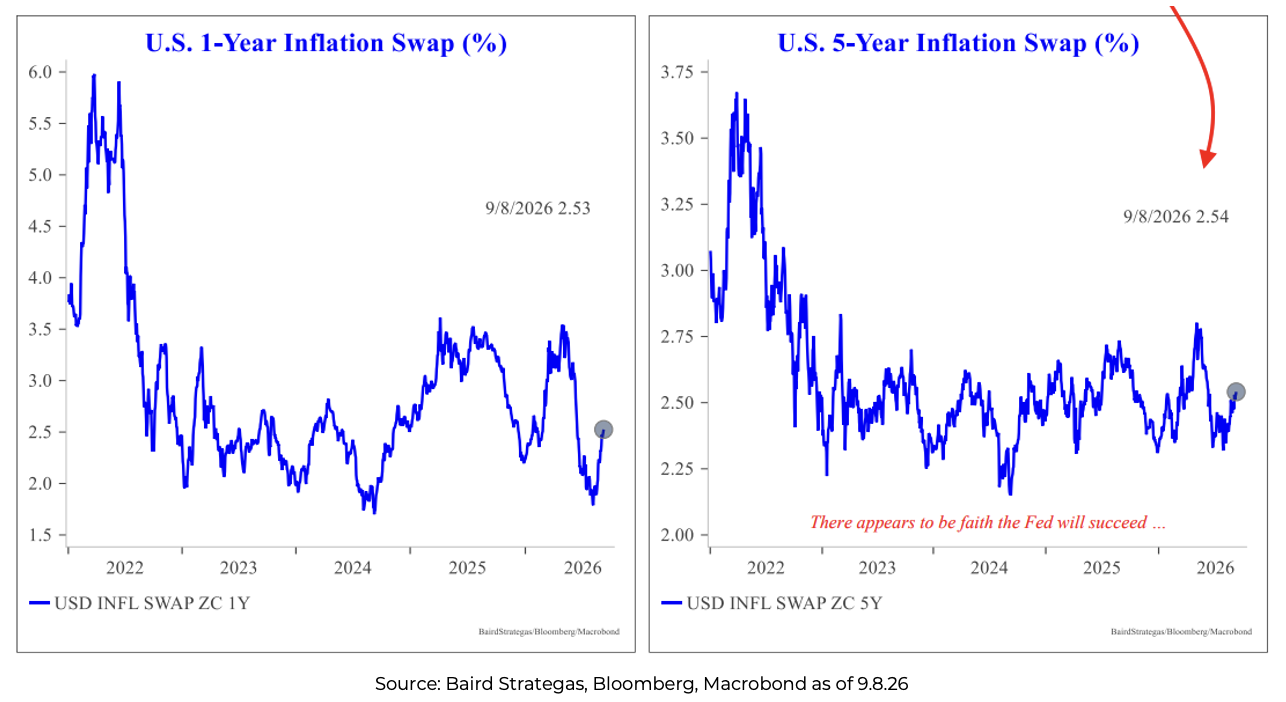
Mike: Markets seem to believe the Fed can still land this, as interest rates have not been a function of forward expectations for inflation. Both the 1-year and 5-year inflation swaps sit right around 2.5%, down sharply from their 2022 highs.
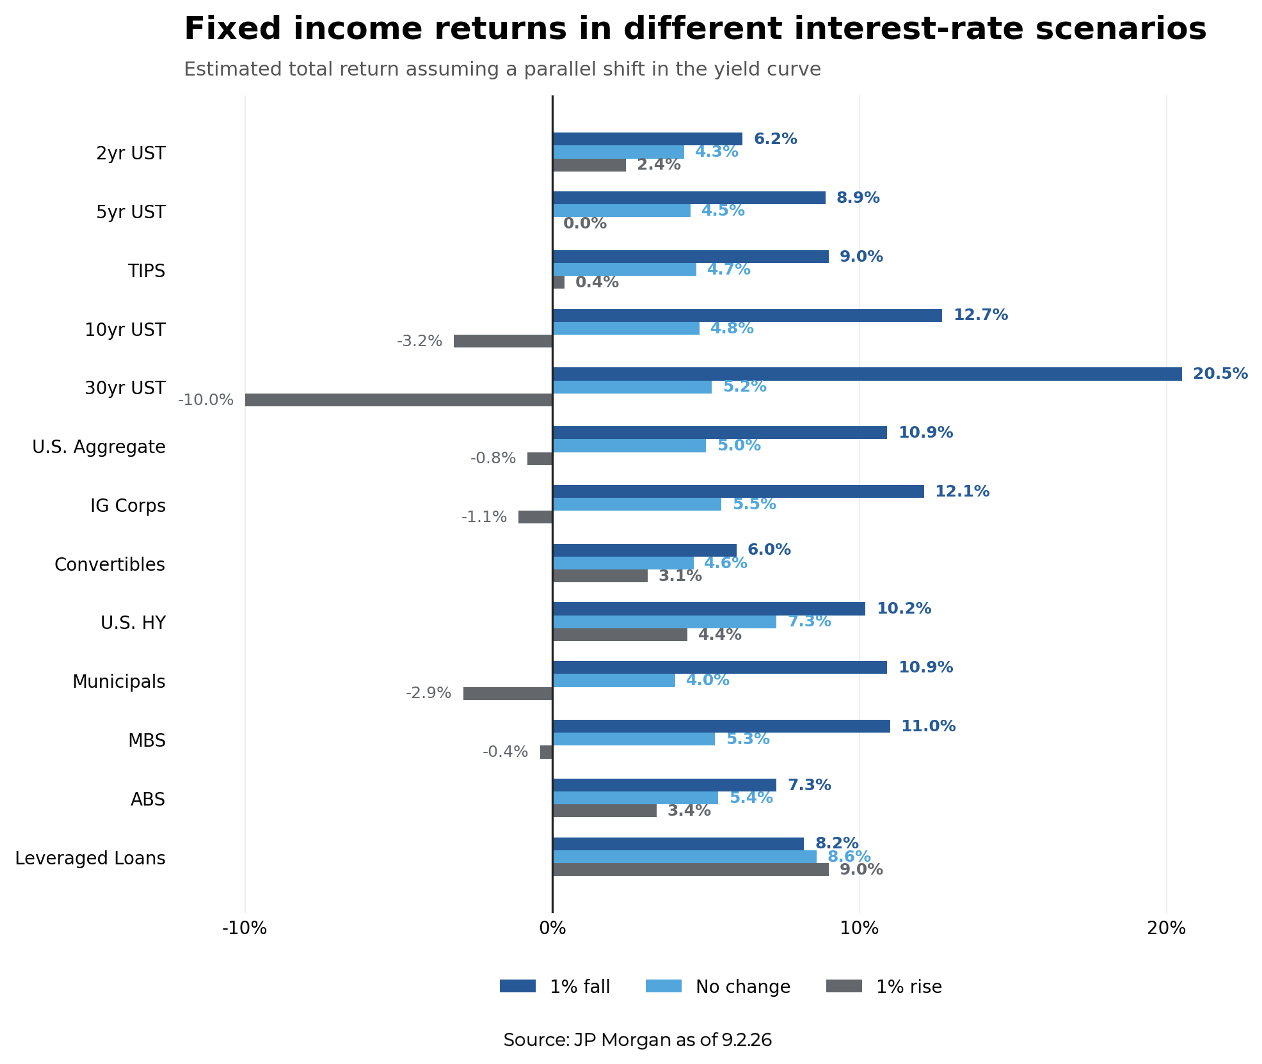
Joseph: Fixed income provides a wide range in forward returns given various assumptions. Where to park your money is a challenging question depending on your view.
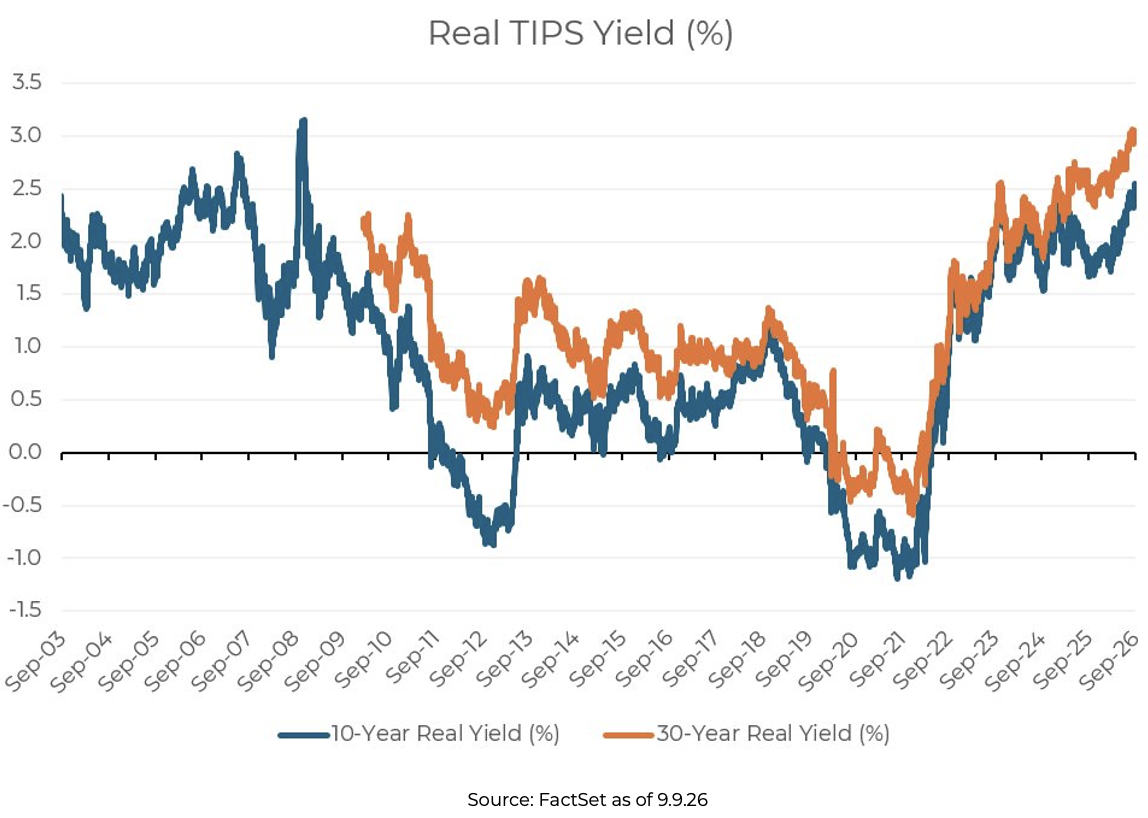
Brian: Zooming out helps put current yields in context. The 10-year TIPS yield has climbed from a low of -1.1% in 2021 to about 2.5% today, a level last seen consistently before the financial crisis.
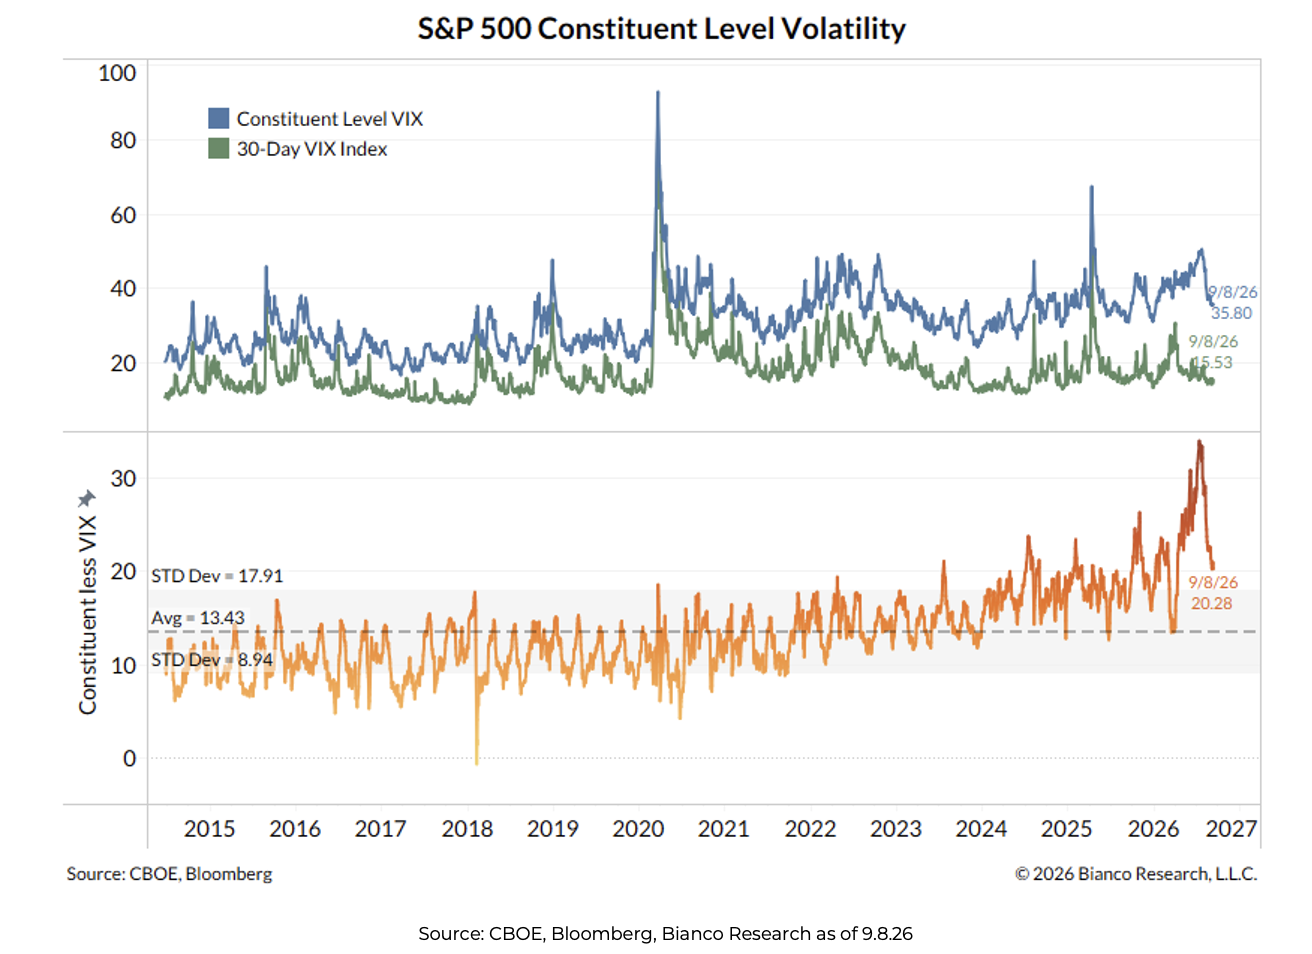
Ten: The calm the VIX index has exhibited much of the last month is masking a lot of stress underneath. Constituent-level volatility sat near 36 against a 30-day VIX near 15, well above its historical range.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2609-16.
