
Have a great weekend!
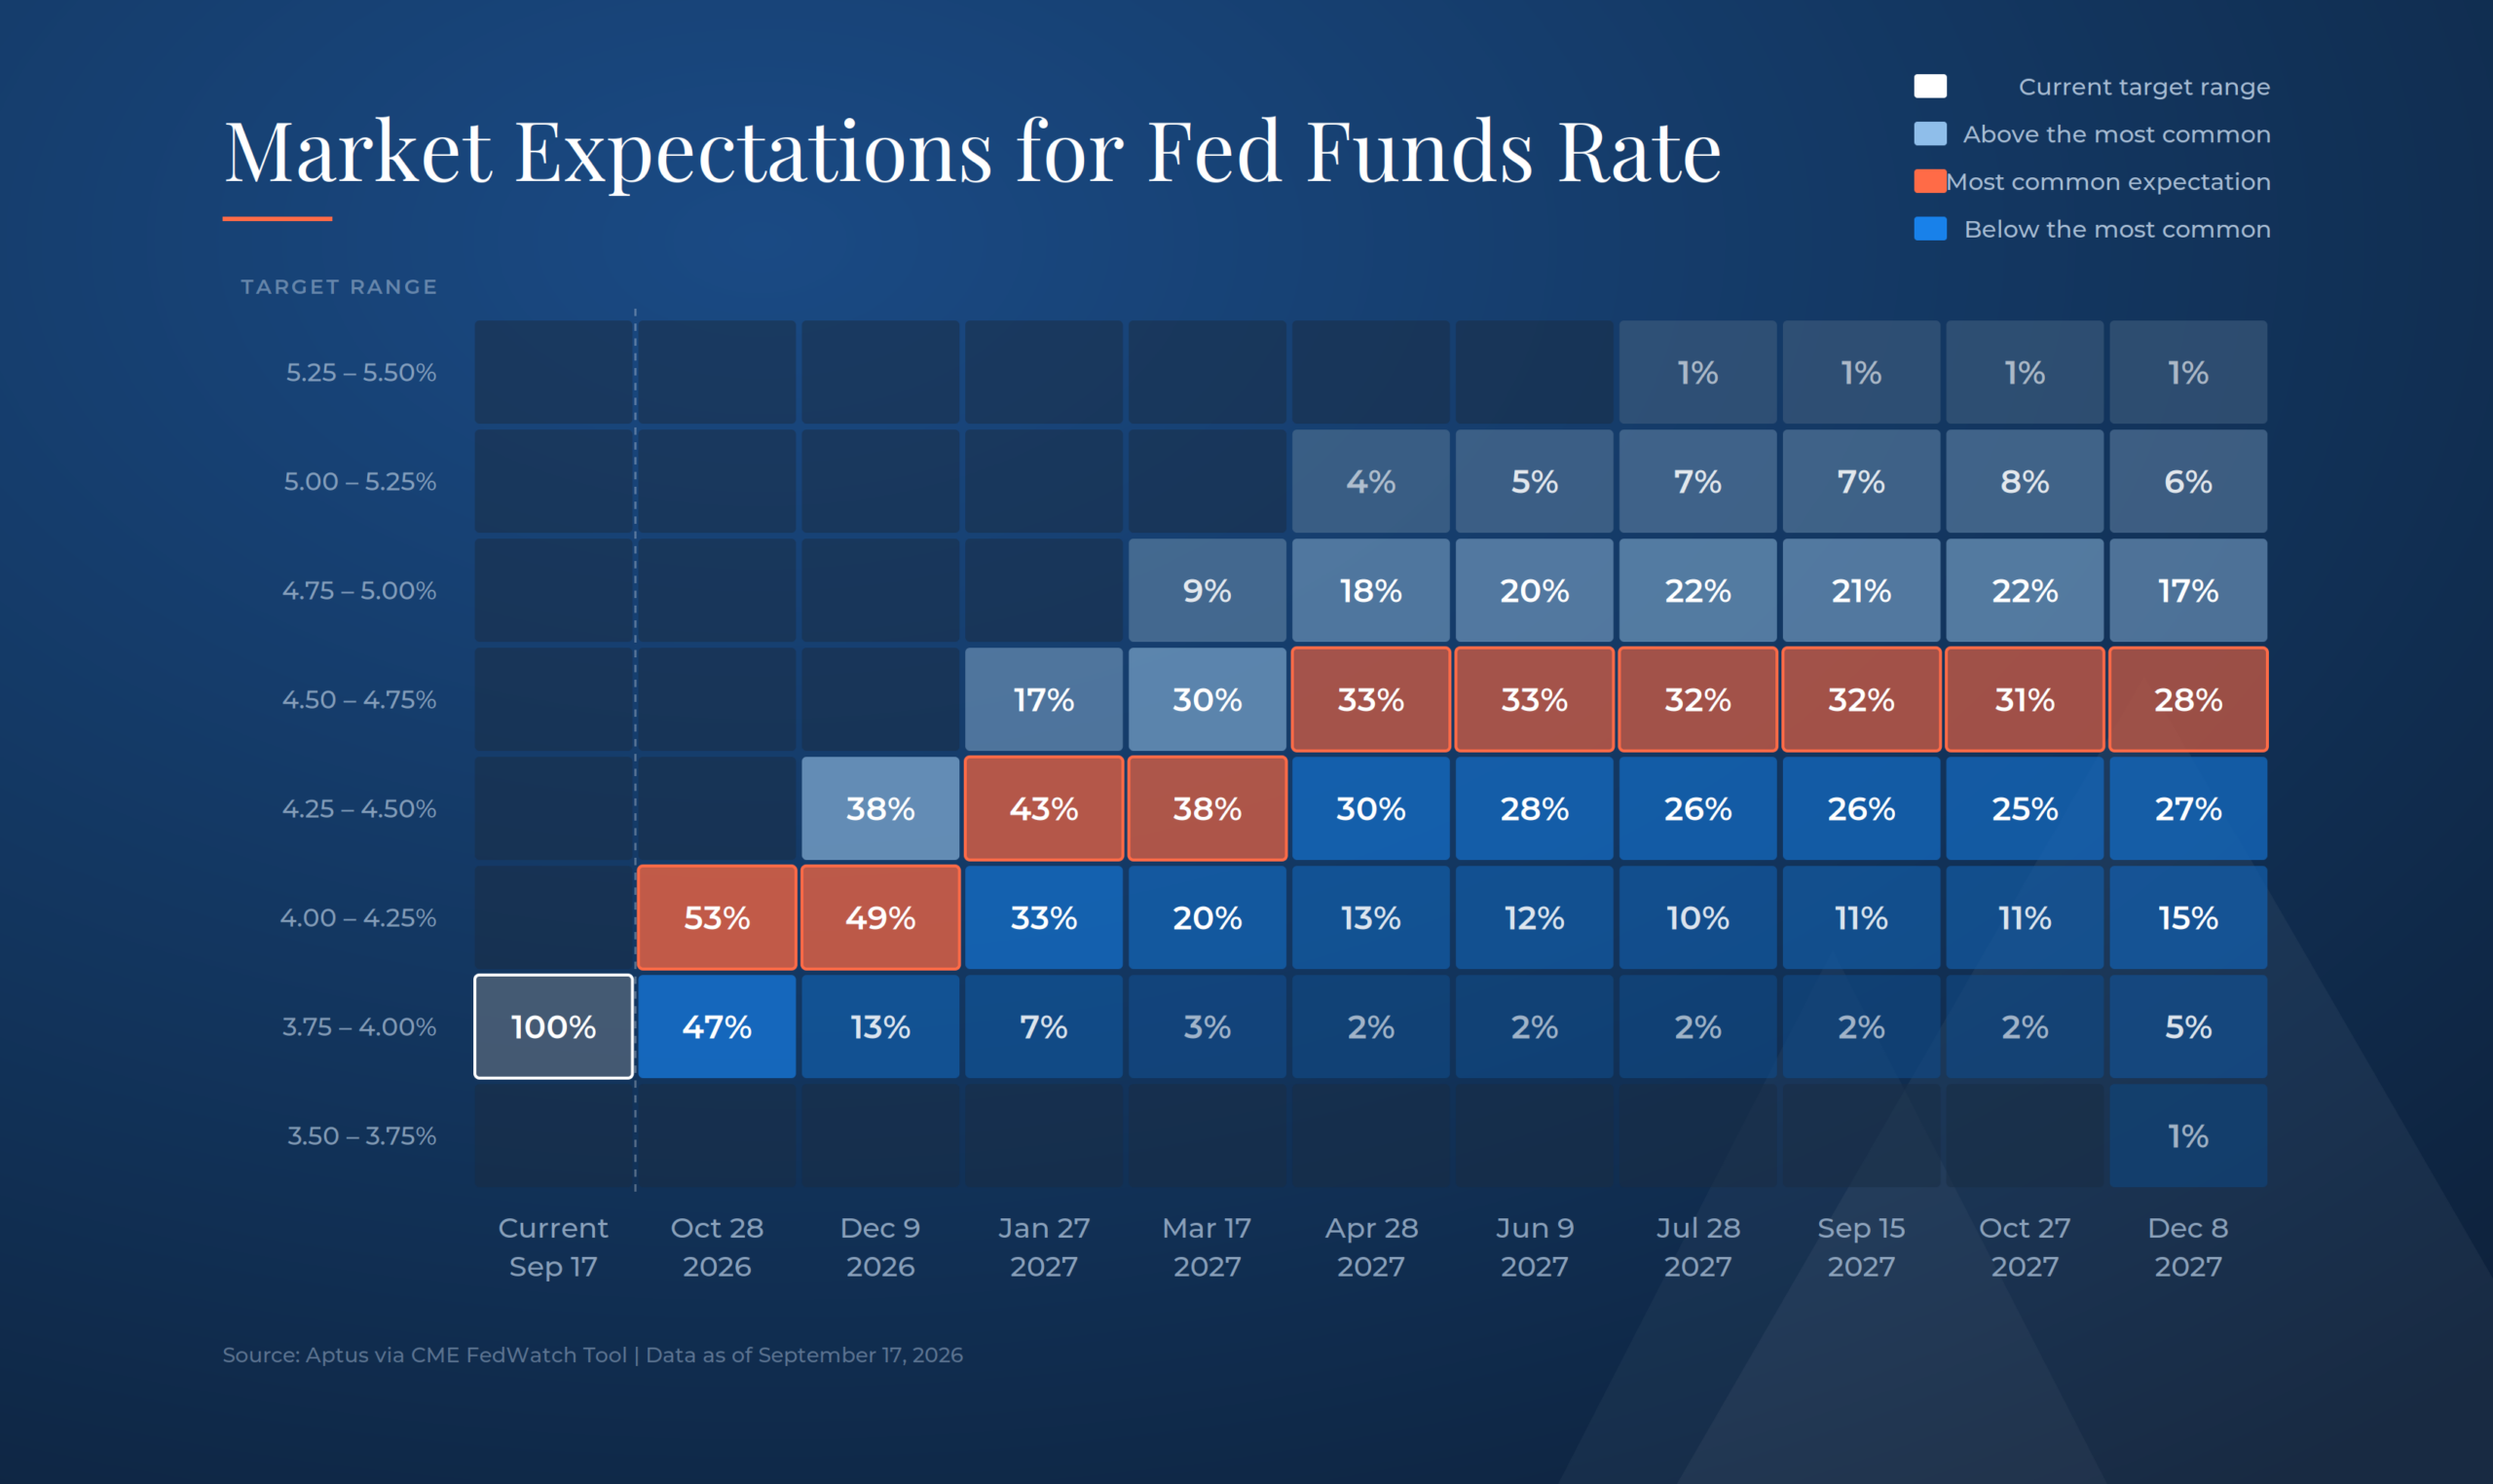
Ten: Markets had all but priced the quarter-point hike going in, the Fed followed through, and at least one more is now the base case by year-end.
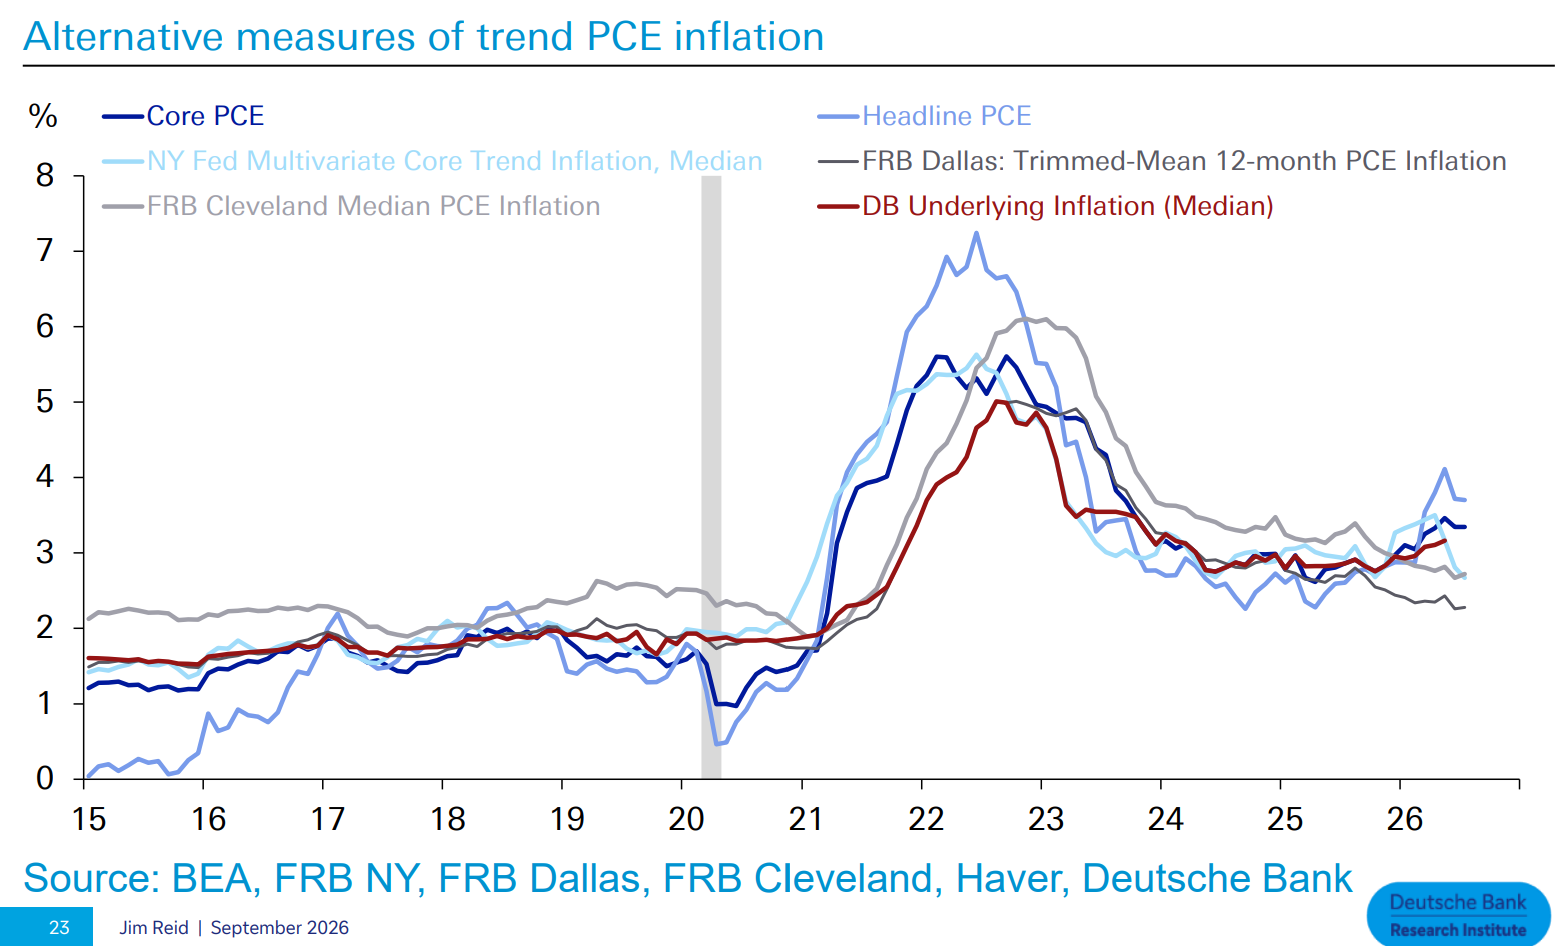
Brad: Inflation is the complicating factor, with every measure stable to higher over the past few months
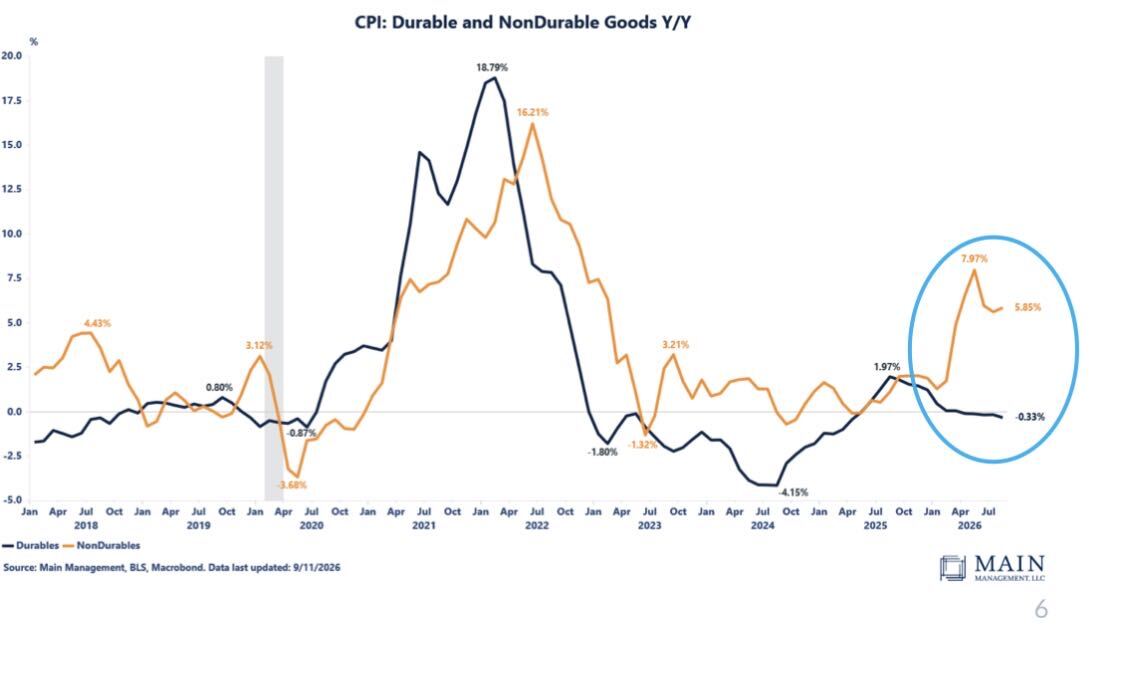
John Luke: and nondurables are driving it, with durable goods prices roughly flat year over year
Jake: The Atlanta Fed’s nowcast has climbed through the quarter, with consumer spending and private investment both adding to it
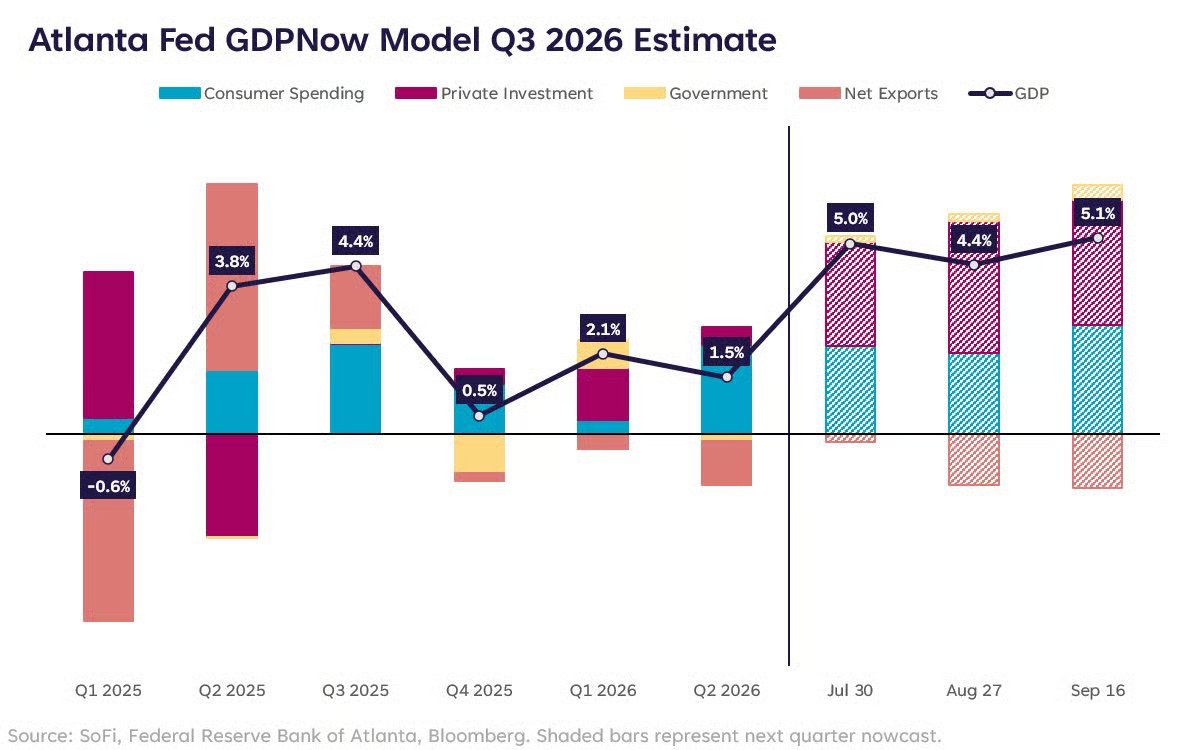 Graphic as of 09.16.2026
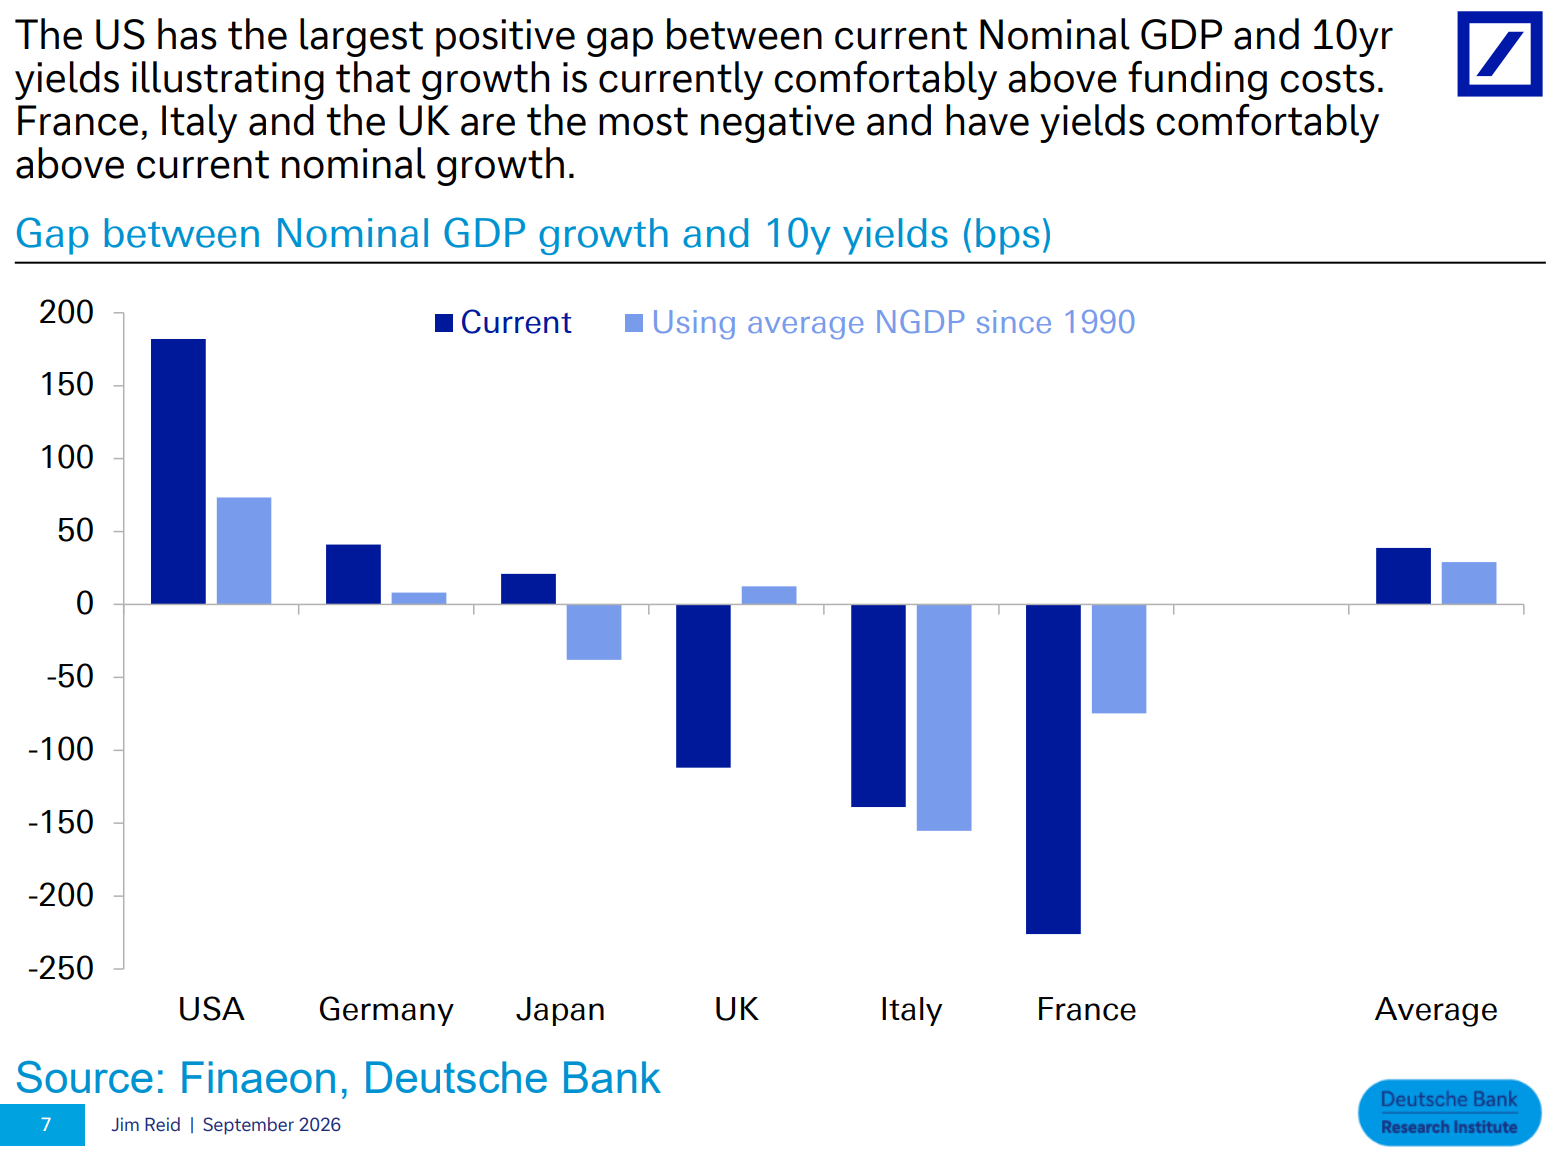
John: and with nominal growth above funding costs, the debt math sits better here than in the largest developed markets
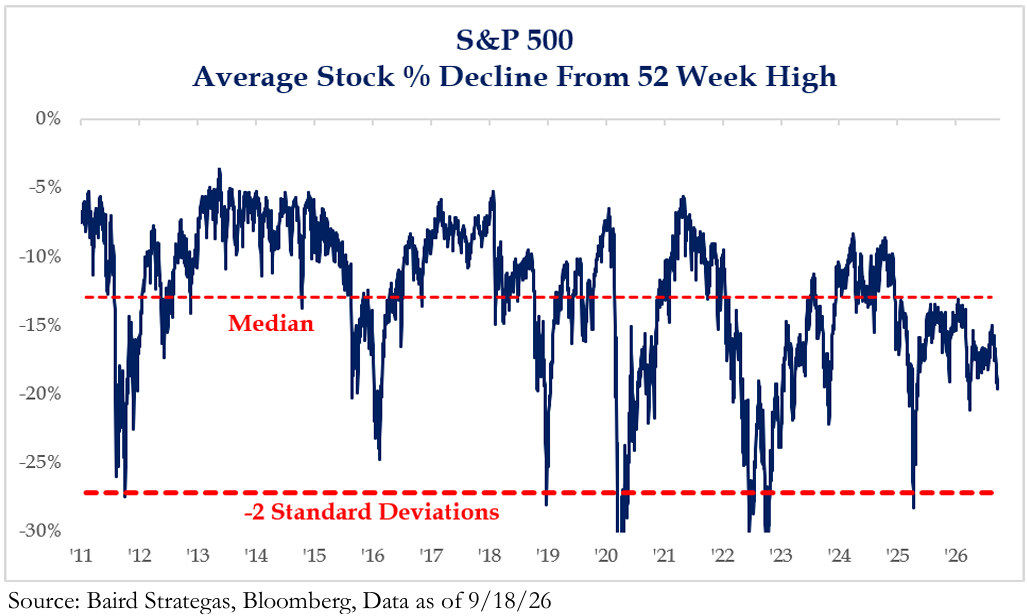
John Luke: The index keeps making this look easy, but the average stock is sitting well off of its own high
Beckham: and the drawdowns are common across most sectors
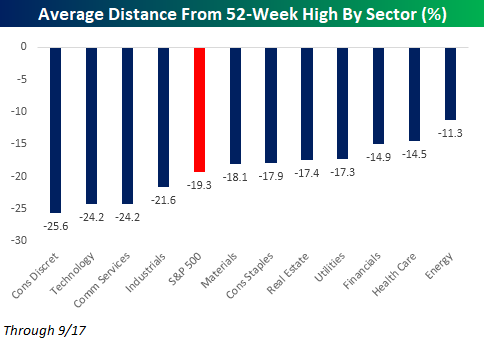 Source: Bespoke as of 9.18.2026
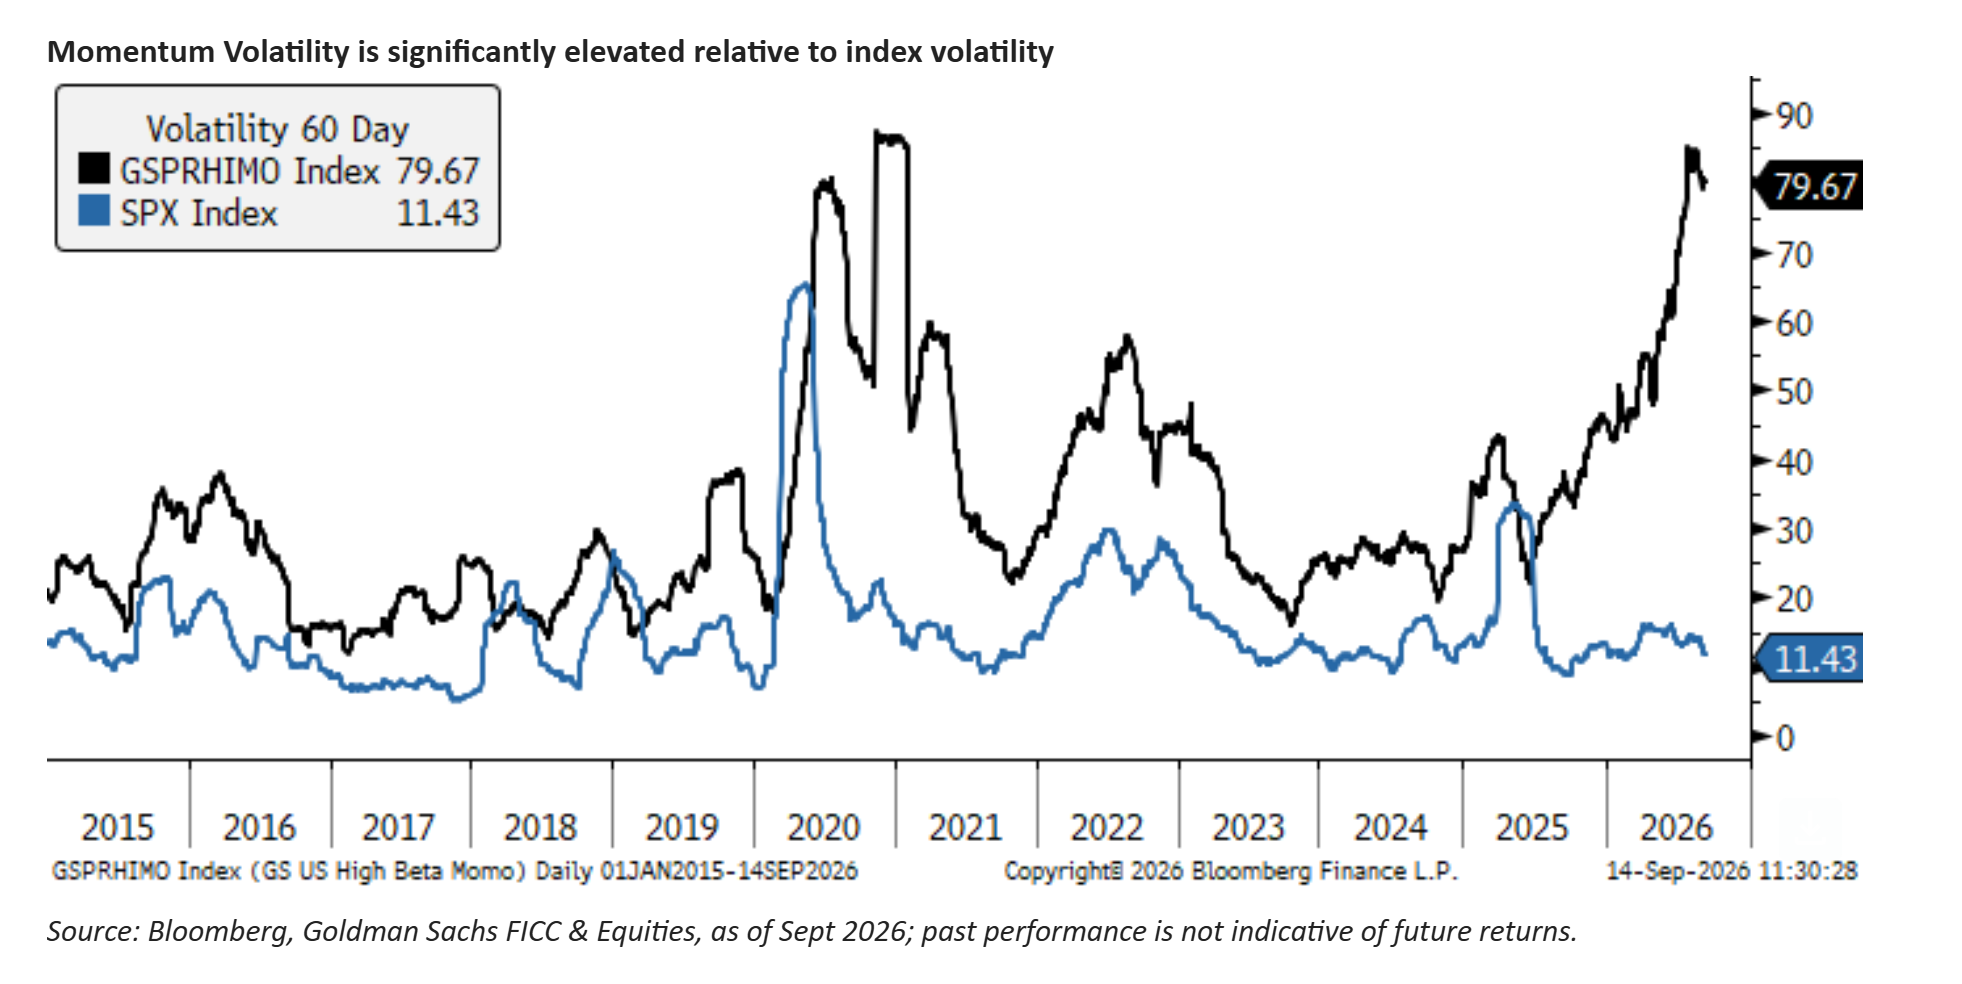
Mark: Momentum has been the epicenter, with the crowded trades swinging wildly day to day
Brett: The wall of worry is not only intact but growing
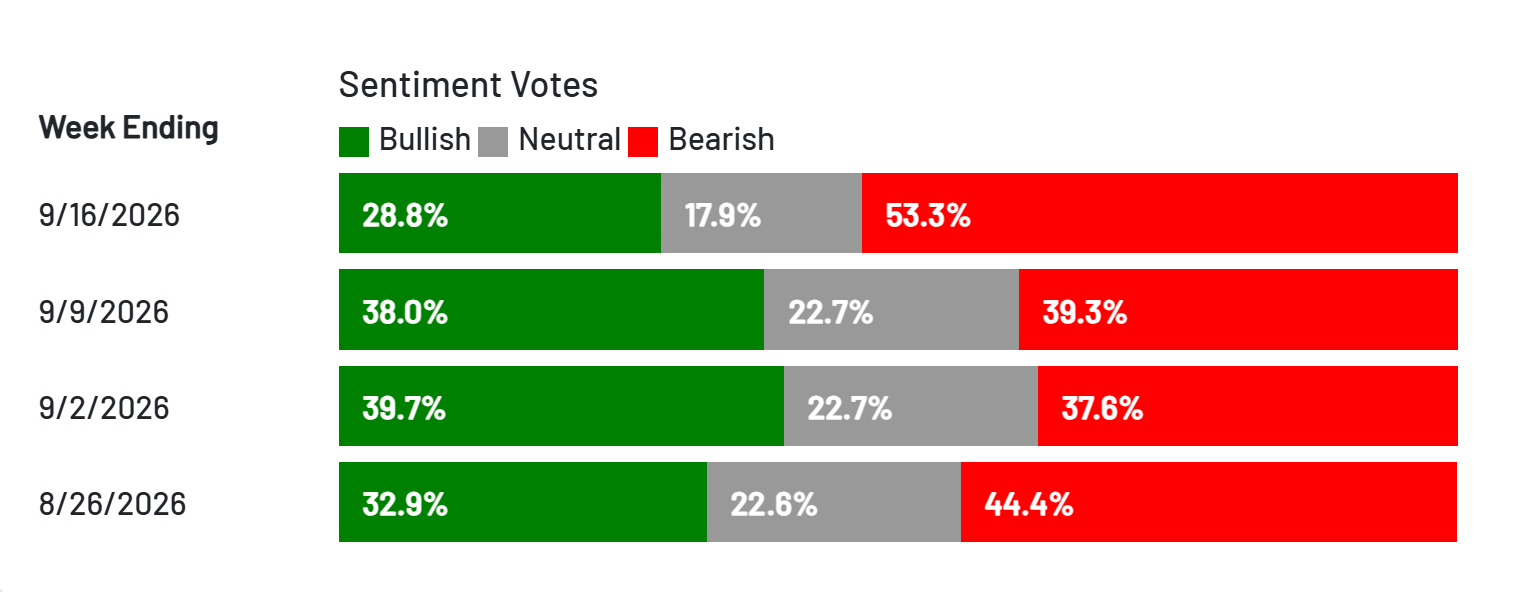 Source: AAII
Dave: This year’s estimates are not only bucking the “drift lower through the year” trend, but accelerating
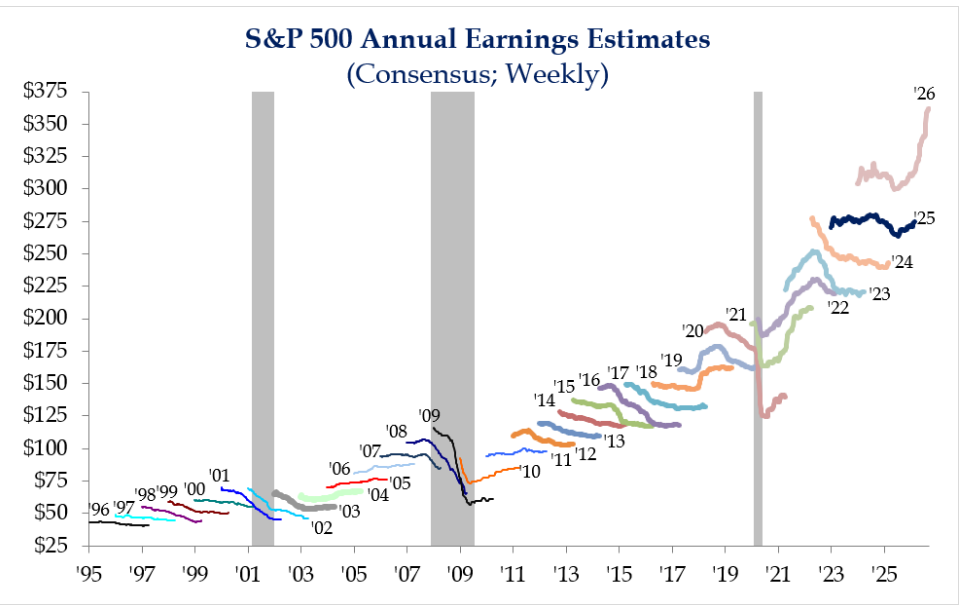 Source: Strategas as of 09.15.2026
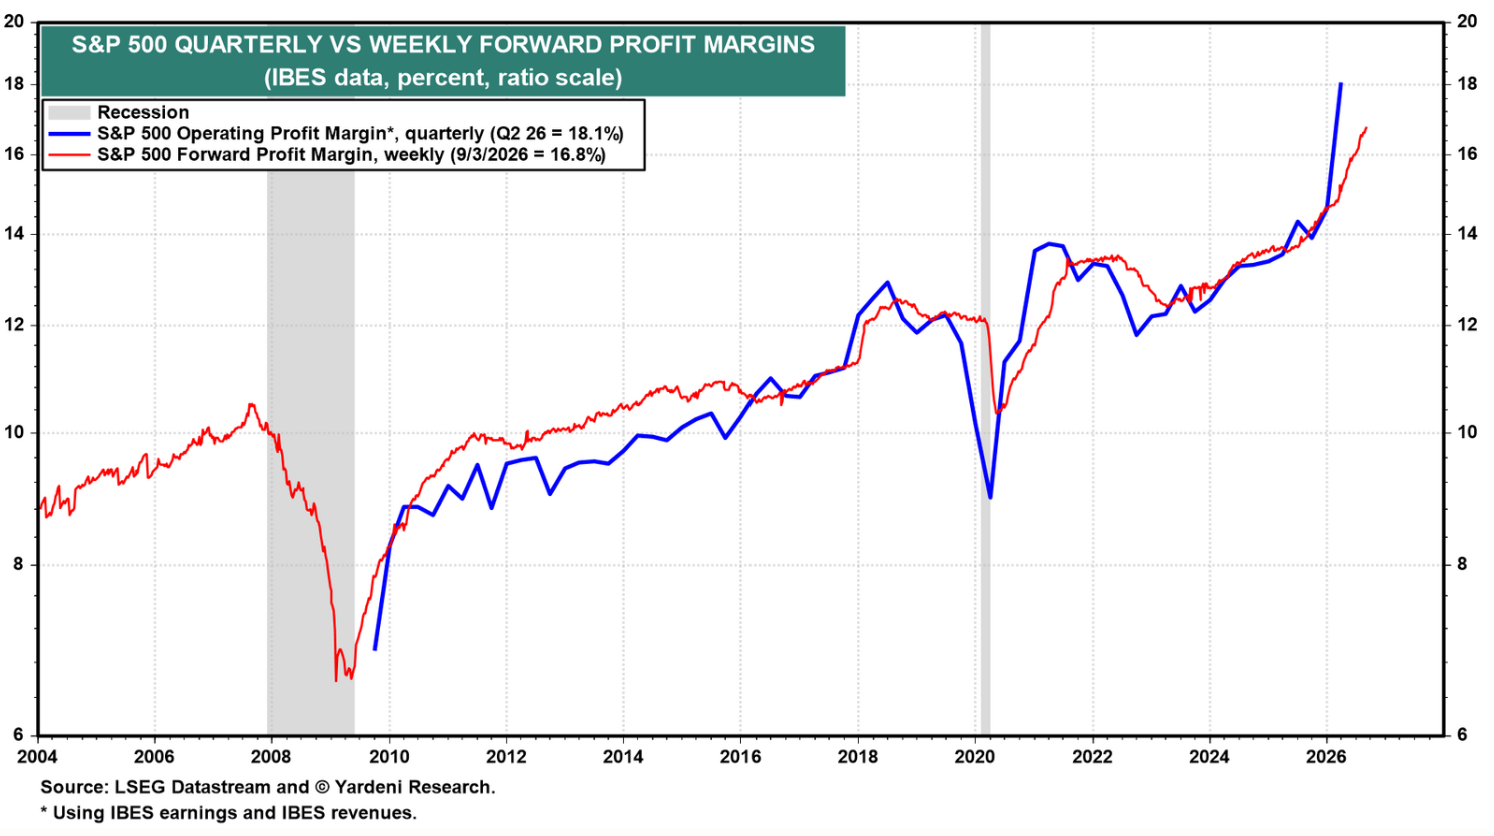
Brad: and margin expansion is doing much of that work
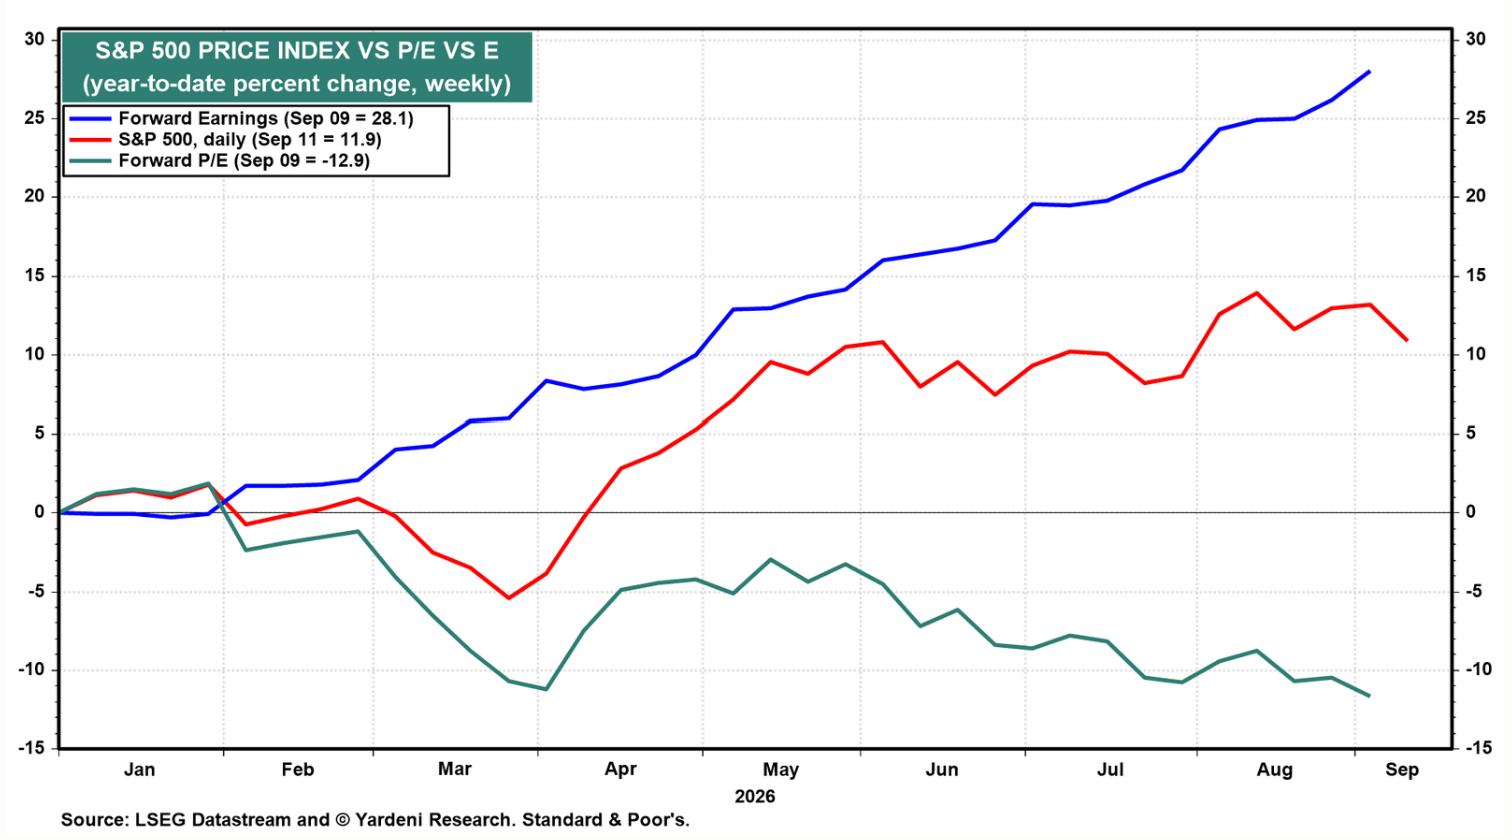
Beckham: The index’s earnings multiple continues to contract, with earnings growth outpacing the index’s gain by a wide margin
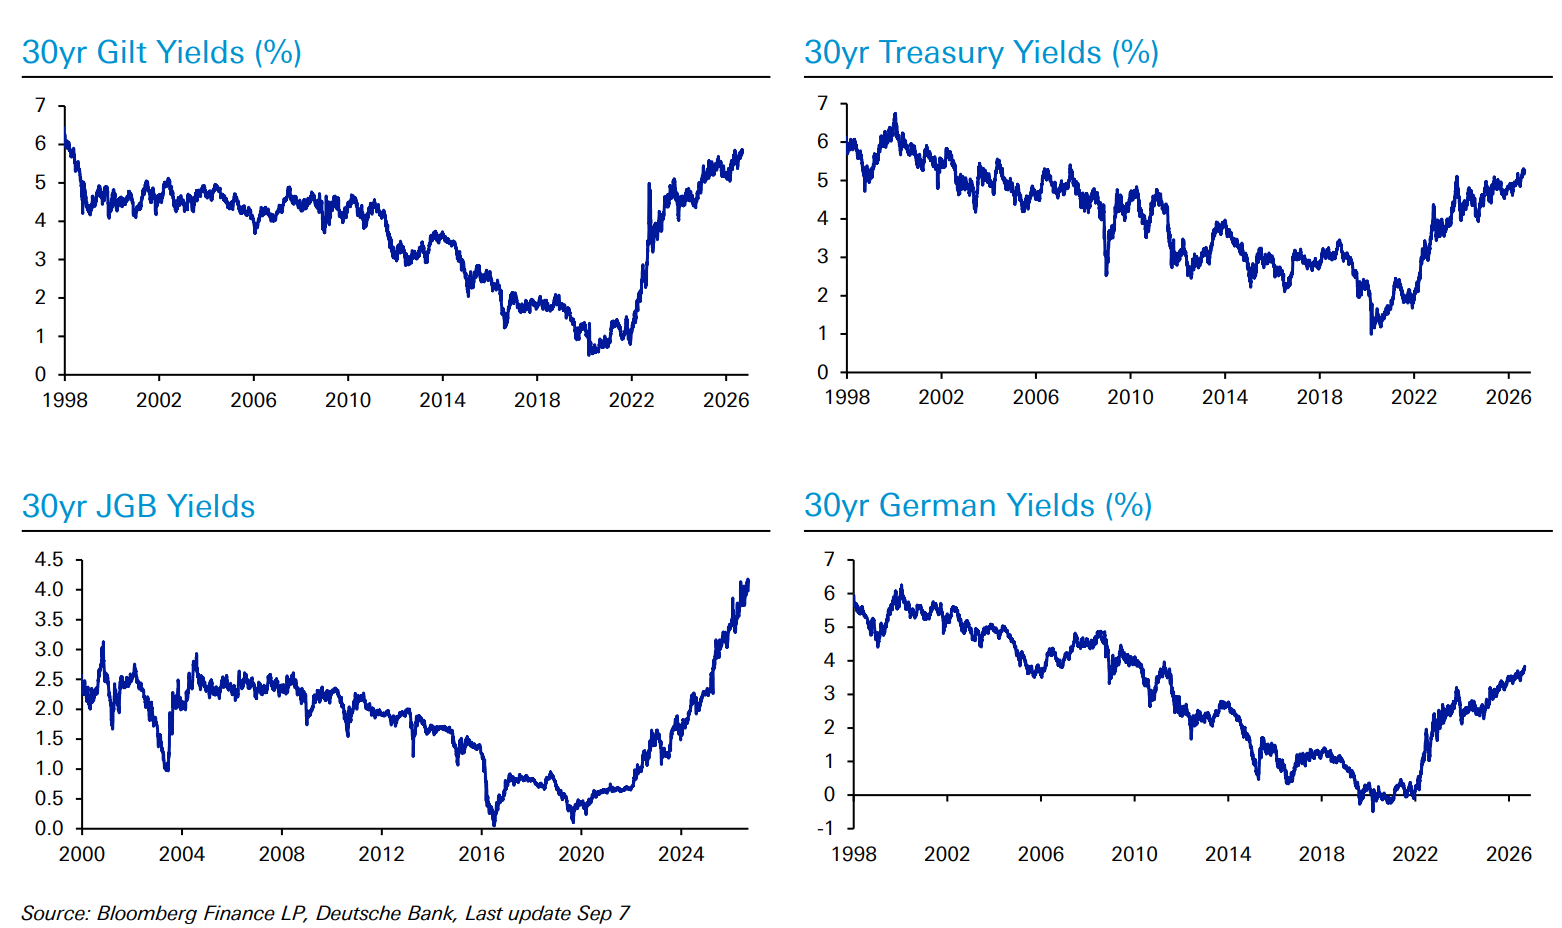
Brian: Rising yields are not just a US phenomenon
Dave: and at home, that has pushed net interest costs to nearly a fifth of federal tax revenue
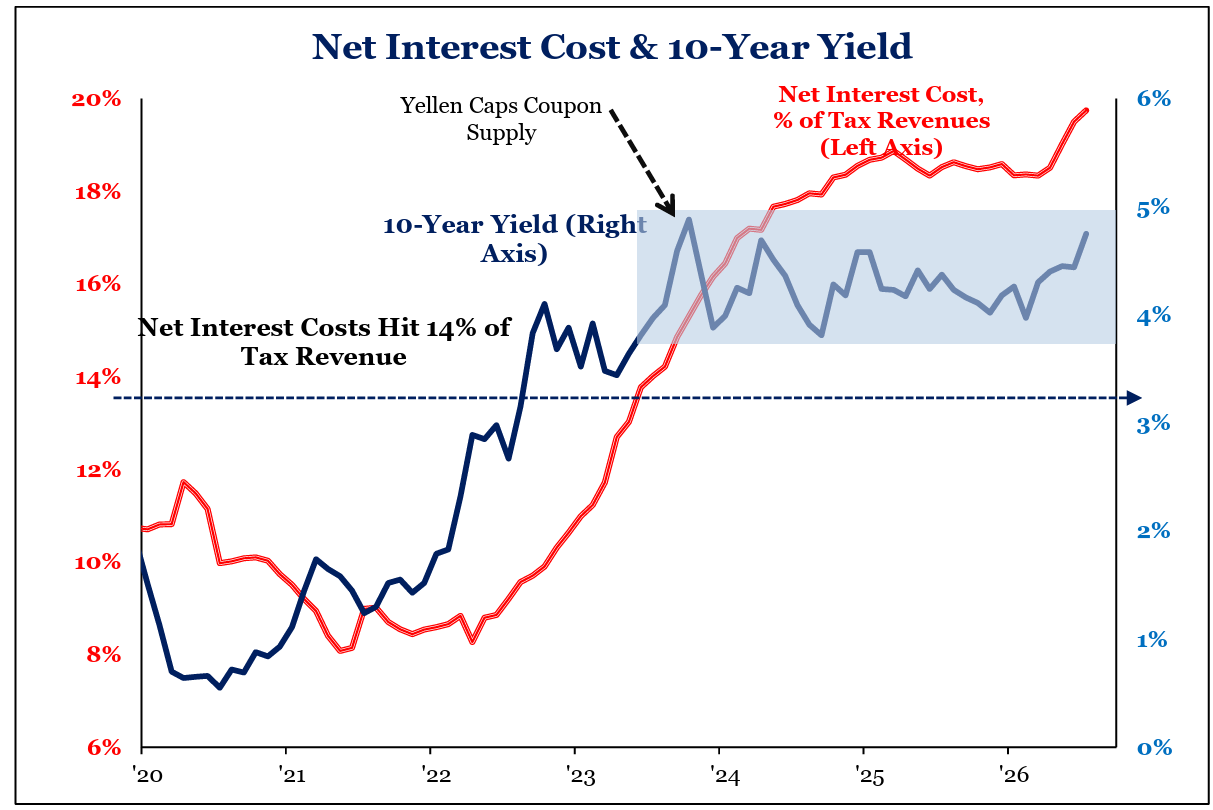 Source: Strategas as of 09.15.2026
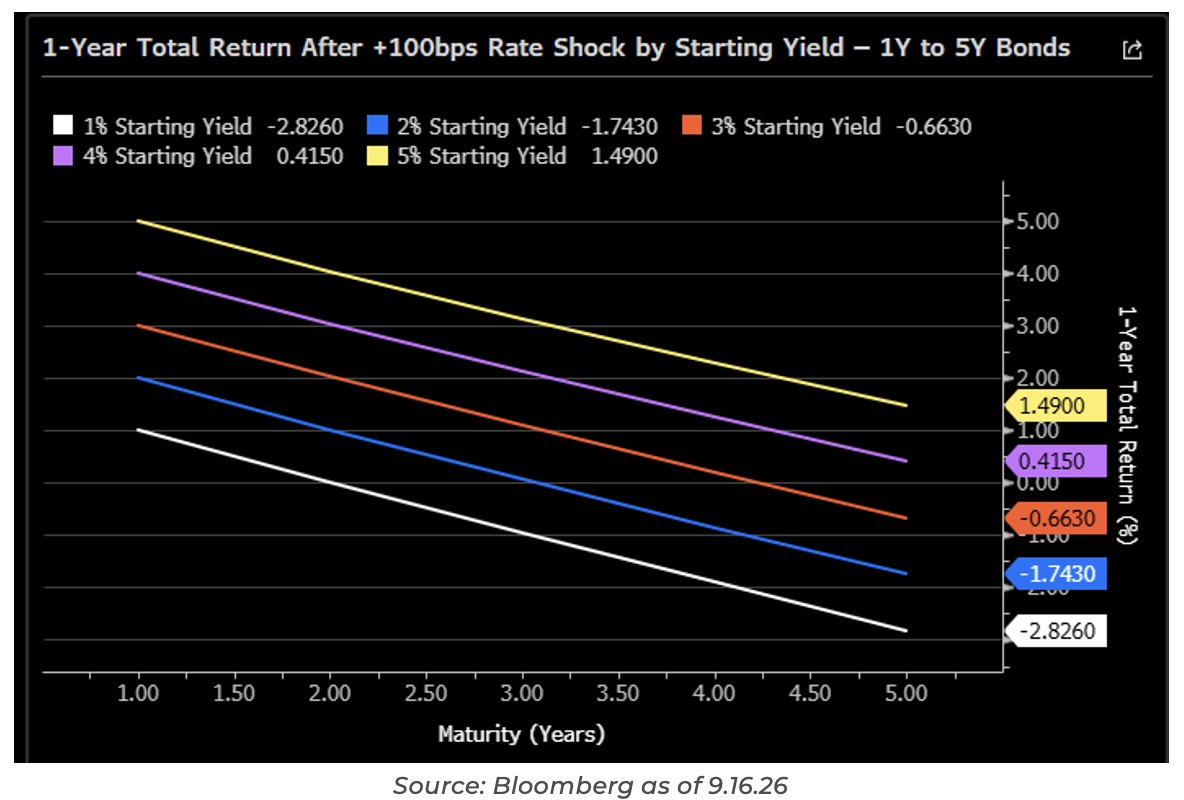
John Luke: For bond investors, a higher starting yield can help overcome a price drag
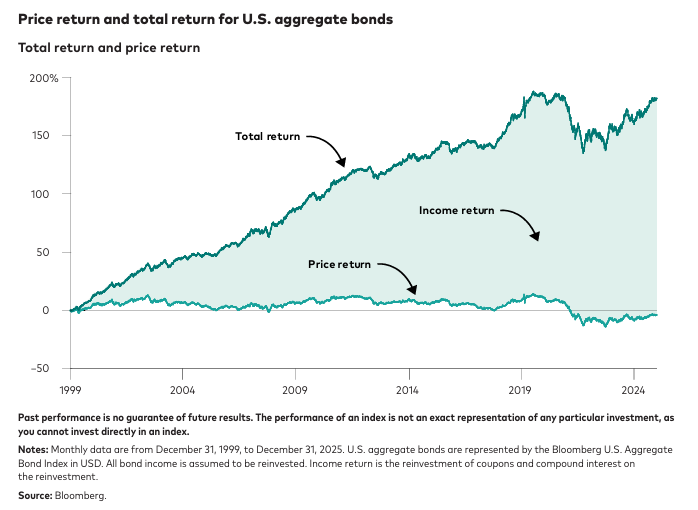
John Luke: and over the long run, it is that income, not price, that produces the total return
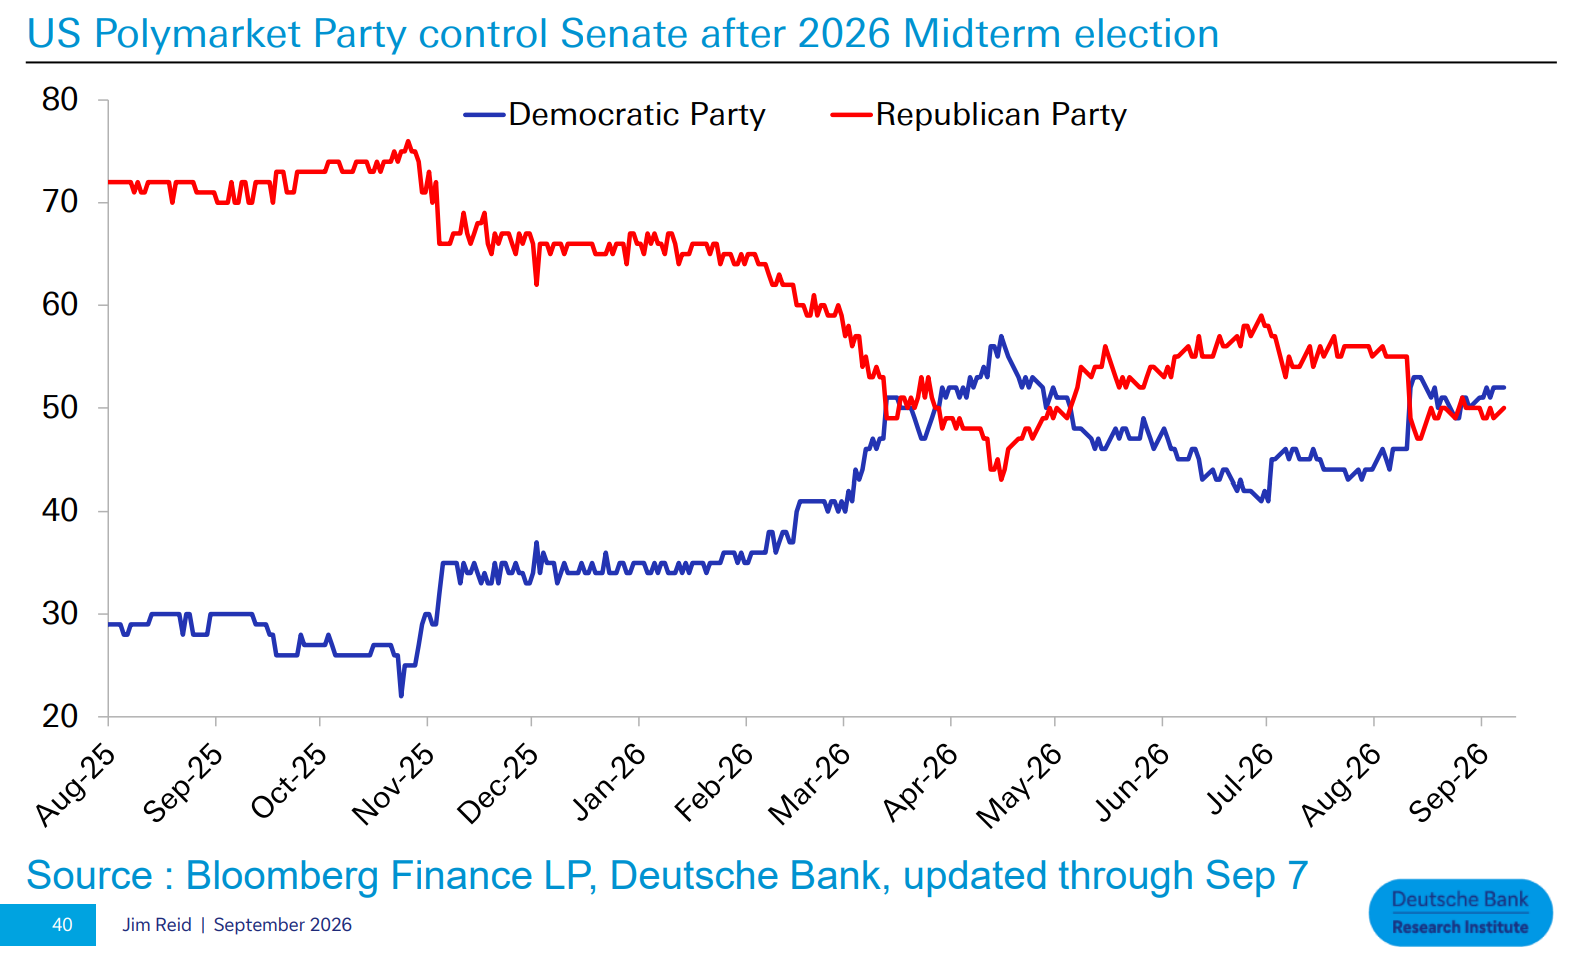
Joseph: Taking a step back, prediction markets have Senate control at close to even money
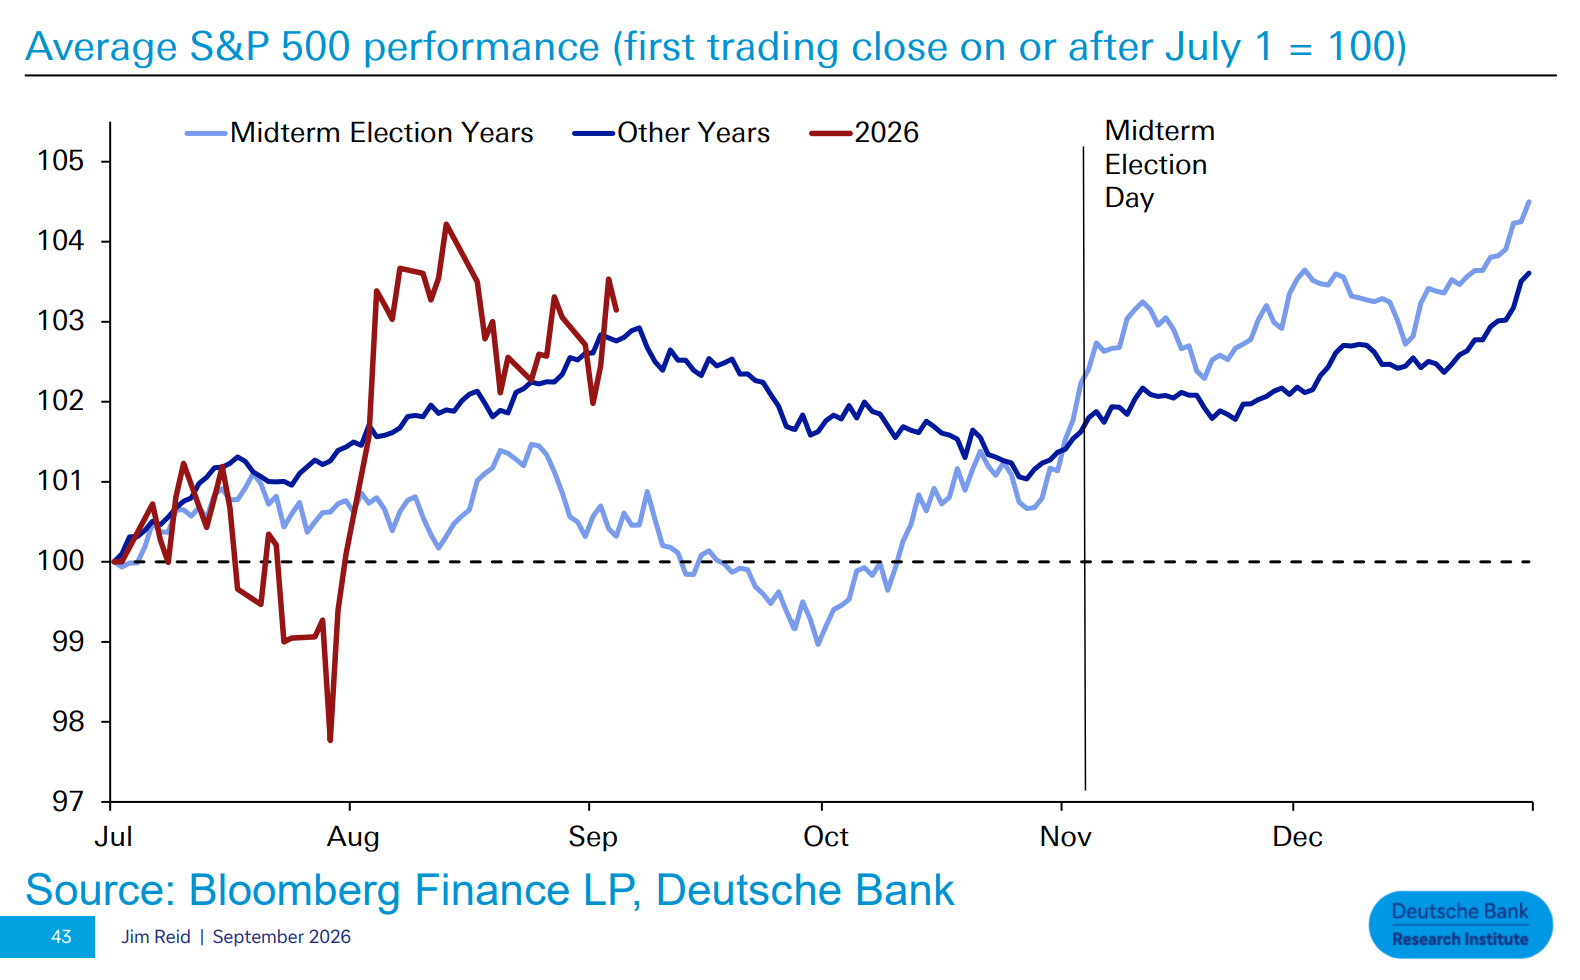
Dave: and in past midterm years, the S&P has tended to soften into October before rallying once the votes are counted
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward-looking statements cannot be guaranteed.
Projections or other forward-looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Be sure to consult with an investment & tax professional before implementing any investment strategy. Investing involves risk. Principal loss is possible.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2609-19.
