
In 1975, a Philadelphia inventor named Garrett Brown mailed around a reel of shots that seemed impossible at the time. One of them followed his girlfriend up the seventy-two steps at the entrance of the Philadelphia Museum of Art, and the remarkable thing about it was how completely unremarkable it looked. The camera simply floated up the stairs behind her without a wobble. Director John Avildsen saw the reel and called Brown to shoot those same steps with a relatively unknown actor… Sylvester Stallone, in his low-budget boxing movie Rocky.
What the audience never saw was the operator. Brown was carrying a camera, a battery, and a monitor on a spring-loaded arm bolted to a vest, absorbing every uneven stair with the structure so the shot would experience none of it.
We think that is the perfect metaphor when advisors ask what is being done when you have a strong allocation structure in place and rely on the solutions embedded in that structure to do the hard work.
Two Lines, Same Twelve Months
Draw a client’s year as a visible portfolio, and a managed one. The top line is the allocation and can stay flat over months, if not years, absent major structural opportunities. Meanwhile, active ETFs can manage risk without triggering taxes. Same client, same twelve months, same account.
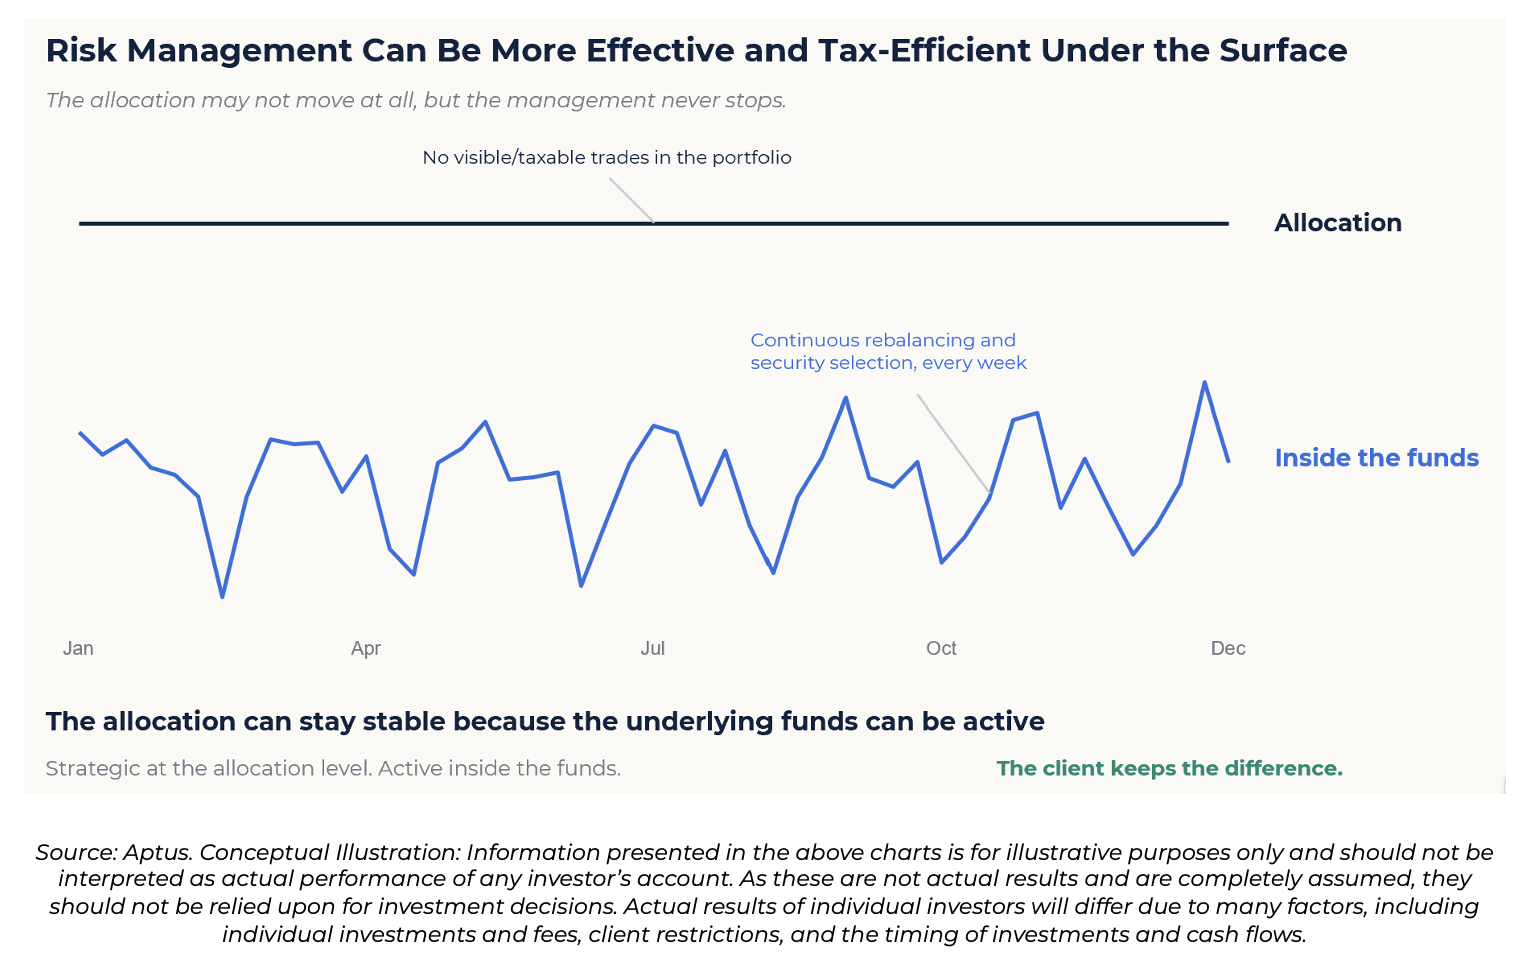
Some might read the top line as passive and the bottom as noise. Holding an allocation takes real conviction and becomes more comfortable for the client if somebody is doing the ongoing work to keep the balance in line with client objectives.
At that (less visible) level, lots can happen. Equity positioning can shift. Covered call positions are written, sometimes closed early to uncap upside when a position starts working, sometimes rolled up and out when harvesting premium makes sense. Puts get struck to conditions, level, and opportunity rather than to a quarterly reset date because choosing the first day of the quarter hands the client a timing lottery nobody agreed to play.
When options are used in an allocation and a drawdown arrives, those gains can potentially get monetized and rolled back into equities at lower prices, which, in our belief, is the whole point of carrying the hedge. While market exposure itself may scale down into weakness rather than somebody’s macro-opinion about the next six months.
None of that needs to show up as a line item on a statement, but all of it can show up in the result.
The Pieces May Be More Challenging to Hold than the Result
There are good reasons for the client to only see the top line; individual positions might benefit a portfolio but may have a path many would not willingly have the patience to sit through on their own. A long put may spend most of a year losing money, or a call written against a security that may rip looks like a mistake right up until you account for the premium collected across everything that did not.
Marked separately on a statement, each of those invites a question, and enough questions eventually produce a sale at the worst possible moment. Inside the fund wrapper it nets to a single price, so the client is left evaluating the outcome rather than the machinery. The gap between the volatility of the pieces and the volatility of the result is the difference between a strategy somebody holds for a decade and one they hold until the first uncomfortable statement.
The Price of Visible Motion
Clients want to know somebody is watching, and when markets move they want evidence that something is being done, which is neither irrational nor a character flaw. The problem is that the easiest way to demonstrate effort is often to overtrade the account.
In addition to the prospect of introducing poor timing, in a taxable account, a trade is often a realized gain on a 1099. Selling into a scare feels like management, and it bills like management when it shows up at tax time.
Take $100,000 earning an 8% annualized pre-tax return for thirty years, and hold that return constant across three scenarios so the only variable is where the tax lands. Realize the entire 8% every year at ordinary rates, and the investor finishes with roughly $437,161.
Realize half of that annual return (4% each year), whether through forced income from a less opportune structure or through the rebalancing and active decisions taken at the allocation level, and that becomes about $595,827. Defer the whole thing and pay once at 20% on liquidation, and the investor keeps roughly $825,013.
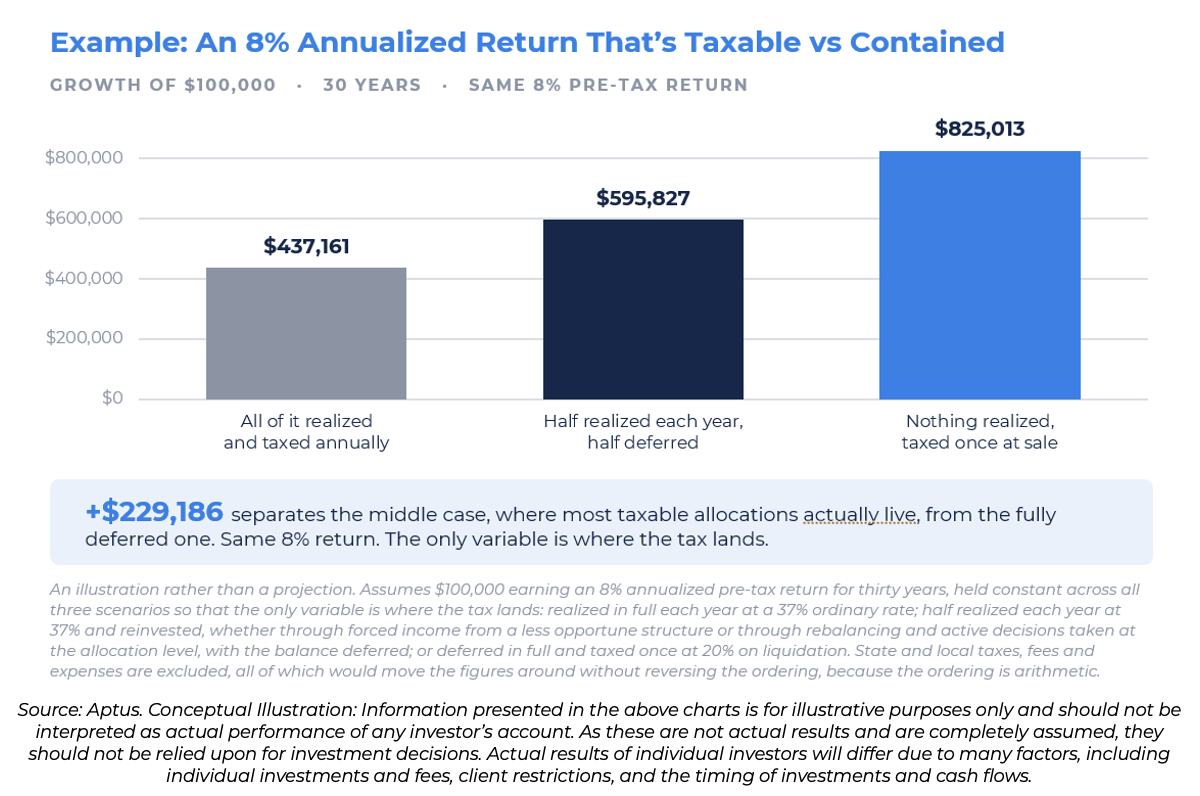
Most taxable allocations live in that middle case, which is $229,186 behind the deferred one, all produced by nothing but the location of the activity. The hardest part is not the mechanics; it is explaining stillness to somebody conditioned to equate stillness with neglect.
Helping The Client Be the Star
Two lines do most of that work for the advisors I talk to:
1. “The portfolios are managed every day, inside the funds you own, where adjusting the portfolio should not hand you a tax bill.”
2. “We do not force transactions that create taxable gains to prove we are working.”
Brown never argued that the Steadicam made walking upstairs easy. He argued that the struggle belonged somewhere other than in the picture, and the discipline of the rig is that none of the strain underneath the frame ever reached the audience.
An allocation that holds still is not always an unmanaged allocation. It is one where the management has been moved to the layer that can absorb it. The client sees a steady frame and needs to be told about the active management happening in that layer to know it is happening. I have come around to believing that is the highest compliment the work can receive.
Disclosures
Past performance is not indicative of future results. This material is not financial advice or an offer to sell any product. The information contained herein should not be considered a recommendation to purchase or sell any particular security. Forward looking statements cannot be guaranteed. Hypothetical examples are for illustrative purposes only, do not reflect the deduction of fees or expenses, and are not indicative of any actual investment result.
The growth illustration assumes an 8% annual pre-tax return on $100,000 over 30 years. In the first scenario the entire return is realized and taxed each year at a 37% ordinary income rate and reinvested net of tax. In the second, half of the return is realized and taxed each year at that same rate and reinvested, while the remaining half compounds untaxed and is taxed once at 20% upon liquidation. In the third, no gain is realized along the way and the entire gain is taxed once at 20% upon liquidation. Realized amounts taxed at long-term capital gains rates rather than ordinary income rates would narrow the differences shown. State and local taxes, fees and expenses are excluded. Information presented is for illustrative purposes only and should not be interpreted as the actual performance of any investor’s account. As these are not actual results and are completely assumed, they should not be relied upon for investment decisions. Actual results of individual investors will differ due to many factors, including individual investments and fees, client restrictions, and the timing of investments and cash flows.
Any tax information may change based on the specific facts and circumstances of the end investor. Additionally, the actual amounts and sources for tax reporting purposes will depend upon a Fund’s investment experience during the fiscal year and may be subject to changes based on tax regulations. Be sure to consult with an investment and tax professional before implementing any investment strategy.
This commentary offers generalized research, not personalized investment advice. It is for informational purposes only and does not constitute a complete description of our investment services or performance. Nothing in this commentary should be interpreted to state or imply that past results are an indication of future investment returns. All investments involve risk and unless otherwise stated, are not guaranteed. Investing involves risk. Principal loss is possible.
Options carry unique risks and are not suitable for all investors. Selling call options limits the upside potential of the underlying position, and purchased put options may expire worthless, resulting in the loss of the premium paid. There is no guarantee that a hedging strategy will achieve its objective or protect against loss.
Call options give the owner the right to buy the underlying security at the specified price within a specific time period. Put options give the owner the right to sell the underlying security at the specified price within a specific time period.
The opinions expressed are those of the Aptus Capital Investment Team as of the date of publication and are subject to change due to market or economic conditions and may not come to pass.
Advisory services are offered through Aptus Capital Advisors, LLC, a Registered Investment Adviser registered with the Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about the advisor, its investment strategies and objectives, is included in the firm’s Form ADV Part 2, which can be obtained, at no charge, by calling (251) 517-7198. Aptus Capital Advisors, LLC is headquartered in Fairhope, Alabama. ACA-2609-10.
